Market overview — definition, scope, and industry significance of Roof Top Tent Rentals Market
Our analysis indicates that the Roof Top Tent Rentals Market represents a dynamic segment of outdoor recreation and travel logistics, bridging automotive accessories and experiential tourism. Valued at $1.32 Billion in 2026, this market encompasses short-term leasing of hard shell, soft shell, and hybrid shelter systems mounted on SUVs, trucks, and vans, catering to commercial agencies, institutional bodies, and individual adventurers seeking turnkey overlanding experiences without capital-intensive equipment ownership.
Key market drivers, restraints, challenges, and opportunities shaping Roof Top Tent Rentals Market
The Roof Top Tent Rentals Market industry trends are primarily accelerated by surging consumer demand for decentralized travel, domestic road trips, and off-grid exploration. However, supply chain constraints involving aluminum framing materials and stringent Department of Transportation payload safety regulations act as notable restraints. Opportunities thrive in specialized rental platforms and eco-tourism partnerships, enabling operators to scale fleet sizes while mitigating vehicle wear and tear during rugged expeditions.
Emerging trends and growth patterns in Roof Top Tent Rentals Market
The shift toward lightweight, aerodynamic hard shell systems and all-season hybrid tent setups is transforming fleet acquisition strategies. Our research reveals that modern consumers increasingly demand seamless digital booking integrations alongside pre-configured overlanding kits featuring portable power stations and slide-out kitchen modules, directly influencing how rental agencies bundle accessories to maximize daily rental yields and capture high-value customer segments.
COVID-19 impact analysis — how the pandemic affected Roof Top Tent Rentals Market and the recovery trajectory
During the pandemic, the Roof Top Tent Rentals Market analysis demonstrated remarkable resilience as international travel restrictions redirected discretionary spending toward socially distanced domestic road trips and state park overlanding. This catalyzed a rapid post-pandemic recovery trajectory, transforming transient interest into permanent lifestyle adoption and forcing fleet operators to aggressively expand inventory to meet unprecedented regional demand for outdoor recreation.
Competitive landscape — major players, market concentration, and strategic dynamics
The market features a fragmented competitive landscape characterized by specialized regional operators and expansive multi-market platforms. Key participants such as Indie Campers S.A., Wicked Campers Pty Ltd, and Outdoorsy Inc. leverage sophisticated digital asset-sharing networks and strategic vehicle fleet partnerships to maintain high utilization rates, whereas boutique providers focus on localized, highly customized off-road outfitting.
Executive summary — high-level synthesis of key findings about Roof Top Tent Rentals Market
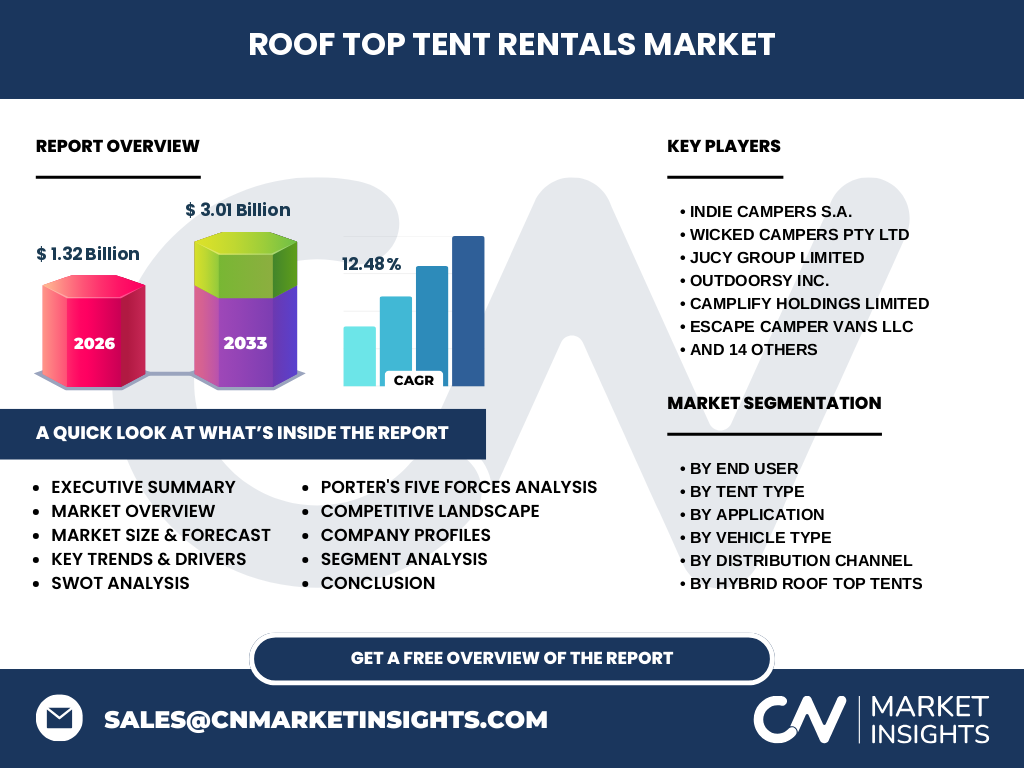
Our comprehensive evaluation highlights that the Roof Top Tent Rentals Market market size is poised for exceptional expansion, driven by widespread adoption of adventure travel and flexible van-life lifestyle choices. Generating robust momentum, the sector is projected to reach $3.01 Billion by 2033, expanding at a remarkable compound annual growth rate of 12.48% from 2027 onward, underlining lucrative entry points for investors and equipment manufacturers alike.
Market forecast — projected growth from 2027 to 2033
Based on our econometric models, the Roof Top Tent Rentals Market will experience accelerated valuation gains between 2027 and 2033, scaling systematically from its 2026 baseline of $1.32 Billion to culminate at $3.01 Billion. This expansion is sustained by a steady 12.48% CAGR, fueled by rising vehicle upfitting rates across light trucks and SUVs alongside institutional investments in ecotourism infrastructure.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation is categorized by end user (Individual, Commercial, Institutional), tent type (Soft Shell, Hard Shell, Hybrid), application (Camping, Overlanding, Adventure Travel, Other), vehicle type (SUVs, Trucks, Cars, Vans), and distribution channel (Online Platforms, Offline Stores, Rental Agencies). Hard shell variants—such as aluminum and clamshell designs—command premium pricing due to rapid deployment speeds, while online booking platforms dominate customer acquisition pathways.
Regional market analysis — geographic distribution and performance across regions
Geographic performance reveals pronounced concentration in regions with extensive public federal land access, robust unpaved road networks, and well-established camping infrastructure. North America and Europe currently dominate revenue generation, supported by high consumer disposable incomes and mature rental ecosystems, whereas Asia-Pacific emerges as an ultra-high-growth frontier driven by expanding middle-class enthusiasm for weekend motorized excursions and domestic tourism.
In-depth regional review — detailed examination of key regional markets
North American growth is anchored by extensive national park networks and concentrated overlanding hubs in the western United States, creating high utilization for truck and SUV-mounted setups. Conversely, the European market favors compact aerodynamic hard shell tents paired with efficient camper vans, navigating stricter urban emission zones and narrower rural access routes through specialized cross-border rental networks.
Company profiles — strategic positioning of leading companies in Roof Top Tent Rentals Market
Industry leaders maintain distinct competitive moats through specialized asset management. Firms like Camplify Holdings Limited and Escape Camper Vans LLC optimize peer-to-peer and corporate-owned fleets to balance peak seasonal demand, while specialized operators such as Bushlore Africa and Safari Car Rental cater to rugged international safari expeditions requiring heavy-duty expedition-grade 4x4 integration and specialized recovery gear.
Porter's Five Forces analysis — competitive forces assessment
The threat of new entrants remains moderate to high due to low initial software setup costs, though capital expenditures required for vehicle and tent fleets create barriers. Supplier power is concentrated among premium aluminum fabricators and automotive rack manufacturers, while buyer power is mitigated by the experiential nature of specialized adventure travel and differentiated fleet offerings.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Core strengths include high asset utilization flexibility and strong experiential consumer demand. Weaknesses involve seasonal revenue fluctuations and high vehicle maintenance overheads. Opportunities lie in integrating autonomous booking tech and expanding into institutional educational expeditions, while primary threats encompass macroeconomic downturns impacting discretionary travel budgets and tightening vehicle modification laws.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with raw material extraction—primarily aluminum, ripstop canvas, and reinforced polymers—processed by component manufacturers into modular roof top tents. These units are acquired by rental fleets, marketed through digital aggregator platforms or direct offline stores, and finally delivered to end-users engaging in camping and overlanding journeys.
Investment insights — strategic recommendations and high-potential areas
Investors should target acquisitions and technology partnerships within digital rental management platforms and fleets deploying all-season hybrid roof top tents. Prioritizing operators with integrated SUV and truck cross-docking capabilities ensures maximum resilience against seasonal demand shocks and captures high-margin adventure travel demographics effectively.
Conclusion and key takeaways
The Roof Top Tent Rentals Market industry trends validate a thriving, high-growth ecosystem scaling toward $3.01 Billion by 2033. Success in this landscape hinges on fleet diversification across hard and soft shell configurations, seamless mobile-first booking integration, and strategic adaptation to regional overlanding regulations to capture long-term consumer enthusiasm.
Research methodology — detail how baseline estimates are triangulated
Our market estimation employs a rigorous triangulation methodology combining primary qualitative interviews with C-level executives of rental agencies like GoCamp and Jucy Group Limited, secondary macroeconomic indicators from tourism registries, and quantitative trade data tracking vehicle upfitting and outdoor equipment import-export flows to establish accurate baseline valuations.
Scope of the report — coverage parameters and limitations
This report covers global revenue streams, volume metrics, and strategic analyses of the Roof Top Tent Rentals Market across specified vehicle types, tent configurations, and end-user segments from 2026 to 2033. Excluded from this scope are permanent recreational vehicle (RV) coach-building and unmounted ground tent retail markets, maintaining strict focus on vehicle-mounted rental systems.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent market activities feature prominent cross-border acquisitions and technological alliances among key players like Indie Campers S.A. and Outdoorsy Inc., aimed at expanding geographic footprints. Companies are increasingly launching modular, climate-controlled hard shell tent variants designed specifically for electric vehicles, addressing sustainability trends and modern powertrain transitions.