Market overview and structural scope of the Rock Drilling Equipment Market
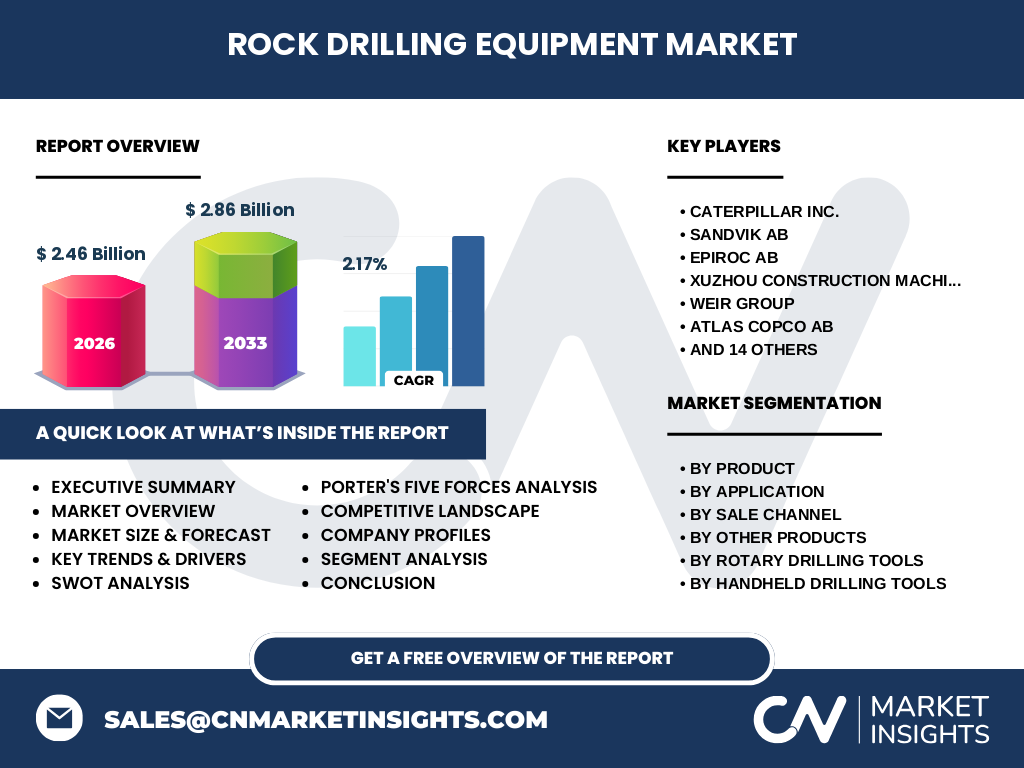
Our analysis indicates that the Rock Drilling Equipment Market represents a critical industrial backbone valued at $2.46 Billion in 2026, scaling toward $2.86 Billion by 2033 at a 2.17% CAGR. This sector encompasses specialized machinery such as Rotary, Down-The-Hole (DTH), Horizontal, and Handheld drilling tools. These systems are indispensable for hard rock extraction, tunneling logistics, and subsurface resource exploration across global mining, quarrying, and civil infrastructure projects.
Structural Growth Drivers and Market Restraints
The market is propelled by surging demand for critical minerals required in the energy transition, alongside aggressive urbanization driving underground infrastructure. However, growth is heavily constrained by stringent OSHA and MSHA emissions mandates, high upfront capital expenditure for fleet modernization, and volatile raw material costs for tungsten carbide and steel alloys. Opportunities lie in automated, sensor-equipped rigs that mitigate skilled labor shortages in remote extraction sites.
The Shift Toward Electrification and Automation
Industry trends reveal a definitive pivot away from diesel-hydraulic units toward battery-electric and tethered electric rigs to reduce underground ventilation loads and carbon footprints. Companies like Epiroc AB and Sandvik AB are leading this technological wave with tele-remote operations and automated drill plans. This transition favors equipment manufacturers with advanced mechatronics capabilities, drastically improving operator safety and borehole accuracy in deep-level mining.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The pandemic severely disrupted global supply chains, causing acute shortages of hydraulic valves and specialized steel components while halting capital projects worldwide. Recovery has been uneven, accelerated by government stimulus packages targeting critical infrastructure and a post-lockdown commodity supercycle. Supply chain resilience and localized manufacturing footprints have emerged as vital survival strategies for leading equipment providers navigating lingering macroeconomic headwinds.
Competitive Benchmarking and Industry Concentration
The competitive landscape is characterized by moderate consolidation, dominated by tier-one giants like Caterpillar Inc., Sandvik AB, and Epiroc AB, alongside agile specialists such as Mincon Group plc and Numa Tool Company. Major players leverage expansive global dealer networks and aftermarket service agreements to secure recurring revenue streams, forcing niche manufacturers to compete through specialized proprietary metallurgy and tailored DTH hammer designs.
Executive Summary of the Rock Drilling Equipment Market
Our comprehensive Rock Drilling Equipment Market analysis projects steady expansion, reaching $2.86 Billion by 2033 from a 2026 baseline of $2.46 Billion. While growth appears modest at a 2.17% CAGR, the underlying technological displacement cycle toward electric and automated rigs offers high-margin replacement opportunities. Strategic investments in aftermarket digital solutions and eco-efficient tooling remain paramount for sustaining competitive advantage.
Long-Term Market Forecast from 2027 to 2033
Based on our research, the market will expand steadily at a 2.17% CAGR, growing from its 2026 valuation of $2.46 Billion to reach $2.86 Billion by 2033. This trajectory assumes sustained commodity demand, particularly for copper, lithium, and gold, alongside sustained public investments in mass transit tunneling. Adoption rates of automated Horizontal Directional Drilling (HDD) rigs will heavily dictate revenue upside during the latter half of the forecast window.
Segmentation Analysis across Products, Applications, and Sales Channels
Market segmentation highlights diverse operational dependencies: By Product, categories span Rotary, DTH, Horizontal, and Handheld tools, featuring sub-segments like Tricone Bits and PDC Bits. By Application, demand splits across Mining, Construction, Quarrying, and Oil & Gas. By Sales Channel, the division between Original Equipment Manufacturer (OEM) sales and high-margin Aftermarket consumable replacements dictates corporate revenue stability across commodity price cycles.
Geographic Distribution and Regional Market Dynamics
Regional performance varies significantly based on localized mineral endowments and infrastructure spending. The Asia-Pacific region dominates volume demand driven by intensive coal and metal mining in Australia and expanding construction across emerging economies. Conversely, North America and Europe prioritize technology-heavy replacement cycles, emphasizing low-emission electric units and automated surface drilling to comply with stringent environmental regulations enforced by bodies like the EPA and EU directives.
In-Depth Regional Review of High-Growth Zones
Latin America and Africa represent vital frontiers for heavy-duty mining equipment, anchored by large-scale open-pit copper and iron ore operations. However, logistical bottlenecks at regional ports and import tariffs on specialized steel components frequently constrain equipment deployment timelines. Meanwhile, North American operations focus on technological retrofits, integrating advanced monitoring systems to optimize fleet productivity in mature, high-cost extraction environments.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct strategic postures: Sandvik AB and Epiroc AB focus heavily on autonomous, electric underground fleets; Caterpillar Inc. leverages its massive distribution network for integrated surface mining solutions; and specialized players like Mincon Group plc and Numa Tool Company capture market share through high-efficiency DTH hammers and proprietary bit metallurgy designed for extreme geological formations.
Porter's Five Forces Analysis of Competitive Pressures
The threat of new entrants is low due to extreme R&D barriers, intellectual property surrounding drill string metallurgy, and the capital intensity of global dealer networks. Bargaining power of buyers is moderate to high, as major mining conglomerates demand customized, high-durability tooling. Supplier power remains moderate, governed by high-grade steel and tungsten carbide input costs, while substitute threats are negligible given the physical necessity of mechanical rock breakage.
SWOT Analysis of the Rock Drilling Equipment Sector
Key strengths include advanced proprietary metallurgy and established global service footprints. Weaknesses involve high susceptibility to cyclical commodity crashes and carbon-intensive manufacturing processes. Opportunities abound in battery-electric fleet conversion and AI-driven predictive maintenance software. Threats center on geopolitical trade tensions impacting raw material supply chains and tightening regulatory restrictions on fossil-fueled industrial machinery.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material sourcing of refined steel, cobalt, and tungsten carbide, progressing through precision machining, heat treatment, and assembly by OEMs like XCMG Group and Furukawa Rock Drill. Equipment flows through global logistics hubs to mining houses and civil contractors, culminating in extensive aftermarket repair and consumable bit replacement cycles managed by regional distributors and direct service teams.
Investment Insights and High-Potential Strategic Areas
Our analysis indicates that investors should prioritize companies specializing in tele-remote autonomy, battery-electric conversion kits, and proprietary consumable manufacturing. Because aftermarket tooling generates recurring revenue buffers during mining downturns, firms with robust consumable distribution networks offer superior risk-adjusted returns compared to pure-play heavy equipment manufacturers vulnerable to capital expenditure freezes.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Rock Drilling Equipment Market offers stable, defensive growth, advancing from $2.46 Billion in 2026 to $2.86 Billion by 2033. Success in this evolving landscape demands an aggressive pivot toward sustainable, electrified, and automated drilling technologies. Stakeholders must balance capital discipline with targeted R&D investments to capture replacement demand driven by tightening global environmental and safety mandates.
Research Methodology and Baseline Triangulation
Our baseline estimates are derived through rigorous data triangulation, combining primary stakeholder interviews with C-level executives, engineering leads, and procurement managers across major mining houses. This primary intelligence is cross-referenced against official trade registry data, customs import-export logs, and secondary macroeconomic indicators to ensure robust, highly accurate market sizing and growth projections.
Scope of the Report and Coverage Parameters
This report covers the global Rock Drilling Equipment Market industry trends, sizing the sector from 2027 to 2033 with a 2026 base year. The analysis encompasses all major product categories, application verticals, and sales channels. Geographic scope spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, subject to standard macroeconomic forecasting assumptions and trade data availability constraints.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry activity highlights a surge in joint ventures focused on zero-emission underground mining. Major market participants have ramped up commercial rollouts of zero-emission drill rigs and AI-driven automated rod-handling systems. Strategic mergers and acquisitions are increasingly targeted at securing proprietary software capabilities for remote fleet monitoring and advanced drill-plan optimization.