Market Overview of the Hardware Market
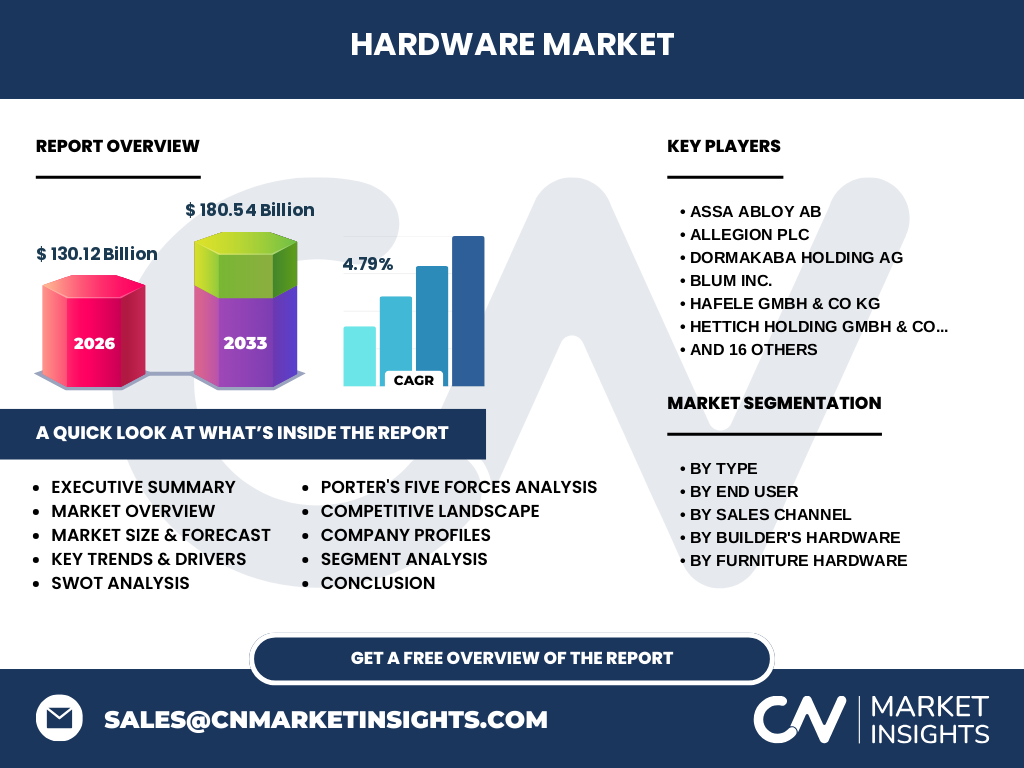
Our analysis indicates the Hardware Market market size stands at 130.12 Billion in 2026. This foundational sector encompasses essential metallic and polymeric components, serving critical structural and functional roles in global construction and manufacturing value chains.
Key Market Drivers and Restraints
The Hardware Market industry trends are heavily propelled by urbanization and smart-building adoption, though volatile raw material costs for steel and aluminum present ongoing margin pressures for manufacturers navigating localized supply chain bottlenecks.
Emerging Trends in the Hardware Market
The shift toward IoT-integrated access control and sustainable zinc-alloy manufacturing is reshaping demand. Smart architecture requirements favor agile innovators capable of merging mechanical durability with digital connectivity.
COVID-19 Impact Analysis on Hardware Supply Chains
Pandemic-era logistical bottlenecks severely disrupted ocean freight routes through major ports like Shanghai and Rotterdam. However, the sector has rebounded via nearshoring strategies and automated inventory buffers.
Competitive Landscape and Market Concentration
The competitive arena features established heavyweights such as Assa Abloy AB and Allegion PLC, alongside precision specialists like Blum Inc., driving high market concentration through aggressive intellectual property portfolios.
Executive Summary of the Hardware Market Report
Based on our comprehensive research, the market is poised to reach 180.54 Billion by 2033. Strategic consolidation and eco-friendly electroplating innovations will define market leadership over the forecast horizon.
Market Forecast and Growth Projections (2027 to 2033)
Projected to scale from 2027 to 2033 at a steady CAGR of 4.79%, the market exhibits robust defensive characteristics driven by mandatory infrastructure upgrades and residential renovation cycles.
Segmentation Analysis by Type and End-User
The market bifurcates into Furniture Hardware and Builder's Hardware, servicing B2B commercial contractors and B2C retail channels through OEM partnerships and aftermarket distribution networks.
Regional Market Analysis and Geographic Performance
Geographic performance highlights North America and Europe as high-value innovation hubs, while Asia-Pacific remains the undisputed volume engine, anchored by massive construction output in emerging economies.
In-Depth Regional Review of Manufacturing Hubs
Regional scrutiny reveals that stringent European CE EN certifications favor high-compliance players like Dormakaba Holding AG, whereas North American markets prioritize rapid logistics fulfillment through extensive distributor networks.
Company Profiles and Strategic Positioning
Industry leaders like Hafele GmbH & Co KG and Hettich Holding GmbH & Co. oHG maintain dominance via proprietary motion technologies, while Godrej Enterprises Group captures substantial share in developing Asian markets.
Porter's Five Forces Analysis of the Sector
Supplier power remains moderate due to consolidated steel pricing, whereas buyer power is high in retail channels, exerting continuous pricing pressure on component manufacturers across the board.
SWOT Analysis of the Hardware Sector
Key strengths lie in unmatched product durability, while weaknesses involve exposure to raw material price volatility. Opportunities in smart fasteners contrast with threats from macroeconomic inflationary pressures.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with primary metal refiners supplying aluminum and stainless steel, flows through precision stamping and die-casting facilities, and terminates via OEM assembly lines or retail hardware distributors.
Investment Insights and High-Potential Areas
Our analysis highlights automated drawer systems and biometric locking mechanisms as prime investment targets, offering superior margin expansion potential for private equity firms targeting industrial technology.
Conclusion and Strategic Takeaways
Sustained success in this sector demands continuous R&D investment in sustainable materials and digital integration, ensuring resilience against shifting global building codes and supply chain disruptions.
Research Methodology for Baseline Estimates
Baseline estimates are meticulously triangulated by combining customs trade registry data, primary executive interviews with industry stakeholders, and secondary macroeconomic indicators from global trade bodies.
Scope of the Report and Coverage Parameters
This report covers global manufacturing, distribution, and end-user adoption trends across commercial and residential sectors, excluding raw mineral extraction operations while focusing entirely on finished hardware components.
Recent Developments in the Industry
Recent strategic moves include cross-border acquisitions by Tyman PLC and new eco-coating product launches by Stanley Black & Decker Inc., underscoring a broader industry pivot toward sustainability and portfolio expansion.