What is the scope and industry significance of the Heavy Lift Jack-Up Vessel Market?
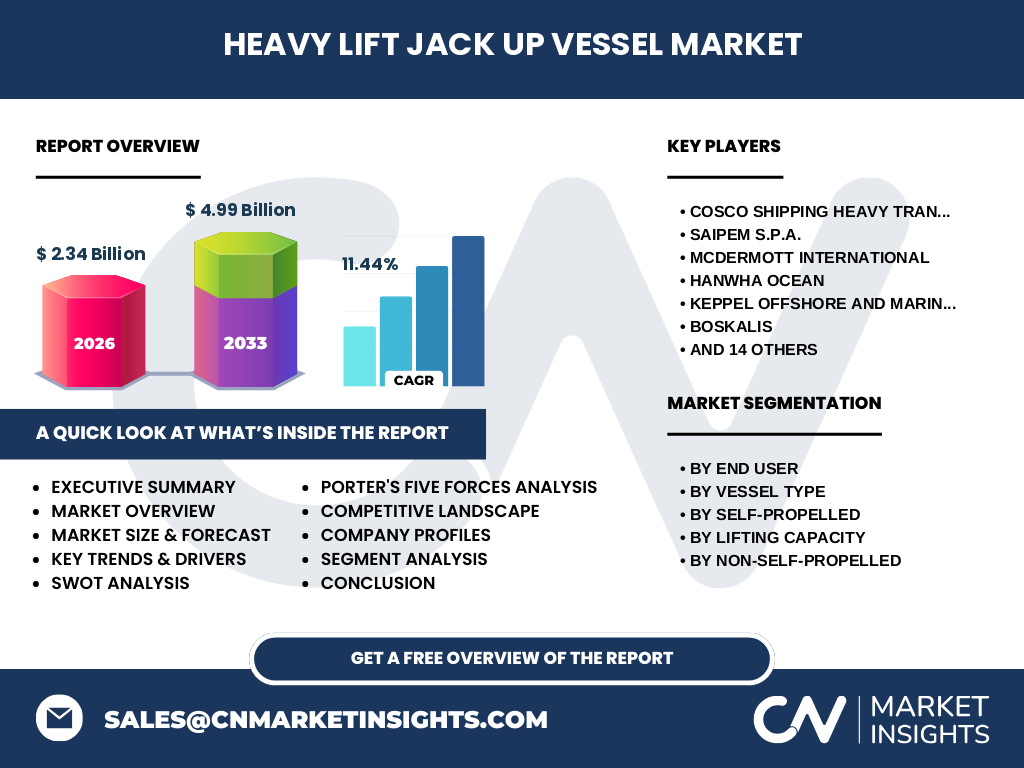
The Heavy Lift Jack-Up Vessel Market is valued at $2.34 Billion in 2026, serving as the critical backbone for offshore wind turbine installation and deepwater hydrocarbon extraction. These self-elevating platforms operate under stringent maritime classifications governed by the IMO and DGL, utilizing ultra-high-grade structural steel and specialized heavy-load hydraulic jacking systems to withstand severe metocean conditions.
Key market drivers, restraints, challenges, and opportunities shaping Heavy Lift Jack-Up Vessel Market
Market expansion is heavily driven by aggressive global net-zero targets and surging turbine capacities exceeding 15 megawatts. However, persistent supply chain bottlenecks for heavy forgings and high shipyard utilization rates act as primary restraints. Significant opportunities lie in retrofitting older tonnage with dynamic positioning capabilities and advanced green propulsion systems to meet tightening environmental regulations.
Emerging trends and growth patterns in Heavy Lift Jack-Up Vessel Market
Our analysis indicates a decisive shift toward ultra-large Above 5,000 Tons lifting capacity units capable of handling next-generation monopiles. Operators are increasingly integrating Hybrid Propulsion Powered systems to reduce carbon intensity during transit between major fabrication hubs like Rotterdam and offshore lease areas.
COVID-19 impact analysis and recovery trajectory for the sector
The pandemic severely disrupted shipyard schedules and crew changes, delaying major offshore wind engineering, procurement, and construction (EPC) timelines. The subsequent recovery trajectory has been robust, propelled by stimulus packages like the European Green Deal and renewed capital expenditure in global offshore energy infrastructure.
Competitive benchmarking and strategic dynamics
The competitive landscape features high market concentration among specialized marine contractors such as Cadeler, Heerema Marine Contractors, and DEME Group. Strategic positioning focuses on securing multi-year charter contracts with Tier-1 energy developers, requiring massive upfront capital expenditure for newbuild vessels equipped with heavy crane capacities.
Executive summary of the Heavy Lift Jack-Up Vessel Market
Our proprietary research demonstrates that the Heavy Lift Jack-Up Vessel Market is poised for explosive expansion, growing from $2.34 Billion in 2026 to $4.99 Billion by 2033 at a compound annual growth rate of 11.44%. This momentum is anchored by surging offshore wind deployment and complex marine construction demands.
Market forecast from 2027 to 2033
Projected growth will accelerate rapidly over the forecast period, pushing the total valuation from its 2026 baseline to reach $4.99 Billion by 2033. This trajectory reflects an impressive 11.44% CAGR, fueled by multi-billion-dollar federal lease auctions and the commercialization of deeper water sites requiring advanced Dynamic Positioning Capable assets.
Segmentation analysis across end-user and vessel categories
Segmentation breaks down into Renewable Energy, Oil And Gas, Marine Construction, and Other End Users. Vessel architectures are split between Self-Propelled units—further categorized by Diesel Electric Powered and Heavy Load Transport Capable configurations—and Non-Self-Propelled variants utilizing Barge Mounted Configuration and Tug Assisted Mobility for sheltered waters.
Geographic distribution and regional performance
Geographic performance is currently dominated by Northern Europe due to mature North Sea wind farms, followed by rapidly expanding project pipelines across the Asia-Pacific basin. North America is emerging as a high-growth region, stimulated by the Jones Act compliance requirements favoring specialized domestic or locally compliant vessel deployments.
In-depth regional review of key deployment zones
The North Sea and Baltic regions lead in utilization rates, driven by shallow water depths and favorable regulatory frameworks. Meanwhile, the Asia-Pacific market exhibits accelerated demand, where regional operators leverage local heavy fabrication yards in South Korea and China to commission customized units tailored to typhoon-prone metocean criteria.
Company profiles and strategic positioning of leading innovators
Industry leaders like COSCO Shipping Heavy Transport, Saipem S.p.A., and Huisman maintain competitive moats through proprietary crane designs and vertically integrated engineering. Meanwhile, fleet operators such as Van Oord, Jan De Nul Group, and Fred Olsen Windcarrier focus on specialized installation efficiencies to capture high-margin offshore wind contracts.
Porter's Five Forces analysis of competitive intensity
The threat of new entrants remains remarkably low due to prohibitive capital expenditure requirements exceeding hundreds of millions per vessel. Bargaining power of buyers is moderate to high, as major developers command leverage over charter rates, while the threat of substitution is mitigated by the unmatched heavy-lifting utility of jack-up assets.
SWOT analysis of the Heavy Lift Jack-Up Vessel Market industry
Key strengths include advanced technological capabilities and high barriers to entry, while weaknesses involve vulnerability to volatile steel raw material costs. Opportunities abound in emerging floating-to-fixed hybrid wind projects, though severe weather downtime and geopolitical supply chain disruptions remain critical persistent threats.
Value chain analysis from raw materials to end-users
The value chain initiates with raw alloy steel and specialized component manufacturers like Huisman providing heavy lifting gear. Midstream involves complex shipyard construction by firms like Hanwha Ocean and Keppel Offshore And Marine, culminating in downstream deployment by marine contractors for utility-scale energy developers.
Investment insights and high-potential areas
Strategic investment should target companies possessing Above 5,000 Tons lifting capacity vessels and advanced Hybrid Propulsion Powered fleets. These assets are best positioned to secure premium long-term charter agreements amidst tightening global environmental mandates and escalating turbine component weights.
Conclusion and key takeaways for stakeholders
The data confirms that navigating this $4.99 Billion market by 2033 requires proactive fleet modernization and strategic shipyard partnerships. Stakeholders must prioritize technological agility, particularly in dynamic positioning and ultra-heavy lift capabilities, to capitalize on the 11.44% CAGR growth window.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by combining proprietary global maritime trade registries, primary stakeholder interviews with C-suite executives at McDermott International and Boskalis, and secondary macroeconomic indicators from international energy agencies to ensure unmatched analytical accuracy.
Scope of the report, coverage parameters, and analytical limitations
This report covers global commercial deployments, newbuild order books, and charter rate dynamics across Renewable Energy and Oil And Gas sectors from 2027 through 2033. Limitations exclude unsanctioned state-backed projects lacking verifiable public registry data or transparent financial disclosures.
Recent developments, strategic partnerships, and product launches
Recent industry momentum highlights strategic joint ventures and vessel acquisitions by players like Cadeler and Seaway7 to expand operational reach. Major shipyards are actively launching next-generation designs featuring upgraded deck space configurations to accommodate massive 15MW-plus turbine components efficiently.