Market overview and industry significance of the Nickel Market
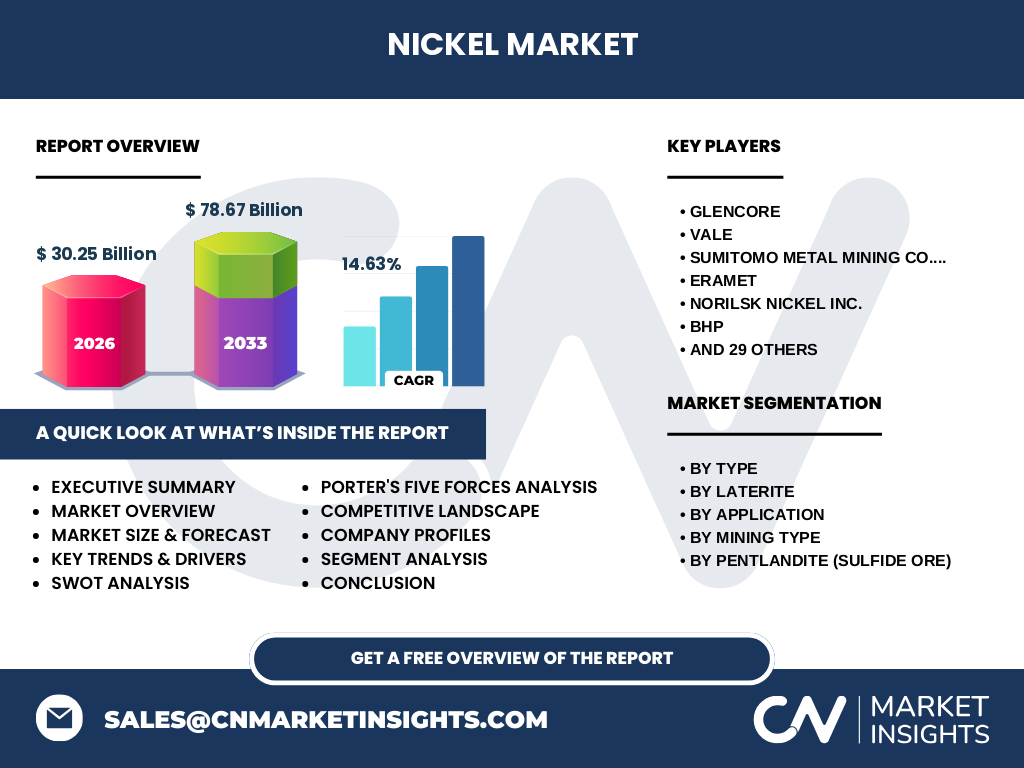
Our analysis indicates that the Nickel Market market size is valued at $30.25 Billion in 2026, driven by essential applications in stainless steel production and advanced energy storage systems. This sector underpins global heavy manufacturing and clean energy transitions, relying heavily on refined products from major miners like Vale and Glencore to feed stringent supply chains across Asia-Pacific and European industrial hubs.
Structural Growth Drivers and Market Restraints
The primary growth catalyst is surging electric vehicle adoption, which heavily accelerates demand for high-purity battery chemicals. Conversely, strict environmental regulations from bodies like the European Union pose significant compliance hurdles for high-emission pyrometallurgical processing. Producers must navigate complex ESG mandates while managing volatile input costs for sulfur and energy.
Emerging Trends in the Nickel Market
The industry is witnessing an aggressive pivot toward High-Pressure Acid Leaching (HPAL) technology to convert low-grade laterite ores into battery-grade intermediates. Innovators like Tsingshan Holdings Group are pioneering novel rotary kiln-electric furnace methods, fundamentally altering cost curves and redefining global supply chain dynamics for nickel matte.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-induced labor shortages and port congestions temporarily disrupted laterite shipments from key Indonesian extraction sites. Based on our research, the sector demonstrated robust resilience, rebounding sharply as governmental stimulus packages revived automotive manufacturing and infrastructure spending globally, solidifying a stable post-pandemic recovery path.
Competitive Landscape and Strategic Dynamics
Market concentration remains moderately fragmented among major state-backed entities and multinational mining conglomerates. Industry leaders such as Norilsk Nickel Inc. and BHP leverage massive asset portfolios and proprietary refining technologies to secure dominant supply agreements, while junior explorers focus on high-grade sulfide deposits in stable jurisdictions.
Executive Summary of the Nickel Market Report
This comprehensive evaluation highlights a projected market expansion to $78.67 Billion by 2033, expanding at a robust CAGR of 14.63% from 2027. Strategic imperatives center on securing green-certified supply sources, optimizing HPAL extraction efficiencies, and mitigating geopolitical risks associated with primary laterite processing regions.
Market Forecast from 2027 to 2033
The data suggests unprecedented acceleration, projecting the market to surge from its 2026 baseline to $78.67 Billion by the end of 2033. This trajectory is underpinned by an impressive CAGR of 14.63%, fueled by relentless demand from lithium-ion battery gigafactories and aerospace alloy manufacturers requiring ultra-pure metal grades.
Segmentation Analysis of the Nickel Market
The industry is segmented by type into Pentlandite (Sulfide Ore) and Laterite, with Laterite further divided into ferronickel, nickel matte, and nickel sulfate. Application segments cover stainless steel, batteries, aerospace and automotive, electronics, and electrical. Mining types encompass underground and surface extraction, while Pentlandite breaks down into concentrates and intermediate products.
Regional Market Analysis and Geographic Distribution
Asia-Pacific dominates consumption and processing, anchored by massive stainless steel mills and battery cell producers in China, Indonesia, and South Korea. Meanwhile, North America and Europe prioritize ESG-compliant supply chains, driving local investments in domestic sulfide deposits managed by firms like Talon Metals and Lundin Mining Corporation.
In-Depth Regional Review
Indonesia continues to dictate global price trends through rapid expansion of domestic laterite processing capacity. Concurrently, North American markets focus on ethical sourcing under the Inflation Reduction Act, creating distinct regional pricing premiums for low-carbon sulfide concentrates produced by miners like FPX Nickel and North American Nickel.
Company Profiles and Strategic Positioning
Major industry participants maintain competitive edges through vertical integration and technological innovation. Vale and Glencore dominate global sulfide supply, whereas Sumitomo Metal Mining Co. Ltd leads in advanced HPAL deployment. Meanwhile, specialized operators like Sherritt International Corporation and Eramet focus on regional laterite refinement and sustainable processing partnerships.
Porter's Five Forces Analysis
Bargaining power of suppliers is moderate due to capital-intensive mine development requirements. Threat of substitutes remains low in heavy aerospace alloys, though substitution risks exist in specific battery chemistries. Competitive rivalry is intense, pressuring operators to optimize ore recovery rates and lower carbon footprints.
SWOT Analysis of the Industry
Key strengths include robust demand fundamentals and established refining networks. Weaknesses involve high capital expenditure and carbon-intensive processing. Opportunities lie in electric vehicle battery expansion and recycling innovations. Threats encompass stringent environmental regulations, geopolitical trade disputes, and unexpected ore grade declines.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with surface and underground extraction of pentlandite and laterite ores, followed by beneficiation into concentrates, ferronickel, or intermediate matte products. Smelters and refineries then convert these intermediates into high-purity nickel sulfate or metal cathodes, which end-users fabricate into stainless steel and battery components.
Investment Insights and High-Potential Areas
Our analysis indicates that high-potential investment opportunities lie in low-carbon HPAL facilities and domestic North American sulfide exploration projects. Strategic capital deployment toward battery recycling infrastructure and proprietary green refining technologies will yield superior risk-adjusted returns over the forecast period.
Conclusion and Key Takeaways
The nickel sector stands at a critical inflection point, transitioning from traditional stainless steel applications to high-growth energy storage markets. Achieving the projected $78.67 Billion valuation requires proactive management of ESG regulations, technological upgrades in laterite processing, and strategic supply chain partnerships across global mining hubs.
Research Methodology
Baseline estimates are meticulously triangulated by combining proprietary trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators from international mining bureaus. This multi-layered approach ensures high fidelity in market sizing and growth forecasting.
Scope of the Report
This report covers global production, consumption, trade flows, and pricing dynamics across all major mine and refined product categories from 2026 through 2033. Limitations include inherent uncertainties regarding future geopolitical trade tariffs, sudden environmental policy shifts, and unforeseen disruptions in primary extraction regions.
Recent Developments in the Sector
Recent industry momentum features major joint ventures aimed at expanding HPAL capacity in Southeast Asia, alongside strategic equity investments by automotive OEMs into junior sulfide developers. Companies are increasingly forging long-term offtake agreements to secure green-certified metal supply for upcoming electric vehicle manufacturing lines.