What is the scope and industry significance of the Nickel-Based Superalloys Market?
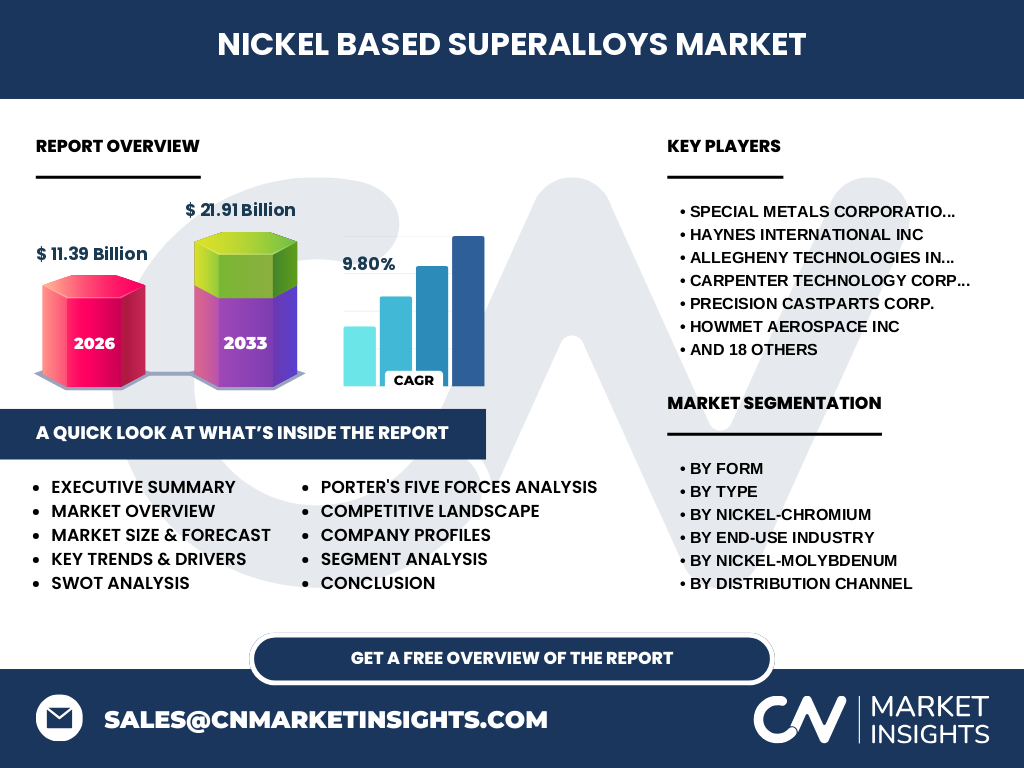
The Nickel-Based Superalloys Market represents a critical cornerstone of advanced materials engineering, projected to reach $11.39 Billion in 2026. Our analysis indicates these high-performance alloys provide exceptional strength, creep resistance, and surface stability at extreme temperatures, making them indispensable for aerospace turbine blades and severe industrial processing environments.
Structural Growth Drivers and Market Restraints
Growth is propelled by expanding commercial aviation fleets and stringent FAA and EASA emissions standards requiring higher turbine operating efficiencies. However, the market faces severe constraints from the extreme price volatility of raw materials like cobalt and nickel, alongside strict trade compliance enforced by regulatory bodies governing strategic metals.
Emerging Trends in the Nickel-Based Superalloys Market Industry Trends
A defining shift is the rapid adoption of additive manufacturing and powder metallurgy for complex geometries, spearheaded by innovators like Rosswag GmbH. Single-crystal casting technologies are also gaining prominence to eliminate grain-boundary weaknesses, allowing components to withstand unprecedented thermal fatigue in next-generation aerospace engines.
How did the COVID-19 pandemic impact the Nickel-Based Superalloys Market market size and recovery?
The pandemic triggered a sharp contraction in commercial aerospace orders, temporarily disrupting supply chains for major players like Precision Castparts Corp. and Howmet Aerospace Inc. Recovery has been driven by a V-shaped rebound in defense spending and post-pandemic air travel normalization, pushing demand back toward robust multi-year growth trajectories.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high market concentration among specialized metallurgical giants such as Special Metals Corporation, Haynes International Inc, and Allegheny Technologies Incorporated. These firms leverage proprietary alloy formulations and integrated supply chains to secure long-term OEM contracts in aerospace and defense sectors.
Executive Summary of Nickel-Based Superalloys Market Analysis
Valued at $11.39 Billion in 2026, the market is poised for accelerated expansion, driven by relentless demand for thermal-resistant materials. Strategic consolidation, technological advancements in single-crystal structures, and critical applications in extreme operating environments underpin the sector's long-term commercial viability and investment appeal.
Market Forecast and Growth Projections Through 2033
Our research forecasts the market to expand from $11.39 Billion in 2026 to $21.91 Billion by 2033, registering a robust CAGR of 9.80%. This upward trajectory is underpinned by surging global air traffic, deep-water oil and gas exploration, and expanding industrial power generation turbine installations.
Segmentation Analysis of the Nickel-Based Superalloys Market
Segmentation is categorized by Form (Cast, Wrought), Type (Nickel–Chromium–Cobalt–Based Superalloys, Nickel-Chromium, Nickel-Molybdenum), and End-Use Industry (Aerospace, Industrial, Oil And Gas). Further sub-segmentation includes Inconel Alloys, Hastelloy Alloys, and specialized Solid-Solution Strengthened or Precipitation-Hardened formulations tailored for specific thermal thresholds.
Geographic Distribution and Regional Market Performance
Regional performance reflects aerospace manufacturing hubs and heavy industrial density, with North America leading consumption due to dominant primes like Pratt & Whitney and GE Aviation. Europe follows closely, anchored by stringent environmental regulations and robust industrial processing sectors, while Asia-Pacific emerges as the fastest-growing manufacturing zone.
In-Depth Regional Review of Manufacturing and Consumption Hubs
North America benefits from established supply networks involving Carpenter Technology Corporation and Haynes International Inc. Meanwhile, Asia-Pacific growth is fueled by expanding domestic aviation programs in China and localized special steel production by entities like Baosteel Group Corporation and Fushun Special Steel Co., Ltd.
Company Profiles and Strategic Positioning
Industry leaders like Sandvik Materials Technology, Aperam S.A., and Mishra Dhatu Nigam Limited maintain distinct competitive edges through localized distribution networks and proprietary melting technologies like vacuum induction melting. Companies continuously invest in R&D to optimize alloy creep resistance and oxidation performance for severe service environments.
Porter's Five Forces Analysis of Competitive Pressures
The threat of new entrants is remarkably low due to massive capital expenditure requirements for vacuum furnaces and strict aerospace qualification hurdles. Supplier power remains moderate to high given the scarcity of raw nickel and cobalt, while buyer power is concentrated among a handful of dominant aerospace OEMs.
SWOT Analysis of the Nickel-Based Superalloys Market
Strengths include unmatched high-temperature mechanical properties and irreplaceable utility in turbine applications. Weaknesses involve high production costs and raw material dependencies. Opportunities lie in additive manufacturing powders, whereas threats stem from ceramic matrix composite alternatives and geopolitical trade restrictions on critical minerals.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with mining raw elements like nickel, chromium, and cobalt, progressing through primary melting, powder atomization, and precision casting or forging. Downstream service centers, including Thyssenkrupp Aerospace and authorized distributors, ensure seamless delivery of certified bar, sheet, and forged components to end-use manufacturers.
Investment Insights and High-Potential Areas
High-potential investment zones center around closed-loop recycling infrastructure for scrap superalloys and the development of proprietary powder alloys for 3D printing. Investors should target vertically integrated producers capable of insulating margins against raw material commodity price fluctuations.
Conclusion and Key Takeaways for Industry Stakeholders
The Nickel-Based Superalloys Market offers compelling growth underpinned by aerospace recovery and stringent thermal performance demands. Stakeholders must prioritize technological differentiation in single-crystal casting and sustainable scrap recycling to capture high-margin opportunities through 2033.
Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by cross-referencing global trade registry data, primary qualitative interviews with C-suite executives across key players like VSMPO-AVISMA Corporation and Eramet S.A., and secondary macroeconomic indicators regarding aerospace build rates and industrial capital expenditure.
Scope of the Report and Coverage Parameters
This report encompasses global market sizing, volume shipments, and revenue projections from 2027 to 2033 across specified form, type, end-use, and distribution channel segments. Limitations include proprietary confidentiality agreements regarding specific tier-1 aerospace pricing contracts and localized spot-market variances.
Recent Developments and Strategic Industry Moves
Recent market activity highlights aggressive capacity expansions and strategic partnerships aimed at securing sustainable raw material supply chains. Key participants such as AMG Advanced Metallurgical Group and Walsin Lihwa Corporation have ramped up investments in specialized recycling and alloy refinement facilities to meet surging green-energy and aerospace specifications.