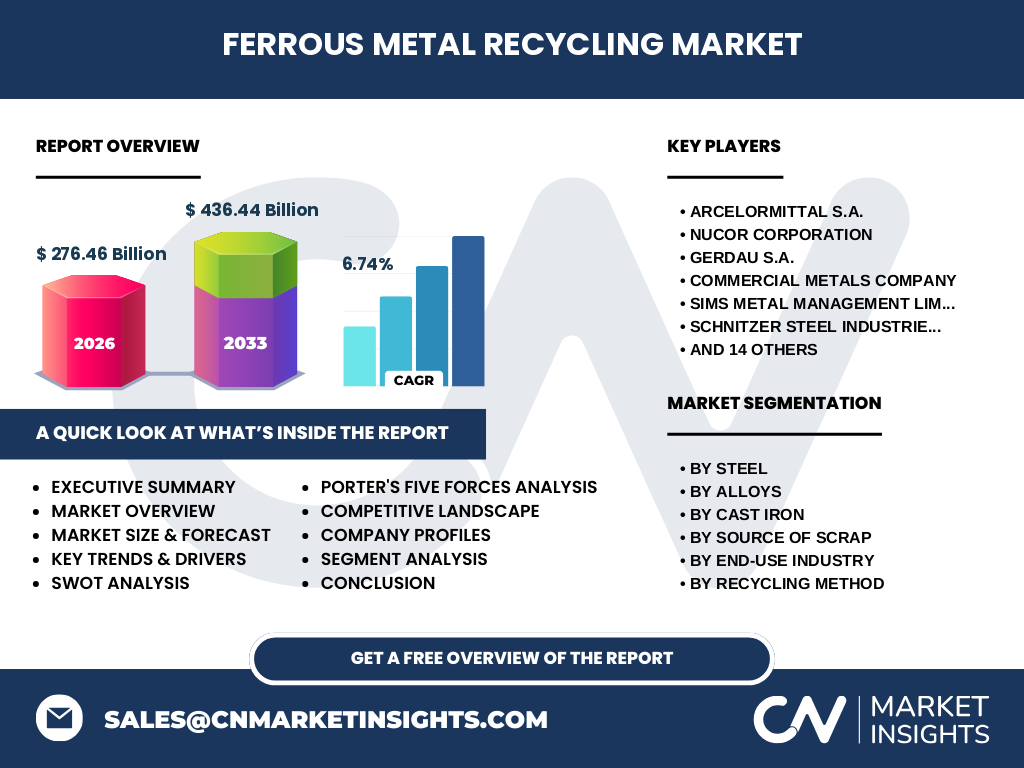
Market overview of the Ferrous Metal Recycling Market
Our analysis indicates that the Ferrous Metal Recycling Market is valued at $276.46 Billion in 2026, serving as a critical backbone for global decarbonization. This sector encompasses the processing, shredding, and repurposing of scrap iron and steel derived from industrial, automotive, and demolition streams to feed Electric Arc Furnaces (EAFs).
Structural Growth Drivers and Market Constraints
The market is propelled by stringent EU and EPA emissions mandates that force steelmakers to reduce carbon intensity by utilizing recycled scrap. However, logistical hurdles such as rising freight costs for heavy bulk commodities and stringent contamination thresholds for post-consumer scrap continue to constrain rapid operational scaling.
Emerging Trends and Technological Shifts
The sector is experiencing a massive pivot toward advanced sorting technologies, including X-ray fluorescence (XRF) and laser-induced breakdown spectroscopy (LIBS). These innovations allow operators like Sims Metal Management and Schnitzer Steel Industries Inc. to precisely separate alloy elements like chromium and nickel from complex scrap streams.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted the collection infrastructure for post-consumer and construction scrap due to widespread lockdowns and automotive plant shutdowns. The subsequent recovery trajectory has been robust, accelerated by government-backed infrastructure stimulus packages that rapidly spiked global demand for recycled carbon steel.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately fragmented among regional giants, with major players securing captive scrap supply through direct vertical integration. Companies like Nucor Corporation and ArcelorMittal S.A. acquire dedicated recycling yards to guarantee raw material feedstock for their low-emission EAF mills.
Executive Summary of the Ferrous Metal Recycling Industry
This comprehensive report highlights a transformative growth phase for the industry, driven by circular economy mandates and steel decarbonization. Key takeaways emphasize that securing prime scrap supply chains and investing in automated sorting will separate market leaders from regional operators through 2033.
Market Forecast and Long-Term Projections
Based on our econometric modeling, the Ferrous Metal Recycling Market is projected to expand from $276.46 Billion in 2026 to reach $436.44 Billion by 2033, expanding at a robust compound annual growth rate (CAGR) of 6.74% over the forecast period.
Comprehensive Segmentation Analysis
Our research segments the market by steel types (carbon steel, stainless steel, alloy steel), alloys (ferroalloys, specialty alloys), cast iron (grey, ductile, white), source (industrial, post-consumer, construction), end-use (automotive, construction, manufacturing, shipbuilding), and recycling methods (physical, chemical, pyrometallurgical), revealing distinct demand pockets across industrial verticals.
Regional Market Performance and Geographic Distribution
Geographic performance is heavily anchored by industrialized economies with stringent environmental policies. North America and Europe dominate consumption due to established EAF steelmaking capacity, while Asia-Pacific exhibits the fastest growth velocity driven by rapid industrialization and massive urban demolition projects.
In-Depth Regional Review: North America and Europe
In North America, regulatory push from the EPA and local zoning laws dictate yard operations, favoring well-capitalized firms like Commercial Metals Company and Alter Trading Corporation. Meanwhile, European markets enforce rigorous end-of-life vehicle directives, pushing recyclers like TSR Recycling GmbH And Co. KG into hyper-efficient closed-loop processing.
Company Profiles and Competitive Positioning
Leading industry participants leverage distinct operational footprints to capture market share. Key players include Gerdau S.A., Real Alloy Holding LLC, PSC Metals LLC, American Iron And Metal Co (AIM), SA Recycling LLC, Metalico Inc., OmniSource LLC, David J. Joseph Co. (DJJ), Kuusakoski Oy, Upstate Shredding LLC, Sadoff Iron & Metal Company, Ferrous Processing And Trading Co. (FPT), and AMG Resources Corporation, each optimizing regional shredding and logistics.
Porter's Five Forces Analysis of the Industry
Bargaining power of suppliers is moderate, constrained by fragmented scrap collection networks. Threat of substitution remains low because recycled ferrous scrap is chemically indispensable for secondary steelmaking, whereas competitive rivalry is intense among mega-recyclers vying for exclusive industrial scrap generation contracts.
SWOT Analysis of Ferrous Metal Recycling
Key strengths lie in established processing infrastructure and circular economy alignment. Major weaknesses involve vulnerability to volatile global iron ore and scrap pricing. Opportunities abound in green steel feedstock agreements, while threats stem from tightening trade restrictions on metal scrap exports.
Value Chain Analysis from Scrap Generation to End-Users
The value flow begins with scrap generation across demolition sites and automotive shredders, moving through physical processing like shearing and magnetic separation. It culminates in delivery to electric arc furnaces where steel mills melt the material into high-grade construction beams and automotive sheet metal.
Investment Insights and High-Potential Areas
Strategic investors should prioritize capital allocation toward automated AI-driven optical sorting facilities and regional scrap consolidation yards. These high-potential areas offer superior margin expansion as steel mills increasingly pay premiums for certified low-residual ferrous scrap.
Conclusion and Strategic Takeaways
The Ferrous Metal Recycling Market industry trends underscore a permanent transition toward sustainable manufacturing. Stakeholders must embrace advanced processing technologies and secure long-term industrial collection agreements to thrive in a carbon-constrained global economy through 2033.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-suite executives, secondary trade registry data from international metal bureaus, and macroeconomic indicators tracking global steel production outputs and scrap trade flows.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for ferrous metal recycling from 2027 through 2033, analyzing specific material streams, regional nuances, and competitive landscapes. Limitations include potential volatility in macroeconomic exchange rates and unforeseen geopolitical trade policy shifts.
Recent Developments, Partnerships, and Strategic Moves
Recent market activities feature aggressive M&A maneuvers, long-term green steel supply partnerships between major recyclers and integrated steelmakers, and facility upgrades incorporating low-emission material handlers to comply with emerging carbon-neutral operational mandates.