What is the market overview and industry significance of the Liquefied Natural Gas (LNG) Tank Insulation System Market?
Our analysis indicates that the Liquefied Natural Gas (LNG) Tank Insulation System Market represents a critical engineering segment, valued at 3.42 Billion in 2026. This sector ensures thermal protection for cryogenic containment structures, operating at extreme temperatures of -162°C. Based on our research, advanced insulation is vital for mitigating boil-off gas (BOG) rates during maritime transport and onshore storage across major import terminals.
Structural Growth Drivers and Market Restraints
The market is propelled by surging global demand for clean energy and stringent International Maritime Organization (IMO) emissions targets. However, our research highlights significant restraints, including the high capital expenditure required for cryogenic materials and complex supply chain bottlenecks for specialized polymers like polyurethane. Industry trends show that players must balance thermal efficiency with strict safety compliance governed by bodies like SIGTTO.
Emerging Trends in the Liquefied Natural Gas (LNG) Tank Insulation System Market
Industry trends reveal a distinct pivot toward ultra-low thermal conductivity solutions, particularly aerogel-based insulation and vacuum-insulated panels. Companies such as Aspen Aerogels Inc. and Armacell International S.A. are leading the charge by developing advanced composite barriers that drastically reduce boil-off losses. This technological evolution favors firms heavily invested in proprietary chemical formulations capable of withstanding severe sloshing forces in offshore applications.
How did the COVID-19 pandemic impact the Liquefied Natural Gas (LNG) Tank Insulation System Market?
The pandemic caused severe supply chain disruptions and delayed engineering procurement construction (EPC) timelines for mega-scale liquefaction plants. Nevertheless, our data suggests a robust recovery trajectory driven by post-pandemic energy security initiatives. Demand rebounded swiftly as European utilities accelerated floating storage regasification unit (FSRU) deployments, boosting orders for specialized spray and panel insulation systems.
Competitive Benchmarking and Market Concentration
The competitive landscape is characterized by a consolidated group of multinational conglomerates and specialized cryogenic pioneers. Market leaders like Gaztransport & Technigaz S.A. dominate membrane containment designs, while insulation specialists such as Kingspan Group plc and Owens Corning secure niche dominance in rigid foam and glass wool applications. Strategic partnerships between shipyards and material providers remain the primary mechanism for maintaining technological moats.
Executive Summary of the Liquefied Natural Gas (LNG) Tank Insulation System Market
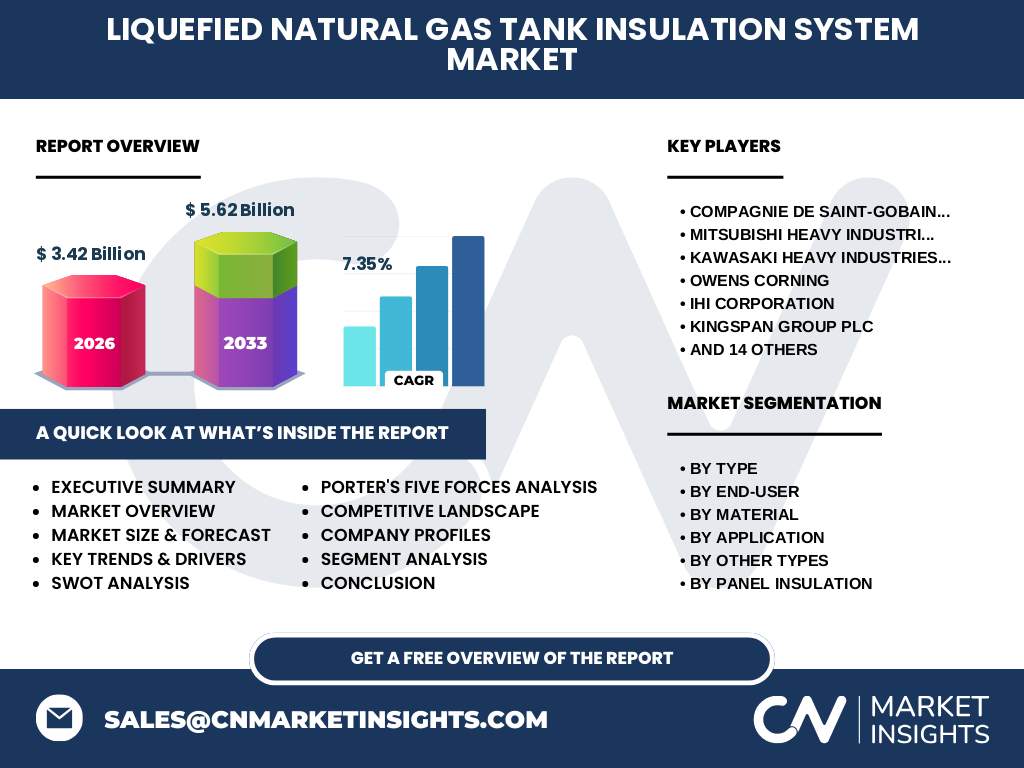
Our comprehensive report synthesis projects the Liquefied Natural Gas (LNG) Tank Insulation System Market to expand from 3.42 Billion in 2026 to 5.62 Billion by 2033, exhibiting a steady CAGR of 7.35%. This expansion is underpinned by aggressive global infrastructure buildouts in Asia-Pacific and North America, necessitating advanced cryogenic containment solutions across onshore terminals and transport vessels.
Long-Term Market Forecast from 2027 to 2033
The data suggests accelerating momentum over the forecast period, scaling the market valuation from 3.42 Billion in 2026 toward the 5.62 Billion threshold by 2033 at a 7.35% CAGR. This growth trajectory reflects sustained investments in midstream export terminals and the continuous expansion of global LNG carrier fleets navigating stringent environmental regulations.
Segmentation Analysis of Insulation Types and End-Users
Segmentation analysis breaks down the market by Type (Spray Insulation, Panel Insulation, Blanket Insulation, Other Types), End-User (Oil And Gas, Marine, Industrial, Other End-User), Material (Polyurethane, Polyisocyanurate, Glass Wool, Perlite, Other Materials), and Application (Onshore Tanks, Offshore Tanks, Transport Tanks). Panel Insulation and Polyurethane materials command dominant market shares due to their superior structural integrity and ultra-low cryogenic permeability.
Geographic Distribution and Regional Market Analysis
Geographically, the market performance diverges based on regional energy transition policies and liquefaction capacity additions. Asia-Pacific leads consumption due to massive import infrastructure projects in China, Japan, and South Korea. Meanwhile, North America maintains robust output driven by Gulf Coast export terminal expansions, while Europe prioritizes FSRU retrofits to secure independent regasification capabilities.
In-Depth Regional Review of Key Markets
A granular review of regional performance reveals that Asia-Pacific acts as the primary demand epicenter, fueled by long-term gas supply contracts and massive regasification terminal construction. North America follows closely, leveraging shale gas abundance to drive onshore storage tank construction. European markets, steered by stringent EU methane emissions standards, focus heavily on upgrading existing containment infrastructure to minimize boil-off losses.
Strategic Positioning in Company Profiles
Leading industry participants leverage distinct strategic advantages to capture market share. Firms like Mitsubishi Heavy Industries Ltd. and IHI Corporation integrate insulation systems directly into heavy marine vessel manufacturing. Meanwhile, specialized chemical producers like Hankuk Carbon Co. Ltd. and Röchling SE & Co. KG supply proprietary composite cryogenic panels tailored for membrane containment LNG carriers.
Porter's Five Forces Analysis of Competitive Pressures
Our analysis indicates that supplier power is moderately high due to the proprietary chemical formulations required for cryogenic insulation. Buyer power remains constrained by the critical safety requirements of handling liquefied gas at -162°C. Threat of substitutes is low, as few materials match the thermal performance of specialized polyurethane, perlite, and aerogel systems in extreme marine environments.
SWOT Analysis of the Liquefied Natural Gas (LNG) Tank Insulation System Market
Key strengths lie in advanced thermal efficiency and proven membrane compatibility. Weaknesses include high capital intensity and susceptibility to raw material price volatility. Opportunities abound in the transition toward bio-LNG and floating offshore production units. Threats stem from geopolitical disruptions impacting global supply chains and regulatory shifts favoring alternate green energy vectors.
Value Chain Analysis from Raw Materials to End-Users
The industry value chain flows from petrochemical feedstock suppliers providing isocyanates and polyols, through specialized insulation manufacturers like Armacell International S.A. and ROCKWOOL International A/S, to system integrators and shipyards. Downstream deployment involves major energy operators utilizing these systems in onshore storage hubs and transport carriers managed by firms such as Chart Industries Inc. and INOX India Limited (INOXCVA).
Strategic Investment Insights and High-Potential Areas
High-potential investment pockets center on advanced aerogel-based insulation and vacuum-insulated panels designed for next-generation membrane LNG carriers. Stakeholders should prioritize partnerships with Asian shipyards and investments in eco-friendly blowing agents that comply with emerging environmental mandates. Companies possessing integrated manufacturing capabilities are best positioned to capture superior operating margins.
Conclusion and Key Takeaways for Industry Stakeholders
The Liquefied Natural Gas (LNG) Tank Insulation System Market offers compelling growth prospects, projected to reach 5.62 Billion by 2033. Success in this sector requires continuous R&D investment aimed at reducing boil-off gas rates, complying with rigorous maritime safety codes, and forging strategic alliances across the EPC and shipbuilding value chain.
Research Methodology and Baseline Triangulation
Baseline estimates are triangulated using a rigorous mixed-methods approach. We combine maritime trade registry data, customs import-export statistics for cryogenic polymers, and primary stakeholder interviews with C-level executives from key participants like Kawasaki Heavy Industries Ltd. and NICHIAS Corporation. Secondary macroeconomic indicators from energy agencies further validate our market sizing models.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for the Liquefied Natural Gas (LNG) Tank Insulation System Market industry trends across 2026 through 2033. Coverage parameters encompass all major insulation types, materials, and end-user verticals. Limitations include the exclusion of small-scale domestic liquefied petroleum gas (LPG) storage not meeting cryogenic LNG temperature thresholds.
Recent Developments and Strategic Industry Moves
Recent industry developments feature aggressive R&D investments in lightweight composite cryogenic panels and strategic joint ventures between European insulation providers and Asian shipbuilders. Recent product launches by innovators like CIMC Enric Holdings Limited and Cryogas Equipment Private Limited emphasize ultra-low boil-off rates, reflecting the market's relentless pursuit of thermal optimization.