What is the market size and scope of the Allied Healthcare Staffing Market?
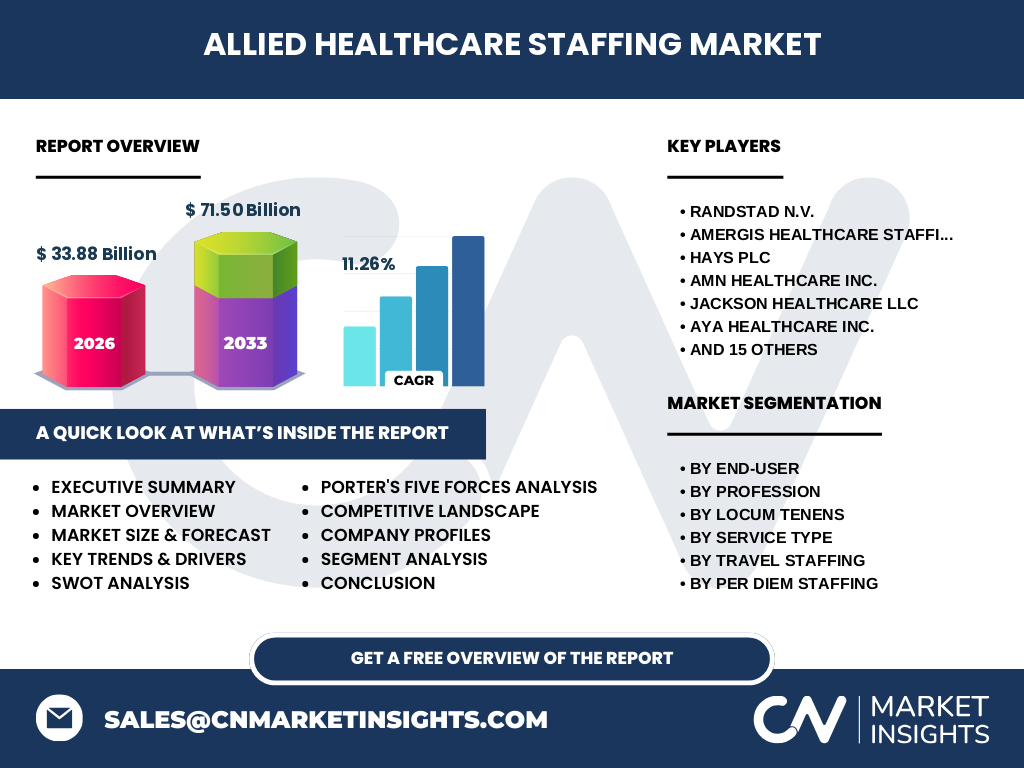
Our analysis indicates that the Allied Healthcare Staffing Market is valued at 33.88 Billion in 2026, driven by rising clinical demands across hospitals, clinics, and long-term care facilities. This sector encompasses specialized workforce deployment, including therapists, technologists, and pharmacists, navigating complex state-level credentialing and regulatory frameworks.
Structural Growth Drivers and Market Restraints
The market is propelled by an aging demographic and chronic staffing shortages, while being constrained by strict licensing compliance enforced by bodies like The Joint Commission. Budgetary pressures within ambulatory surgical centers create operational bottlenecks, though opportunities in telehealth support integration offer strong mitigation paths.
Emerging Trends in the Allied Healthcare Staffing Market
Travel staffing and digital-first vendor management systems are reshaping workforce agility. Facilities increasingly rely on short-term and long-term travel assignments to manage fluctuating census levels, benefiting tech-enabled agencies that streamline onboarding and credential verification for radiologic technologists and physical therapists.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted the Allied Healthcare Staffing Market, causing unprecedented wage inflation and acute burnout among medical assistants and per diem workers. Post-pandemic recovery centers on sustainable contract stabilization, shifting away from emergency surge pricing toward structured, long-term workforce planning models.
Competitive Benchmarking and Strategic Dynamics
Market concentration features key innovators like AMN Healthcare Inc., Aya Healthcare Inc., and Cross Country Healthcare Inc. These leaders leverage robust digital platforms and extensive candidate networks to dominate travel staffing and locum tenens segments, squeezing smaller independent regional agencies.
Executive Summary of Industry Findings
Our research projects the Allied Healthcare Staffing Market to surge from 33.88 Billion in 2026 to 71.50 Billion by 2033 at a CAGR of 11.26%. Accelerated demand for allied health professionals in specialized care underscores the critical need for agile recruitment strategies.
Market Forecast Projections (2027 to 2033)
Expanding at a robust 11.26% CAGR, the market valuation is slated to climb from 2027 through 71.50 Billion by 2033. This growth trajectory reflects persistent clinician shortages and expanding healthcare infrastructure demands across North America and key international corridors.
Comprehensive Segmentation Analysis
Segmentation spans end-users (Hospitals, Clinics, Ambulatory Surgical Centers, Long-Term Care), professions (Therapists, Technologists, Medical Assistants, Pharmacists), service types (Travel, Per Diem, Permanent Placement, Locum Tenens), and locum tenens tiers. Hospitals and travel staffing represent the highest revenue-generating nodes within this taxonomy.
Regional Market Analysis and Geographic Distribution
Geographic performance is heavily concentrated in North America due to mature healthcare reimbursement systems and high patient acuity. Regional variations in nurse practice acts and allied health licensing compacts dictate how swiftly agencies can deploy travel staffing solutions across state lines.
In-Depth Regional Review
Urban clusters in North America exhibit the highest density of specialized ambulatory surgical centers and hospital networks, driving intensive demand for per diem and permanent placement solutions. Regulatory hurdles in specific states require agencies to maintain localized compliance teams to avoid operational friction.
Company Profiles and Market Positioning
Industry stalwarts such as Randstad N.V., Hays plc, and Jackson Healthcare LLC employ diversified portfolio strategies. By balancing high-margin physician and advanced practice locum tenens with high-volume allied health travel placements, these firms secure resilient revenue streams against macroeconomic volatility.
Porter's Five Forces Assessment
Buyer power remains moderate-to-high as large hospital networks negotiate vendor-neutral fee structures. Meanwhile, threat of new entrants is mitigated by steep regulatory compliance costs and proprietary technology investments required to manage credentialing at scale for specialized technologists and pharmacists.
SWOT Analysis of the Industry
Key strengths include proprietary talent databases and established hospital partnerships, offset by weaknesses such as high candidate acquisition costs. Opportunities in international travel staffing balance threats from legislative wage caps and tightening federal labor regulations.
Value Chain Analysis in Allied Healthcare Staffing
The value chain flows from sourcing clinical talent through digital sourcing engines, verifying credentials against state board registries, deploying professionals via travel or per diem models, and managing billing integration with hospital enterprise resource planning systems.
Strategic Investment Insights
High-potential areas include technology platforms automating compliance verification and specialized recruitment for underserved allied professions like diagnostic medical sonographers. Investors should prioritize agencies with scalable digital infrastructure and multi-state licensing capabilities.
Conclusion and Key Takeaways
The Allied Healthcare Staffing Market represents a high-growth sector set to reach 71.50 Billion by 2033. Success hinges on technological innovation, rigorous compliance management, and strategic workforce diversification across travel and per diem service lines.
Research Methodology
Baseline estimates are triangulated by combining federal labor statistics, state health registry data, primary executive interviews with staffing agency leaders, and secondary macroeconomic indicators to ensure rigorous, evidence-based market sizing.
Scope of the Report and Limitations
This report covers global trends with a primary focus on North American and European allied health staffing dynamics. Limitations include potential lag in state-level licensing data updates and rapid regulatory shifts governing cross-border healthcare delivery.
Recent Industry Developments
Recent strategic moves feature major mergers, digital platform rollouts by firms like Medical Solutions LLC and Aya Healthcare Inc., and new vendor-neutral contracts designed to streamline contingent labor management for overburdened hospital health systems.