What is the scope and market significance of the Aluminum Rolled Products Market?
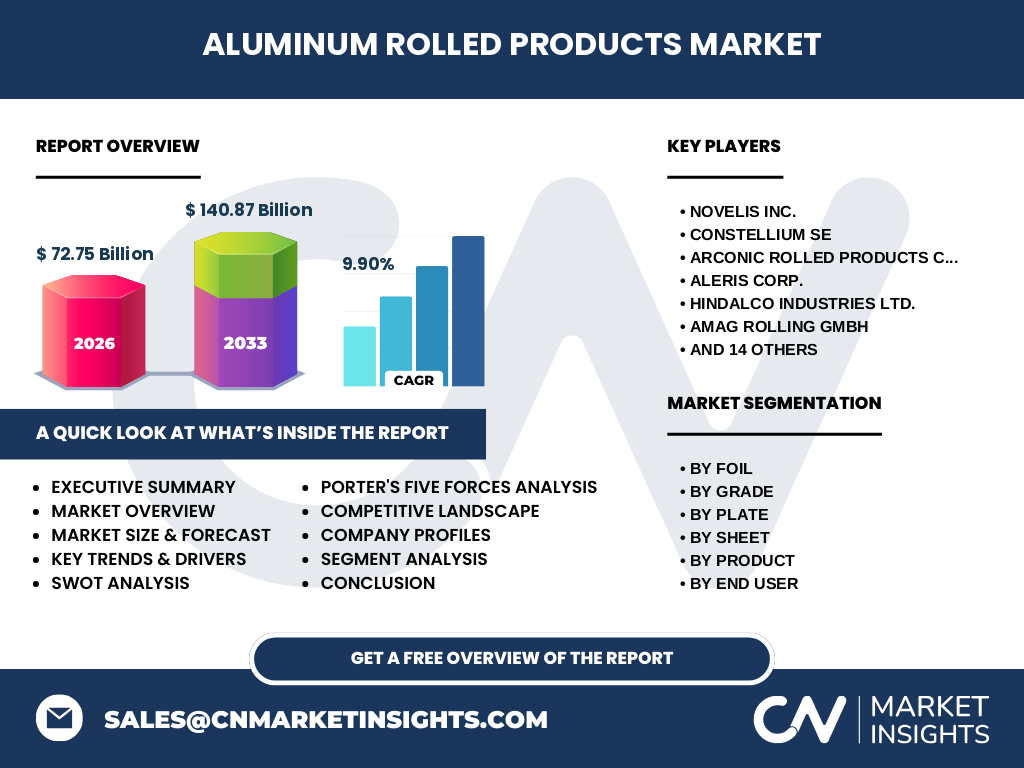
The Aluminum Rolled Products Market encompasses the production and distribution of high-performance sheets, plates, and foils used across heavy industries. Our analysis indicates this sector is valued at $72.75 Billion in 2026, serving as a critical backbone for lightweight engineering and sustainable material transitions globally.
Structural Growth Drivers and Market Restraints
Growth is propelled by surging demand for lightweight automotive architecture and eco-friendly packaging, offset by stringent energy regulations and fluctuating primary aluminum smelting costs. Supply chain bottlenecks and regional energy tariffs in Europe continue to constrain high-margin processing output for key producers.
The Shift Toward Advanced Sustainability and Alloy Innovation
Industry trends reveal a decisive pivot toward closed-loop recycling and specialized 5xxx and 6xxx series alloys. Manufacturers are increasingly utilizing scrap-based inputs to lower carbon footprints while meeting demanding automotive crash-worthiness standards set by regulatory bodies.
How did the COVID-19 pandemic impact the Aluminum Rolled Products Market recovery trajectory?
The pandemic caused severe supply chain fractures and sudden demand destruction across aerospace and automotive sectors in 2020. However, our research shows a robust V-shaped recovery driven by surging food packaging foil consumption and accelerated e-commerce logistics requirements.
Competitive Benchmarking and Industry Concentration
The market features high consolidation among tier-one multinational giants. Industry leaders like Novelis Inc., Constellium SE, and Hindalco Industries Ltd. leverage massive global rolling footprints to secure long-term contracts with multinational OEMs, outcompeting regional players.
Executive Summary of the Aluminum Rolled Products Market
This proprietary report synthesis highlights a transformative growth cycle for the Aluminum Rolled Products Market. Backed by stringent carbon reduction mandates, the sector represents an essential investment target for stakeholders seeking exposure to advanced industrial manufacturing.
Market Forecast and Long-Term Projections
Our forecasting models project the market to expand significantly, reaching $140.87 Billion by 2033. This trajectory represents a robust compound annual growth rate of 9.90% from 2027 to 2033, driven by massive infrastructure electrification investments.
Segmentation Analysis Across Foils, Plates, Sheets, and Grades
Segmentation spans multiple product categories: By Foil (Household Foil, Food Packaging Foil, Pharmaceutical Foil); By Grade (1xxx, 3xxx, 5xxx, 6xxx Series); By Plate (Thick, Thin, Specialty Plates); By Sheet (Standard, Anodized, Coated); and By End User (Automotive, Building, Packaging, Consumer Durables).
Geographic Distribution and Regional Market Performance
Regional performance varies widely, with Asia-Pacific dominating production volume driven by massive smelting hubs in China. Meanwhile, North America and Europe prioritize high-value anodized and coated sheets for premium electric vehicle applications and architectural facades.
In-Depth Regional Review of Consumption Hubs
North American demand centers on automotive body-in-white panels, while European markets enforce strict circular economy mandates favoring recycled 3xxx series alloys. Emerging economies in Asia-Pacific exhibit the highest consumption velocity for basic construction and packaging foils.
Strategic Positioning of Leading Companies
Major producers such as Arconic Rolled Products Corporation, Kaiser Aluminum Corp., and Emirates Global Aluminium focus heavily on high-margin aerospace plates and specialized industrial foils to maximize profitability amidst rising energy pressures.
Porter's Five Forces Analysis of Competitive Intensity
The industry experiences moderate-to-high competitive rivalry due to high capital expenditure requirements for rolling mills. Supplier power remains elevated due to primary aluminum pricing volatility, while buyer power is concentrated among major automotive and packaging conglomerates.
SWOT Analysis of the Global Rolling Sector
Strengths include unmatched material recyclability and high strength-to-weight ratios. Weaknesses involve high energy dependency during rolling operations. Opportunities lie in electric vehicle battery enclosures, whereas threats include trade tariffs and substitution by advanced polymer composites.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from bauxite mining and alumina refining to primary smelting, hot and cold rolling, and final surface treatment. Value capture is highest at the advanced rolling and finishing stages managed by specialized tier-one producers.
Investment Insights and High-Potential Growth Pockets
Investors should target facilities equipped for advanced closed-loop recycling and automated gauge control rolling. High-potential opportunities exist in specialized EV battery shielding plates and pharmaceutical-grade packaging foils.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Aluminum Rolled Products Market offers exceptional long-term growth driven by global lightweighting megatrends. Success requires continuous investment in sustainable alloy development and operational efficiency to navigate complex macroeconomic headwinds.
Rigorous Research Methodology and Triangulation Techniques
Our baseline estimates are meticulously triangulated by combining customs trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators from international aluminum associations to ensure absolute market accuracy.
Scope of the Report and Analytical Parameters
This report covers global revenue estimations and volume shipments from 2026 through 2033. It analyzes primary product classifications, regional consumption metrics, and competitive strategies while excluding downstream secondary fabrication processes.
Recent Industry Developments and Strategic Corporate Moves
Recent market activities feature major capacity expansions by firms like Gränges AB and Constellium SE, focusing on low-carbon rolled products. Strategic joint ventures and green-energy sourcing agreements dominate current corporate announcements across North America and Europe.