Market overview of the Copper, Nickel, Lead, And Zinc Market
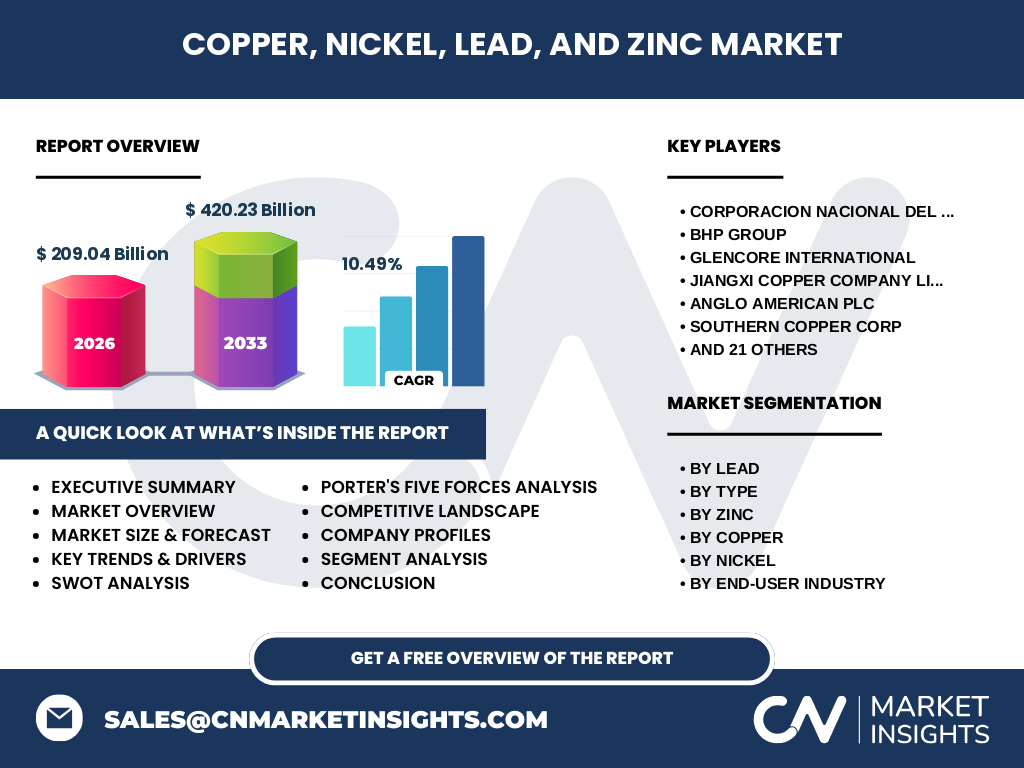
The Copper, Nickel, Lead, And Zinc Market valuation stands at 209.04 Billion in 2026. This foundational base metals sector drives global electrification, infrastructural expansion, and advanced industrial manufacturing through essential non-ferrous commodities.
Key market drivers, restraints, challenges, and opportunities
Our analysis indicates that accelerating EV adoption acts as the primary catalyst. Logistical bottlenecks and stringent environmental compliance imposed by bodies like the EPA constrain near-term output, while high-grade ore depletion presents severe operational challenges for miners.
Structural Growth Trends in Copper, Nickel, Lead, And Zinc
The shift toward green energy infrastructure dictates modern consumption patterns. Refined copper and nickel alloys see unprecedented demand surges driven by renewable energy grid transformations and high-density battery chemistry requirements.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions caused temporary smelter shutdowns across major hubs. V-shaped recovery trajectories materialized as state-sponsored stimulus packages unlocked substantial funding for heavy industrial and civil construction projects.
Competitive benchmarking and market concentration
The competitive landscape features high concentration among multinational titans like BHP Group, Glencore International, and Rio Tinto Group. These enterprises leverage vast asset portfolios to dominate global mining, smelting, and distribution networks.
Executive summary of the Copper, Nickel, Lead, And Zinc Market
Our research confirms the sector is poised for exceptional expansion, reaching 420.23 Billion by 2033. Operating at a robust 10.49% CAGR from 2027 to 2033, the market offers lucrative entry points for forward-thinking investors.
Market forecast from 2027 to 2033
Proprietary forecasting models project stellar growth from an initial 2026 baseline of 209.04 Billion to 420.23 Billion by 2033. This impressive trajectory is underpinned by a 10.49% CAGR fueled by rising urbanization and clean-tech applications.
Segmentation analysis across product categories
The market fragments by metal type into Copper, Zinc, Lead, and Nickel. Each metal subdivides into ore, refined metal, alloys, and scrap, catering directly to industrial manufacturing, transport, and construction end-users.
Regional market analysis and geographic distribution
Geographically, Asia-Pacific dominates consumption due to massive manufacturing bases in China and India. Meanwhile, Latin American nations such as Chile host the primary extraction hubs, supplying crucial raw inputs to global smelting facilities.
In-depth regional review of key markets
Latin America spearheads extraction through entities like Corporacion Nacional del Cobre de Chile (Codelco) and Southern Copper Corp. Concurrently, Asia-Pacific hubs drive consumption, balancing local smelter processing with heavy import reliance.
Company profiles and strategic positioning
Industry leaders like Vale SA, MMC Norilsk Nickel PJSC, and Anglo American plc secure competitive moats via low-cost asset ownership, ESG-compliant processing facilities, and strategic vertical integration across the base metals value chain.
Porter's Five Forces analysis of the industry
The industry exhibits moderate-to-high supplier power due to the scarcity of tier-one ore deposits. Threat of substitution remains low in structural wiring and galvanization, though threat of new entrants is severely limited by astronomical capital expenditure requirements.
SWOT analysis of the base metals ecosystem
Key strengths include unmatched asset quality among major producers, while weaknesses involve high carbon-intensity processes. Opportunities lie in closed-loop recycling networks, contrasted against regulatory threats from carbon border adjustment mechanisms.
Value chain analysis from raw extraction to end-user
The value chain flows from raw ore extraction by firms like Teck Resources Limited and Hudbay Minerals Inc. through capital-intensive smelting and refining stages, ultimately delivering high-purity metals to construction and transport manufacturers.
Investment insights and high-potential areas
Strategic capital should target greenfield recycling infrastructure and low-emission hydrometallurgical extraction technologies. Companies investing in traceable, low-carbon nickel and copper alloys will capture premium pricing margins from sustainability-focused original equipment manufacturers.
Conclusion and key takeaways for stakeholders
Surging to 420.23 Billion by 2033 at a 10.49% CAGR, the sector offers undeniable growth. Stakeholders must proactively address ESG mandates and secure long-term offtake agreements with established mining powerhouses to mitigate future supply shocks.
Research methodology for baseline estimates
Our exhaustive methodology triangulates data via primary stakeholder interviews with C-suite executives, cross-referencing customs trade registries, and analyzing secondary macroeconomic indicators from institutions like the International Copper Study Group.
Scope of the report and coverage parameters
This report encompasses global demand, supply, pricing dynamics, and competitive profiling across Copper, Nickel, Lead, And Zinc Market segments from 2026 to 2033, excluding localized artisanal mining operations lacking verified institutional reporting data.
Recent developments and strategic industry moves
Recent market activity highlights aggressive merger and acquisition strategies by firms like Zijin Mining Group Co. Ltd. and Glencore International. Enterprises are aggressively securing copper and nickel concessions to future-proof their supply chains against mounting geopolitical trade restrictions.