What is the market overview and strategic significance of the Silica Sand Market?
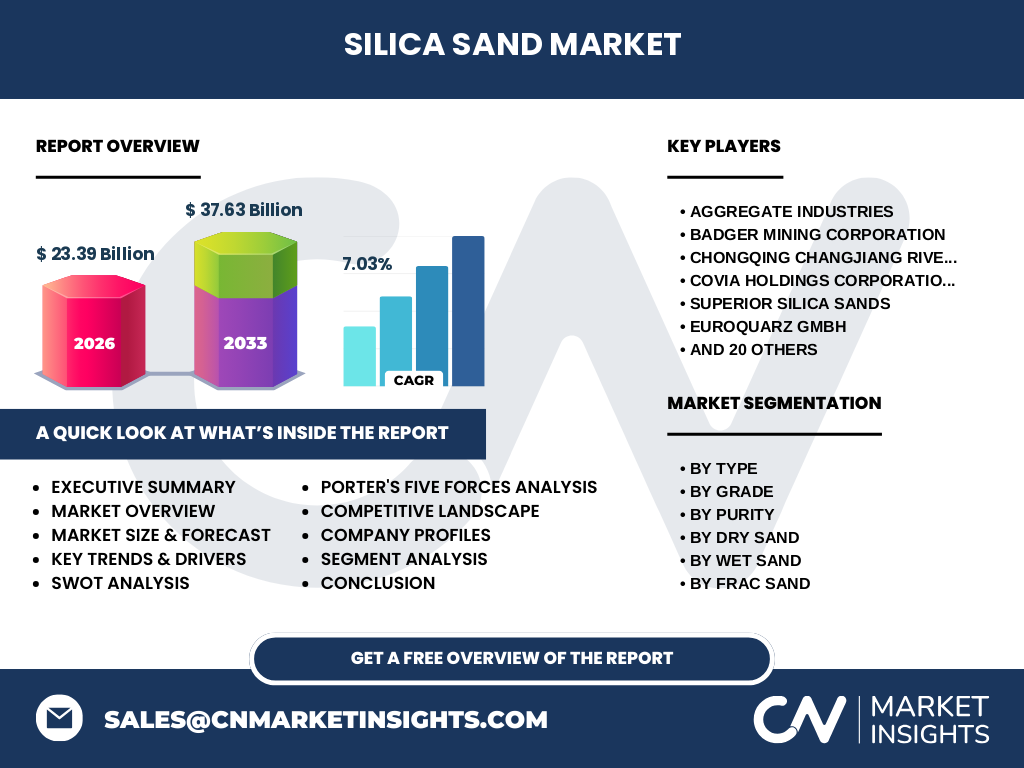
The Silica Sand Market is valued at 23.39 Billion in 2026, serving as an indispensable raw material across glass manufacturing, foundries, and hydraulic fracturing. Our analysis indicates that high-purity quartz reserves dictate regional manufacturing competitiveness, driving critical demand for specialized grades in industrial applications globally.
Structural Growth Drivers and Restraints
Growth is propelled by surging urban infrastructure development and hydraulic fracturing activities requiring Northern White and Southern White frac sand. However, stringent OSHA silica dust inhalation regulations and high logistics costs act as primary restraints, forcing operators to optimize supply chains near major end-user hubs.
Emerging Trends in Industrial Processing
The shift toward advanced processing technologies has heightened demand for high-purity quartz reaching 98% to 98.95% purity. Producers are increasingly investing in electrostatic separation and magnetic filtration to meet strict specifications for photovoltaic glass and electronics manufacturing.
How did the COVID-19 pandemic reshape the Silica Sand Market recovery trajectory?
Pandemic-induced supply chain disruptions and temporary automotive shutdowns severely impacted foundry sand demand in 2020. Yet, the subsequent post-lockdown infrastructure stimulus triggered a robust rebound, accelerating automation and dry sand processing efficiency among major producers like Covia Holdings and U.S. Silica.
Competitive Benchmarking and Industry Consolidation
The market features intense competition among heavyweights like Sibelco Group, Quarzwerke GmbH, and Covia Holdings Corporation. Strategic mergers and quarry acquisitions dominate the landscape, allowing top-tier firms to secure premium Northern White frac sand reserves and achieve vital logistical economies of scale.
Executive Summary of Key Findings
Our research forecasts the Silica Sand Market to expand from 23.39 Billion in 2026 to 37.63 Billion by 2033 at a steady 7.03% CAGR. Glass manufacturing and oil and gas extraction remain the primary revenue pillars underpinning this expansion.
Market Forecast Analysis from 2027 to 2033
Driven by a projected 7.03% CAGR, the market valuation will surge from 23.39 Billion in 2026 to 37.63 Billion by 2033. This acceleration reflects rising global requirements for precision-mesh foundry sand and ultra-clear solar glass.
Segmentation Analysis Across Product Types and Grades
Segmentation spans wet sand, dry sand, frac sand, filter sand, and coated sand, graded meticulously for glass, foundry, and chemical uses. Purity tiers ranging from 94% to 95.9% up to 98% to 98.95% dictate pricing power and end-use suitability across demanding industrial sectors.
Geographic Distribution and Regional Market Performance
North America leads consumption due to extensive onshore oil and gas drilling and robust flat glass manufacturing. Meanwhile, Asia-Pacific represents the fastest-growing regional market, fueled by rapid urbanization, massive construction pipelines, and expanding foundry output in emerging economies.
In-Depth Regional Review of Operational Constraints
Regional performance is heavily tied to rail and barge transport economics. While North American producers navigate complex regional trucking constraints, European operations under Quarzwerke and Sibelco face stringent environmental permitting frameworks governing quarry expansions and particulate emissions.
Strategic Positioning of Leading Industry Players
Key market participants including U.S. Silica Holdings Inc., Fairmount Santrol, and Badger Mining Corporation leverage vertically integrated transload networks. Their strategic positioning focuses on delivering specialized <70 mesh and 70-120 mesh frac sands directly to tight oil basins.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of buyers remains moderate due to the commodity nature of standard grades, though high switching costs apply for ultra-pure electronic silicon. Threat of substitutes is low, as few minerals replicate silica's thermal stability in foundry molds and glass matrices.
SWOT Analysis of the Silica Sand Sector
Key strengths lie in abundant mineral reserves and indispensable industrial utility. Weaknesses involve high freight-to-product value ratios. Opportunities emerge in high-purity photovoltaic glass sands, while threats center on tightening environmental regulations and silica exposure litigation.
Value Chain Analysis from Quarry to End-User
The value chain initiates with open-pit quartz mining, progressing through crushing, wet/dry screening, and acid leaching purification. Value is substantially added during resin coating and specialized mesh sizing before rail delivery to glassworks and oilfield service providers.
High-Potential Investment Insights and Opportunities
Investors should target premium processing facilities capable of upgrading lower-grade deposits to 98% to 98.95% purity. Capitalizing on resin-coated sand technologies for enhanced oil recovery and high-end foundry casting yields superior margins.
Conclusion and Strategic Takeaways
The Silica Sand Market demonstrates resilient fundamentals, tracking toward 37.63 Billion by 2033. Success requires balancing strict environmental compliance with technological investments in high-purity processing capabilities for specialized industrial applications.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining proprietary primary stakeholder interviews with mining regulatory registries, customs import-export logs, and secondary macroeconomic indicators from industrial manufacturing indices to ensure high forecast accuracy.
Scope of the Report and Coverage Parameters
This report covers global silica sand production, consumption, and trade flows across North America, Europe, Asia-Pacific, and emerging regions. Analysis specifically evaluates wet sand, dry sand, frac sand, and coated sand segments across all stated purity and mesh tiers.
Recent Industry Developments and Strategic Moves
Recent market activities involve major producers like Atlas Sand and Covia investing in automated rail terminals and eco-friendly resin coating lines. These strategic moves aim to reduce carbon footprints and lower last-mile delivery costs for oil and gas and glass manufacturing clients.