What is the scope and industry significance of the Heat Treating Market?
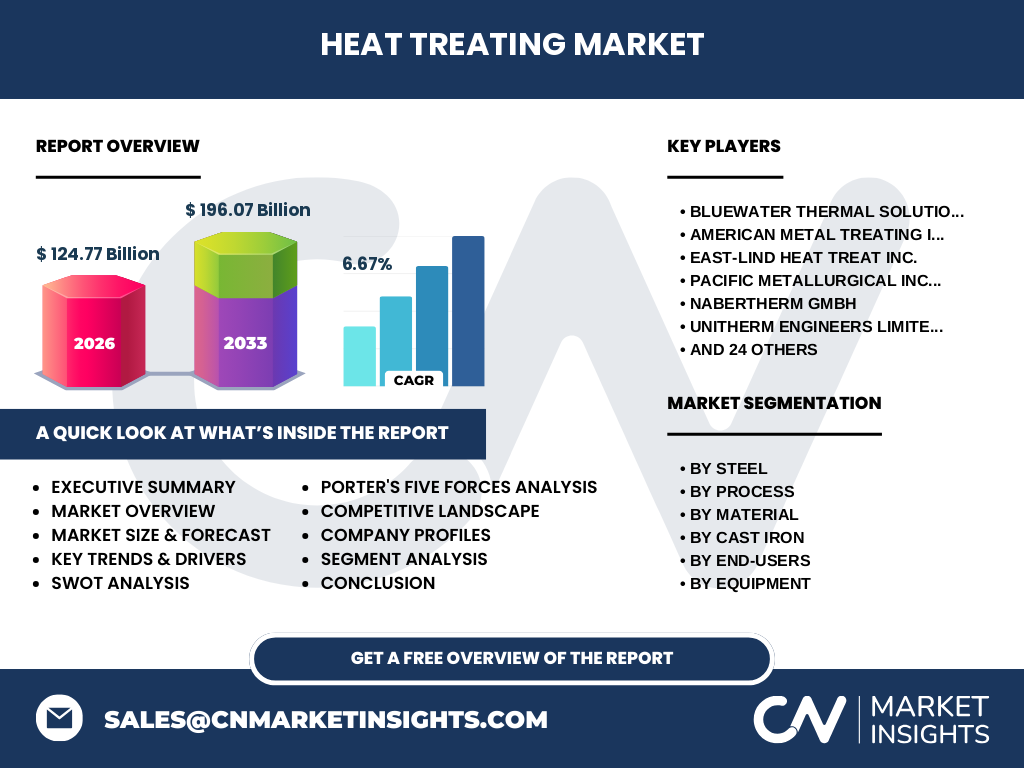
Our analysis indicates that the Heat Treating Market size represents a critical pillar of advanced manufacturing, valued at 124.77 Billion in 2026. This sector encompasses thermal processing services for structural integrity, supporting critical aerospace, automotive, and machinery supply chains relying on strict metallurgical specifications.
Key market drivers, restraints, challenges, and opportunities shaping the Heat Treating Market
The market is propelled by demand for lightweight components in automotive applications, though constrained by volatile energy prices for electrically heated furnaces. Opportunities abound in proprietary vacuum hardening technologies pioneered by innovators like Solar Atmospheres and Bodycote PLC.
Emerging trends and growth patterns in Heat Treating Market industry trends
Energy efficiency and digital process control are dominating Heat Treating Market industry trends. Operators are aggressively adopting vacuum and ion-nitriding techniques to eliminate hazardous quenching effluents while meeting stringent ISO metallurgical standards.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted aerospace and automotive supply chains, causing temporary shutdowns across commercial heat treaters. Recovery has been swift, driven by robust stimulus investments in heavy machinery and defense manufacturing, stabilizing thermal processing demand.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains fragmented, featuring specialized providers like Bluewater Thermal Solutions alongside equipment giants like Nabertherm GmbH. Competition hinges on proprietary metallurgical recipes, rapid turnaround capabilities, and NADCAP-certified quality assurance systems.
Executive Summary of Heat Treating Market analysis
The data suggests exceptional expansion, scaling from 124.77 Billion in 2026 to reach 196.07 Billion by 2033 at a 6.67% CAGR. Stakeholders must prioritize energy-efficient equipment modernization to capture high-margin aerospace contracts.
Market forecast from 2027 to 2033
Our forecasting models project steady acceleration, expanding from the 2026 baseline to 196.07 Billion by 2033. This 6.67% CAGR reflects robust global infrastructure spending and rising deployment of advanced high-strength steels.
Segmentation analysis across material, process, and end-user verticals
Segmentation reveals distinct demand pockets: By Steel (Carbon Steel, Alloy Steel, Stainless Steel, Tool Steel), By Process (Carburizing, Nitriding, Hardening, Tempering, Normalizing, Annealing), and By Equipment (Electrically Heated Furnace, Fuel-Fired Furnace). Automotive and aerospace remain dominant end-user verticals.
Regional market analysis and geographic performance
Geographic performance highlights North America and Europe as mature hubs driven by strict aerospace standards, while Asia-Pacific commands the highest volume growth due to rapid industrialization, automotive manufacturing, and heavy machinery production in regional industrial centers.
In-depth regional review of industrial clusters
Industrial clusters in North America rely heavily on commercial operations like Paulo Thermal Processing and Metlab Corporation. Meanwhile, Asian markets experience massive output surges driven by regional machining hubs and localized steel processing mills.
Company profiles and competitive positioning
Industry leaders like Thermax Limited and Ajax TOCCO International Ltd. supply advanced thermal infrastructure, while service providers such as Advanced Heat Treat Corp. and Specialty Steel Treating deliver specialized surface engineering solutions to OEM manufacturers.
Porter's Five Forces analysis of competitive intensity
Supplier power is moderate due to specialized refractory and energy dependencies, whereas buyer power remains high among major automotive OEMs. Threat of substitutes is mitigated by the irreplaceable mechanical improvements achieved via professional heat treatment.
SWOT analysis of the thermal processing sector
Key strengths include advanced metallurgy and proprietary process controls; weaknesses involve high capital expenditure and energy intensity. Opportunities reside in EV lightweighting alloys, while threats stem from strict environmental emissions regulations.
Value chain analysis from raw materials to end-users
The value chain starts with raw metal producers supplying steel, cast iron, and non-ferrous alloys, moving through commercial heat treaters utilizing specialized furnaces, and culminating in precision-engineered components for aerospace, defense, and automotive end-users.
Investment insights and high-potential growth areas
Investors should target greenfield facilities integrating zero-emission electric furnaces and AI-driven process monitoring. Companies like ONEX Corp. and NITREX.COM exemplify scalable models well-positioned for capturing high-margin sustainable manufacturing contracts.
Conclusion and key takeaways for market participants
Achieving profitability requires navigating rising energy costs through technological upgrading. Reaching the projected 196.07 Billion valuation by 2033 demands strategic alignment with green manufacturing mandates and advanced alloy requirements.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with executives at firms like East-Lind Heat Treat Inc. and Pacific Metallurgical Inc., and secondary macroeconomic indicators from industrial associations.
Scope of the report and coverage parameters
This report covers global commercial and captive heat treating operations through 2026-2033. Exclusions apply to rudimentary backyard blacksmithing operations not meeting commercial quality assurance and NADCAP compliance standards.
Recent developments in industry partnerships and product launches
Recent market activities feature technological collaborations by firms like Queen City Steel Treating Co. and S.M. Engineering & Heat Treating Inc. focusing on automated vacuum quenching systems to improve throughput and minimize distortion in complex aerospace geometries.