What is the comprehensive scope of the Digital Advertising Market?
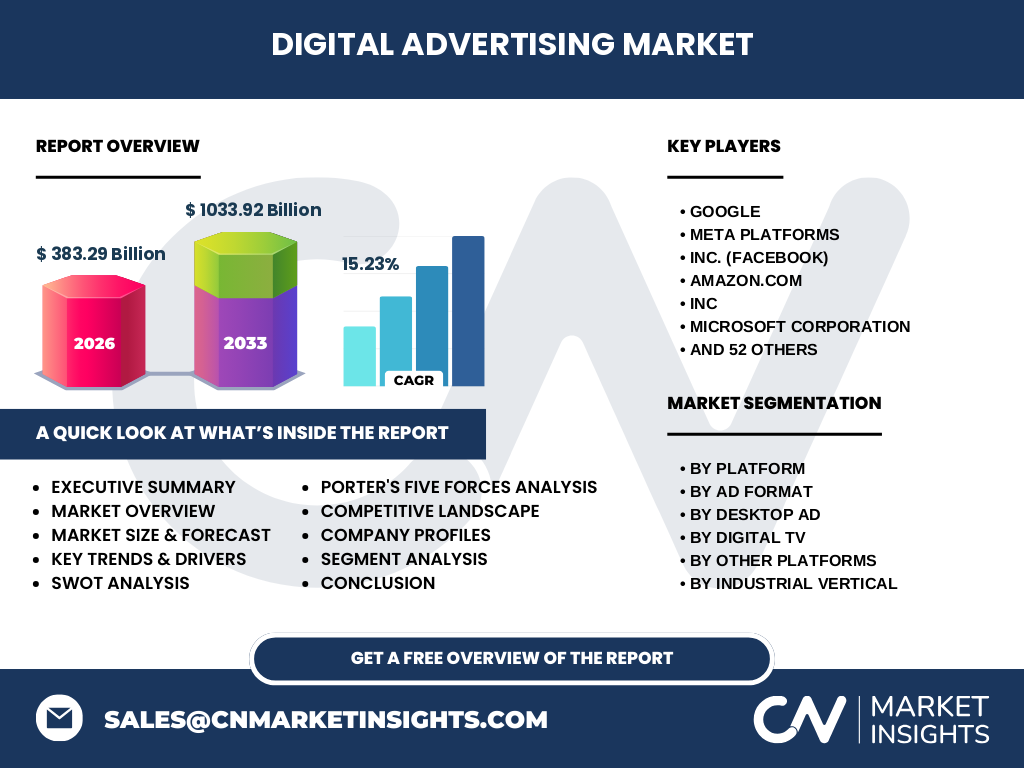
Our analysis indicates that the Digital Advertising Market represents a foundational pillar of modern commerce, valued at 383.29 Billion in 2026. This sector encompasses complex programmatic bidding architectures, cross-device attribution models, and algorithmic content distribution across desktop, mobile, and digital television ecosystems, driving high-velocity commercial interactions worldwide.
Key market drivers, restraints, challenges, and opportunities shaping Digital Advertising Market
Growth is supercharged by programmatic infrastructure adoption and surging connected TV investments, though strict privacy mandates from the European Data Protection Board create regulatory bottlenecks. Industry stakeholders must navigate signal loss from cookie deprecation while capturing high-margin opportunities within addressable linear television and privacy-compliant contextual targeting solutions.
The Shift Toward Immersive Formats and Privacy-First Targeting
The data suggests a rapid migration of budgets toward short-form online video, influencer marketing platforms, and retail media networks. Publishers and brands are aggressively abandoning legacy third-party cookie strategies in favor of first-party data clean rooms, directly addressing consumer privacy concerns while maintaining campaign ROI.
How did the COVID-19 pandemic permanently alter the trajectory of the Digital Advertising Market?
The global pandemic triggered an initial contraction in travel and retail spend during 2020, followed by a dramatic structural acceleration of e-commerce and streaming consumption. Consumer goods and retail advertisers permanently reallocated budgets from physical out-of-home to dynamic mobile apps and connected TV, cementing a permanent shift toward digital-first consumer engagement.
Competitive Benchmarking and Market Concentration
The landscape features a dominant oligopoly led by Google, Meta Platforms, Inc. (Facebook), and Amazon.com, Inc, which collectively capture a massive share of global ad spend through proprietary walled gardens. Meanwhile, specialized innovators like S4 Capital, Dentsu International, and regional players such as Netpeak (Moscow) carve out lucrative niches in programmatic optimization and localized campaign execution.
Executive Summary of the Digital Advertising Market
Our comprehensive research projects the Digital Advertising Market to expand from 383.29 Billion in 2026 to an astounding 1033.92 Billion by 2033, posting a robust 15.23% CAGR. Strategic investments in artificial intelligence-driven creative generation and cross-platform measurement will separate market leaders from underperformers over the next decade.
Long-Term Market Forecast from 2027 to 2033
Driven by compounding programmatic efficiencies and surging emerging market connectivity, the market will scale aggressively to reach 1033.92 Billion by 2033. Analyst projections confirm that maintaining a steady 15.23% CAGR requires continuous innovation in attribution modeling to combat shrinking attention spans across desktop and mobile channels.
Granular Segmentation Analysis by Platform, Format, and Vertical
The market divides across platforms like Mobile Ad (In-App And Mobile Web), Desktop Ad, and Digital TV, alongside diverse formats spanning Digital Display Ad, Internet Paid Search, Social Media, and Online Video. Key industrial verticals include Media And Entertainment, Consumer Goods And Retail Industry, Financial Service And Insurance, and Healthcare Sector, each requiring tailored execution strategies.
Geographic Distribution and Macro Regional Performance
North America commands the largest baseline share due to mature programmatic ecosystems and massive retail media investments, whereas Asia-Pacific exhibits the fastest organic expansion driven by mobile-first populations in Southeast Asia. Regional constraints such as local data residency laws in the EU and localized search engines in APAC dictate distinct go-to-market strategies for global holding companies.
In-Depth Regional Review and Localized Growth Dynamics
In North America, hyper-competitive retail media networks dominate digital budgets, while European markets operate under the stringent oversight of the Digital Services Act. Latin American and Middle Eastern markets—supported by agencies like Sherlock Communications and FP7 McCANN—are experiencing rapid digital transformation fueled by smartphone penetration and expanding fintech infrastructures.
Strategic Positioning of Leading Companies
Industry titans leverage massive proprietary datasets and machine learning engines to maintain dominance, while regional agencies and holding groups offer specialized execution. Enterprises like Baidu Advertising dominate localized search in Asia, whereas global consultants such as Accenture Interactive and PwC's Digital Services bridge enterprise technology integration with creative execution for Fortune 500 brands.
Porter's Five Forces Assessment of Competitive Pressures
Bargaining power of buyers is moderate to high due to sophisticated procurement teams managing multi-million dollar programmatic budgets. The threat of substitutes remains low given digital's unmatched targeting capabilities, though intense rivalry among dominant walled gardens and emerging retail media networks keeps competitive pressure at peak levels.
SWOT Analysis of the Digital Advertising Market
Key strengths include granular audience targeting and measurable attribution; weaknesses involve ad fraud and brand safety concerns. Prime opportunities lie in connected TV programmatic integration and generative AI ad creation, while regulatory crackdowns and privacy sandbox limitations present persistent threats to established behavioral tracking models.
Value Chain Analysis from Publisher Infrastructure to End-User
The value chain flows from foundational ad tech infrastructure providers and supply-side platforms (SSPs) to demand-side platforms (DSPs), ad exchanges, and media agencies before reaching end-user devices. Inefficiencies in this programmatic supply chain are actively being mitigated by direct publisher-to-brand partnerships and transparent marketplace protocols.
High-Potential Investment Insights and Strategic Recommendations
Investors should direct capital toward privacy-compliant identity resolution technologies, connected TV measurement platforms, and retail media software enablers. Our analysis indicates that businesses failing to adopt zero-party data collection frameworks will rapidly lose market share to agile competitors leveraging machine learning attribution.
Conclusion and Strategic Industry Takeaways
The trajectory toward 1033.92 Billion by 2033 underscores the permanent centrality of digital channels in global marketing mix modeling. Successful participants will master privacy-safe targeting, harness immersive formats like online video and digital out-of-home, and align operations with evolving regulatory frameworks across key global jurisdictions.
Methodological Approach to Baseline Triangulation
Our proprietary estimates are meticulously triangulated by combining statutory trade registry filings, primary executive stakeholder interviews across major agency holding groups, and macroeconomic indicators from international monetary institutions. Data validation involves cross-referencing programmatic bidding volume indices with enterprise earnings reports to ensure absolute precision.
Scope of the Report and Analytical Parameters
This report covers global advertising expenditures across mobile, desktop, and digital television platforms, segmented by major ad formats and key industrial verticals from 2026 through 2033. Limitations include the exclusion of unverified underground gray-market ad networks and informal peer-to-peer social commerce transactions lacking standardized programmatic tracking.
Recent Strategic Developments, Partnerships, and Product Launches
Recent months have seen major technology giants rollout advanced generative AI creative tools, while boutique agencies announce cross-border mergers to bolster regional capabilities. Strategic maneuvers by participants like Twitter, Inc. and HULU LLC highlight an ongoing race to capture premium connected TV and conversational commerce advertising revenues.