Market overview and industry significance of the Mineral Market
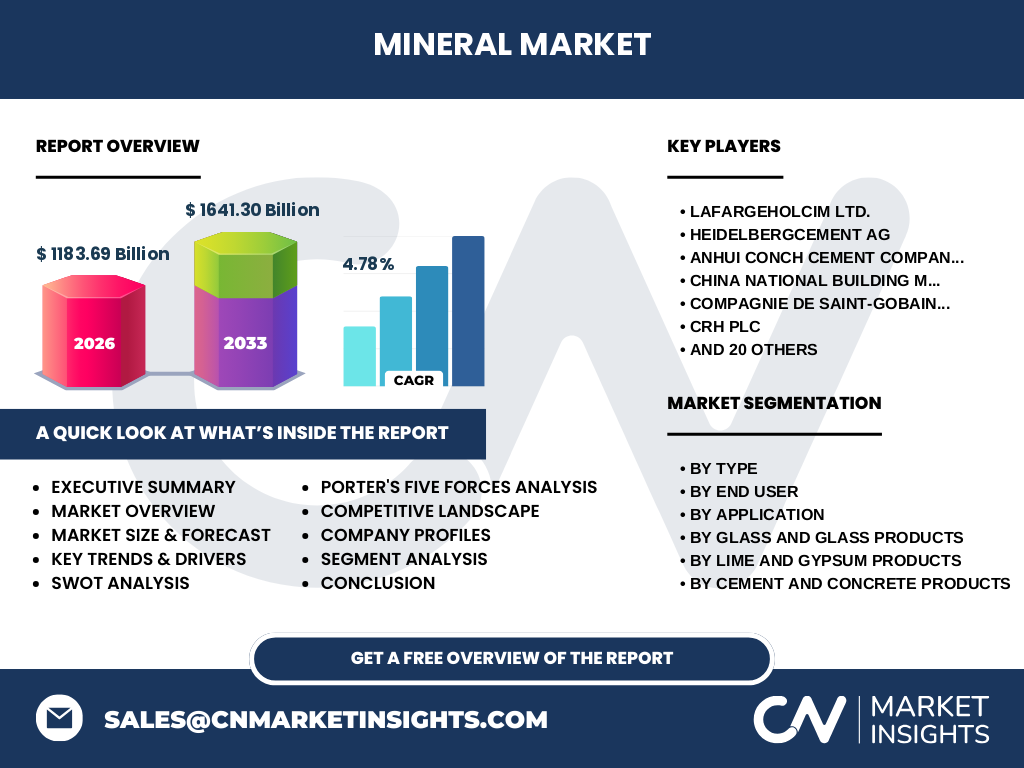
Our analysis indicates that the Mineral Market encompasses vital non-fuel raw materials fundamental to global infrastructure. Valued at 1183.69 Billion in 2026, this sector powers foundational construction, advanced manufacturing, and high-performance glass production. Key players like LafargeHolcim Ltd. and Anhui Conch Cement Company Limited drive raw material processing across international ports.
Key market drivers, restraints, challenges, and opportunities shaping the Mineral Market
The market is propelled by aggressive urbanization across developing economies, though stringent environmental regulations by bodies like the EPA pose operational hurdles. Energy cost volatility challenges heavy-kiln producers, yet lucrative opportunities emerge in low-carbon cement production. Companies such as Cemex S.A.B. de C.V. are capitalizing on green product portfolios to offset regulatory friction.
Emerging trends and growth patterns in the Mineral Market
Industry dynamics show a decisive pivot toward sustainable binders and circular construction methodologies. Decarbonization initiatives are transforming kiln operations for firms like HeidelbergCement AG, shifting demand toward blended cements and secondary raw materials that lower clinker-to-cement ratios and reduce carbon footprints.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions temporarily halted quarry operations and logistics via major maritime hubs. However, state-backed infrastructure stimulus packages catalyzed a robust V-shaped recovery. Demand surged past pre-pandemic baselines, rewarding agile operators who reconfigured their supply chains to mitigate regional labor shortages.
Competitive landscape, major players, and strategic dynamics
The Mineral Market industry trends highlight consolidation among multinational giants balancing scale with local quarry access. Firms like CRH plc, Compagnie de Saint-Gobain S.A., and China National Building Material Group command significant share through vertical integration, securing captive raw material reserves and optimizing regional distribution networks.
Executive summary of the Mineral Market report
Our comprehensive evaluation confirms the Mineral Market market size will reach 1641.30 Billion by 2033, expanding at a steady CAGR of 4.78% from 2027. Urban expansion, green construction mandates, and technological innovations in refractory materials remain the primary catalysts for sustained enterprise value creation.
Market forecast from 2027 to 2033
Driven by sustained infrastructure investments, the sector will expand from its 2026 baseline to 1641.30 Billion by 2033, achieving a compound annual growth rate of 4.78%. Long-term forecasting demonstrates resilience, supported by steady demand for ready-mix concrete and specialized flat glass products.
Segmentation analysis across product types and end-users
The market is categorized by type into Cement and Concrete Products, Glass and Glass Products, Non-Metallic Mineral Products, Clay Products and Refractories, and Lime and Gypsum Products. End users span Construction and Manufacturing sectors, deploying specific grades like Portland cement, fiberglass, and refractory bricks for heavy industrial applications.
Regional market analysis and geographic performance
Geographic performance is led by Asia-Pacific, fueled by rapid megacity expansion in China and India. Meanwhile, North America and Europe exhibit steady modernization cycles, prioritizing eco-friendly insulation materials, lightweight gypsum boards, and recycled aggregate solutions to meet stringent green building codes.
In-depth regional review of key markets
Asia-Pacific dominates consumption volume, leveraging local manufacturing hubs for container glass and ceramic products. In contrast, European markets focus heavily on carbon-neutral lime and gypsum production, driven by strict EU ETS compliance mandates that penalize high-emission pyroprocessing operations.
Company profiles and strategic positioning of leading enterprises
Industry leaders maintain distinct competitive moats through geographic diversification and product innovation. UltraTech Cement Limited and Siam Cement Group focus on regional cost leadership, whereas Saint-Gobain and Owens Corning prioritize high-margin specialty glass and advanced thermal insulation solutions.
Porter's Five Forces analysis of competitive intensity
The threat of new entrants remains low due to high capital expenditure requirements for quarries and kilns. Bargaining power of buyers is moderate to high in commoditized segments like Portland cement, whereas supplier power is dictated by proximity to high-purity limestone and silica sand deposits.
SWOT analysis of the Mineral Market ecosystem
Key strengths include essential utility in all construction; weaknesses involve high carbon intensity; opportunities lie in carbon capture utilization; and threats stem from tightening environmental compliance and substitute building materials.
Value chain analysis from raw materials to end-users
The value chain begins with raw extraction at quarries and mines, advancing through energy-intensive crushing, grinding, and pyroprocessing. Finished goods flow through complex distribution channels to reach commercial contractors, precast fabricators, and residential builders.
Investment insights and high-potential areas
Investors should target greenfield decarbonization technologies, alternative supplementary cementitious materials, and high-purity silica assets. Firms integrating carbon capture utilization and storage into lime and cement manufacturing present superior long-term risk-adjusted return profiles.
Conclusion and key takeaways for stakeholders
The Mineral Market offers durable growth prospects backed by a 4.78% CAGR through 2033. Success requires proactive adaptation to environmental regulations, digital supply chain optimization, and strategic investments in sustainable product formulations.
Research methodology and baseline triangulation
Our baseline estimates are rigorously triangulated by cross-referencing national trade registry data, primary executive interviews with industry leaders at firms like Buzzi Unicem and Knauf Gips KG, and secondary macroeconomic indicators from global construction indices.
Scope of the report and coverage parameters
This research evaluates global production, consumption, and trade flows across specified mineral segments from 2026 to 2033. Limitations include localized informal mining exclusion and unforeseen geopolitical disruptions impacting cross-border raw material freight.
Recent developments, partnerships, and strategic moves
Recent industry momentum features major cross-border acquisitions, joint ventures in carbon-neutral cement R&D, and facility upgrades by market makers like Wienerberger AG and Martin Marietta Materials, aimed at enhancing operational efficiency and reducing clinker emissions.