What is the scope and industry significance of the Fifth Generation (5G)-Powered Smart Stadiums Market?
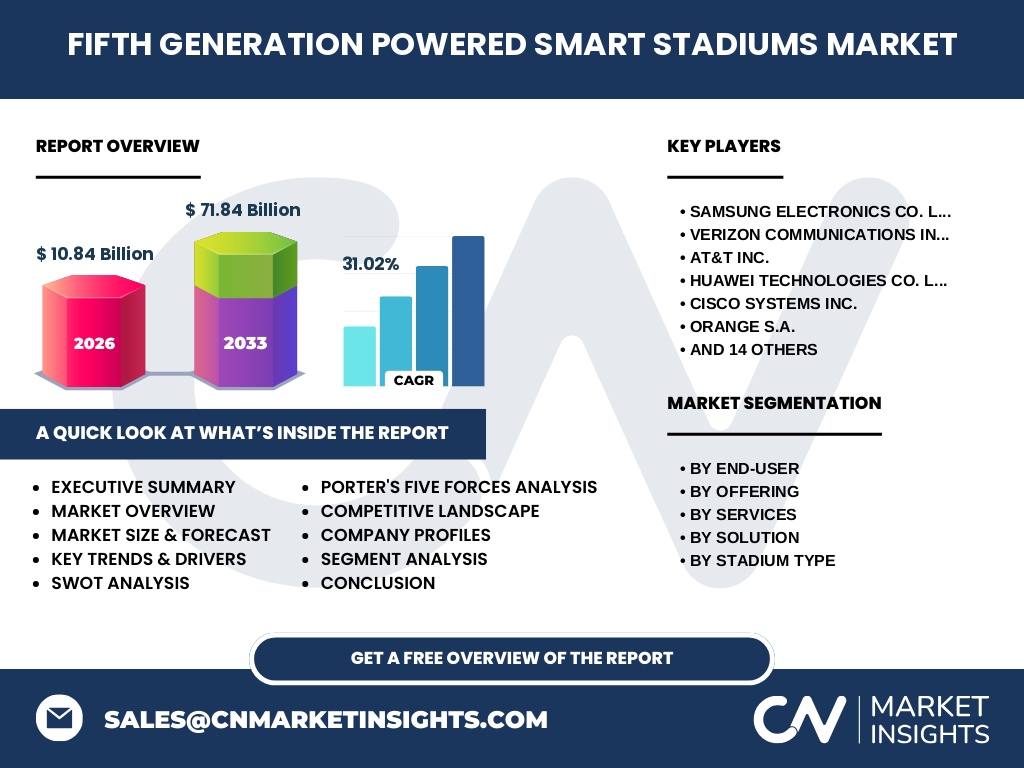
Our analysis indicates that the Fifth Generation (5G)-Powered Smart Stadiums Market valued at 10.84 Billion in 2026, fundamentally redefines live venue operations. By leveraging ultra-reliable low-latency communication (URLLC), this ecosystem transforms traditional venues into hyper-connected hubs, integrating millimeter-wave frequencies and Citizens Broadband Radio Service (CBRS) spectra to support immersive fan experiences and automated venue management.
Structural Growth Drivers and Restraints
The market is propelled by surging demand for multi-gigabit wireless connectivity and immersive augmented reality broadcast overlays. However, deployment is constrained by prohibitive capital expenditure for distributed antenna systems (DAS) and stringent municipal electromagnetic field (EMF) regulations enforced by bodies like the FCC and ITU, creating complex compliance hurdles for arena operators.
Emerging Trends in the Fifth Generation (5G)-Powered Smart Stadiums Market industry trends
The shift toward private 5G core deployments is accelerating, allowing venues to guarantee deterministic network performance independent of public carrier congestion. Concurrently, integration of computer vision powered by edge computing infrastructure enables real-time crowd flow optimization and cashierless concession operations.
How did the COVID-19 pandemic impact the Fifth Generation (5G)-Powered Smart Stadiums Market analysis?
The pandemic initially froze capital outlays for venue upgrades, yet it ultimately accelerated the adoption of contactless ticketing, biometric access control, and sanitization robotics. As live attendance rebounded, stadium operators prioritized resilient, touchless connectivity infrastructure to ensure public health compliance and restore consumer confidence.
Competitive Benchmarking and Industry Concentration
Market concentration is moderate to high, dominated by telecommunications giants and infrastructure vendors. Samsung Electronics Co. Ltd. and Huawei Technologies Co. Ltd. spearhead radio access network (RAN) rollouts, while enterprise specialists like Cisco Systems Inc. provide foundational routing architectures essential for handling massive concurrent data loads.
Executive Summary of the Fifth Generation (5G)-Powered Smart Stadiums Market market size
Our research projects the Fifth Generation (5G)-Powered Smart Stadiums Market to surge from 10.84 Billion in 2026 to 71.84 Billion by 2033, expanding at a robust 31.02% CAGR. This hyper-growth is driven by the convergence of edge computing, IoT sensor arrays, and advanced networking solutions across global sports and entertainment venues.
Long-Term Market Forecast (2027 to 2033)
Driven by widespread commercial adoption of standalone (SA) 5G architecture, the market will experience exponential acceleration through 2033. The projected valuation of 71.84 Billion reflects increased monetization through dynamic mobile ticketing, localized advertising, and specialized enterprise services tailored for multi-purpose arena operators.
Comprehensive Segmentation Analysis
The market is segmented by End-User (Sports Arenas, Concert Venues, Convention Centers), Offering (Solution, Services), Services (Consulting, Managed, Support, Network Optimization, Training), Solution (Network Infrastructure, Edge Computing, IoT/Sensors, AI/Analytics, Security, Connectivity Management), and Stadium Type (Outdoor, Multi-Purpose, Indoor), tailoring deployments to distinct operational demands.
Geographic Distribution and Regional Performance
Regional performance varies based on local telecommunications infrastructure and government spectrum auctions. North America leads in early commercial deployments due to aggressive carrier investments, while Asia-Pacific represents the fastest-growing territory fueled by newly constructed smart arenas and government-backed digital infrastructure initiatives.
In-Depth Regional Review
North America anchors global market share, supported by major telecommunications players like Verizon Communications Inc. and AT&T Inc. deploying ultra-wideband nodes across premier sports facilities. Meanwhile, European venues navigate stringent GDPR data privacy mandates while integrating private networks supplied by Nokia Corporation and Ericsson.
Strategic Positioning of Leading Company Profiles
Industry leaders employ distinct specialization strategies; Corning Incorporated and CommScope Holding Company Inc. dominate physical fiber and antenna pathways, whereas AiFi Inc. pioneers autonomous retail solutions. Telemetry innovators like Boingo Wireless Inc. focus on neutral-host indoor wireless deployments to maximize venue coverage efficiency.
Porter's Five Forces Analysis
Bargaining power of suppliers is moderate due to specialized semiconductor and fiber optic components required for ultra-low latency infrastructure. Threat of substitute technologies remains low as Wi-Fi 7 cannot match the deterministic mobility and high-density connection capacity offered by dedicated 5G enterprise architectures.
SWOT Analysis of the Ecosystem
Core strengths include ultra-low latency and massive device connection capacity. Weaknesses involve high initial deployment costs for specialized hardware. Opportunities lie in monetizing private broadcast feeds, while threats encompass cybersecurity vulnerabilities targeting critical venue operational technology (OT) systems.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with raw material providers supplying silicon wafers and rare-earth elements for semiconductors, flowing through hardware manufacturers like ZTE Corporation and Hewlett Packard Enterprise Company, system integrators like BT Group plc, and ultimately delivering smart venue experiences to event attendees.
High-Potential Investment Insights and Strategic Recommendations
Investors should prioritize edge computing and AI analytics solution providers, as these segments capture the highest software margins. Strategic partnerships between telecom operators like Vodafone Group Plc and venue management firms present prime opportunities for scalable revenue-sharing deployment models.
Conclusion and Strategic Takeaways
The Fifth Generation (5G)-Powered Smart Stadiums Market represents a paradigm shift in venue monetization and operational efficiency. Reaching 71.84 Billion by 2033 at a 31.02% CAGR underscores that next-generation connectivity is no longer a luxury, but a core operational prerequisite for modern entertainment complexes.
Rigorous Research Methodology
Our baseline estimates are meticulously triangulated by combining proprietary trade registry data, primary stakeholder interviews with chief technology officers at firms like Rakuten Mobile Inc. and Telefónica S.A., and secondary macroeconomic indicators regarding global spectrum allocation and stadium capital expenditure budgets.
Scope of the Report and Analytical Limitations
This report covers global deployment metrics, hardware and service revenues, and regional adoption dynamics for 5G smart stadiums from 2026 through 2033. Limitations include unpredictable regulatory changes in regional spectrum allocation and unforeseen macroeconomic shifts affecting large-scale construction budgets.
Recent Industry Developments and Strategic Moves
Recent milestones include joint venture announcements between infrastructure providers like John Mezzalingua Associates LLC and wireless carriers to deploy modular 5G systems. Furthermore, network vendors such as Ruckus Networks Inc. continue launching converged Wi-Fi and private 5G platforms designed specifically for seamless stadium roaming.