What is the market overview and scope of the Distributed Natural Gas-Fueled Generation Market?
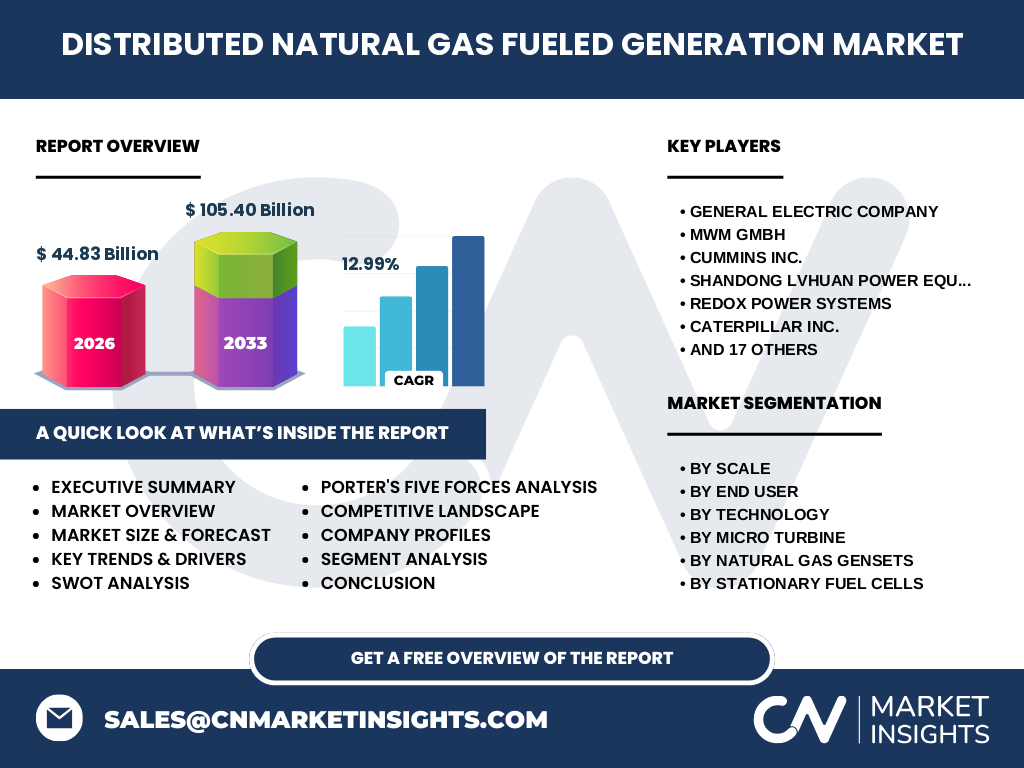
Our analysis values the Distributed Natural Gas-Fueled Generation Market at $44.83 Billion in 2026. This sector encompasses localized power units deployed near end-users, utilizing pipeline natural gas. Industry significance stems from grid-decongestion needs, relying on raw materials like specialty alloys for turbines and silicon for fuel cell stacks.
Structural Growth Drivers and Market Restraints
Growth is propelled by stringent Environmental Protection Agency (EPA) emissions caps and industrial demand for uninterrupted power. However, market restraints include volatile natural gas spot prices and complex interconnection hurdles imposed by regional transmission organizations, slowing rapid deployment for commercial facilities.
The Shift Toward High-Efficiency Microgeneration
The data highlights a distinct industry trend toward decentralized microgeneration and solid oxide fuel cells. Commercial end-users increasingly favor these assets for combined cooling, heating, and power (CCHP) applications, dramatically boosting thermal efficiency while mitigating localized grid failures.
How did the COVID-19 pandemic impact the Distributed Natural Gas-Fueled Generation Market?
The pandemic caused severe supply chain bottlenecks for raw casting materials and delayed engineering-procurement-construction timelines. Nevertheless, our research indicates a robust recovery trajectory driven by post-pandemic institutional focus on resilient, on-site backup generation to safeguard critical infrastructure against future disruptions.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high market concentration among multinational engineering giants. Industry leaders leverage extensive global service networks and proprietary combustion technology to outpace regional rivals, while maintaining aggressive R&D budgets to enhance electrical efficiency in reciprocating engines and microturbines.
Executive Summary of the Distributed Natural Gas-Fueled Generation Market
Our proprietary research confirms that the Distributed Natural Gas-Fueled Generation Market industry trends point toward rapid expansion, surging from $44.83 Billion in 2026 to $105.40 Billion by 2033. This trajectory reflects a robust 12.99% CAGR driven by decentralization mandates.
Long-Term Market Forecast (2027 to 2033)
Based on our econometric modeling, the market will experience explosive acceleration from 2027 to 2033, culminating in a market valuation of $105.40 Billion by 2033. This impressive 12.99% CAGR is anchored by expanding urban commercial developments and industrial electrification requirements.
Segmentation Analysis Across Scales, End-Users, and Technologies
Segmentation breaks down by scale (Microgeneration to Large-Scale), end-user (Residential, Commercial And Industrial, Building And Institutional), and technology (Natural Gas Gensets, Micro Turbine, Stationary Fuel Cells). Each tier serves distinct load profiles, with spark-ignition gensets dominating heavy industrial applications.
Regional Market Analysis and Geographic Performance
Geographic performance varies significantly due to localized pipeline infrastructure and regulatory incentives. North America and Europe lead adoption owing to mature natural gas distribution networks, whereas Asia-Pacific exhibits the fastest-growing demand profile due to rapid industrialization and urban energy deficits.
In-Depth Regional Review of Key Markets
North America remains a cornerstone market, supported by abundant shale gas reserves and favorable Federal Energy Regulatory Commission policies. Meanwhile, European markets prioritize high-efficiency stationary fuel cells to comply with stringent European Union decarbonization directives and local municipal heating mandates.
Company Profiles and Strategic Positioning
Key market participants such as General Electric Company, Caterpillar Inc., and Siemens AG dominate through diversified power portfolios. Innovators like Capstone Turbine Corporation and Doosan Corporation carve out high-growth niches in microturbines and solid oxide fuel cells respectively.
Porter's Five Forces Analysis of Competitive Intensity
Supplier power remains moderate due to specialized metallurgical requirements for turbine blades. However, competitive rivalry is fierce among established industrial stalwarts like Cummins Inc. and MWM GmbH, driving continuous innovation in lower-emission spark-ignition and compression-ignition gensets.
SWOT Analysis of the Industry Landscape
Strengths include high electrical reliability and lower carbon output than coal. Weaknesses involve high initial capital expenditure. Opportunities lie in hydrogen-blended natural gas compatibility, while threats include aggressive regulatory pushes toward complete electrification.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material extraction—specialty steels and rare earth catalysts—moving through precision manufacturing by firms like Wärtsilä Corporation and Mitsubishi Heavy Industries Ltd., culminating in integrated turnkey installation for commercial and institutional end-users.
Investment Insights and High-Potential Areas
Our analysis indicates prime investment opportunities in solid oxide fuel cells and modular microturbines. Investors should target asset developers partnering with industrial parks seeking reliable, low-emission on-site power generation solutions insulated from centralized grid volatility.
Conclusion and Key Takeaways for Market Stakeholders
The Distributed Natural Gas-Fueled Generation Market market size expansion to $105.40 Billion underscores a fundamental shift toward localized energy resilience. Stakeholders must align product roadmaps with hybrid fuel capabilities and high-efficiency CCHP configurations to capture market share.
Research Methodology and Baseline Estimation
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary stakeholder interviews with engineering executives, and secondary macroeconomic indicators from energy agencies to ensure unmatched analytical precision and market sizing reliability.
Scope of the Report and Coverage Parameters
This comprehensive report evaluates the global sector across defined technology, scale, and end-user parameters from 2026 through 2033. Exclusions apply to utility-scale natural gas combined-cycle power plants operating purely as centralized wholesale generation assets.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is defined by strategic joint ventures focused on fuel flexibility. Major equipment manufacturers are actively integrating advanced digital monitoring systems into legacy genset lines, enhancing predictive maintenance capabilities for mission-critical commercial and institutional deployments.