What is the market overview and industry significance of the Workload Scheduling And Automation Market?
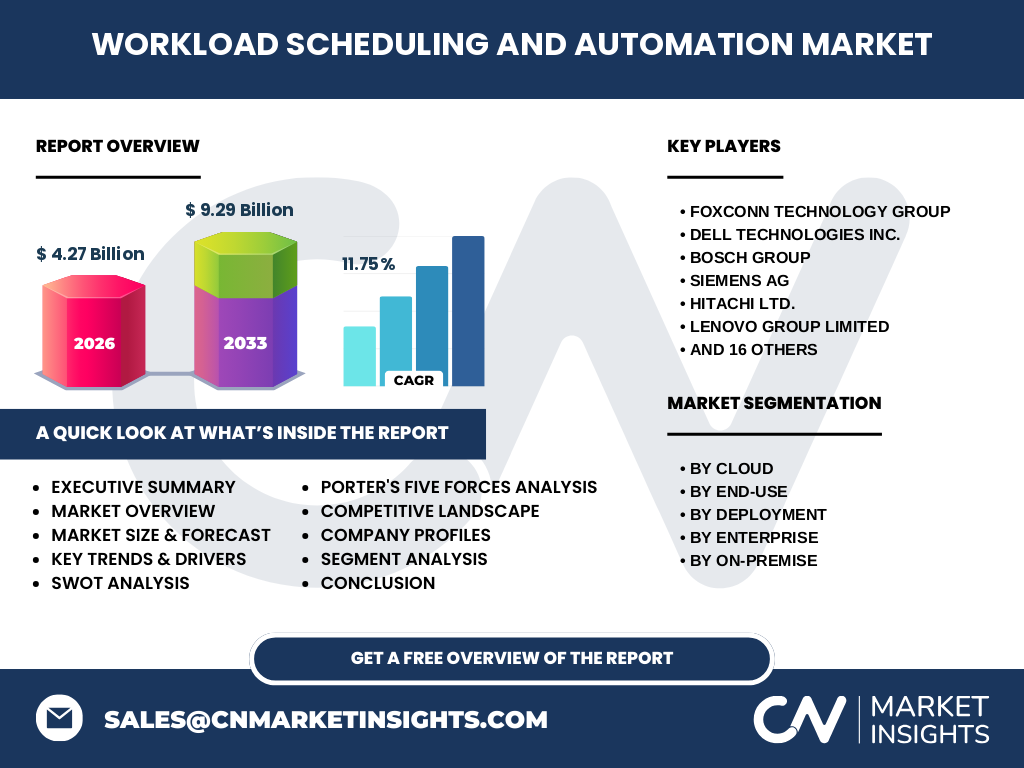
Our analysis indicates that the Workload Scheduling And Automation Market is valued at 4.27 Billion in 2026, driven by the critical need for operational orchestration across complex enterprise infrastructures. This sector enables organizations to coordinate batch processes, manage dependencies, and streamline digital pipelines without manual intervention.
Structural Growth Drivers and Market Restraints
Based on our research, growth is propelled by escalating enterprise digitalization and hybrid multi-cloud adoption. However, stringent data sovereignty regulations enforced by bodies like the European Union create deployment bottlenecks, restricting seamless cross-border job scheduling.
Emerging Trends in the Workload Scheduling And Automation Market Industry Trends
The shift toward predictive analytics and event-driven automation represents a major industry inflection point. Organizations are moving away from static time-based triggers toward dynamic, intelligent workload placement that optimizes resource consumption in real time.
How did COVID-19 impact the Workload Scheduling And Automation Market market size?
The pandemic accelerated remote operations, forcing enterprises to rapidly adopt automated cloud orchestration to maintain business continuity. This disruption catalyzed long-term modernization efforts, anchoring automation as a non-core expenditure that transitioned into a board-level strategic imperative.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high concentration among diversified industrial giants and specialized software providers such as International Business Machines Corporation and Hewlett-Packard Enterprise Company. These established players leverage extensive enterprise relationships to bundle workload automation with broader IT infrastructure management suites.
Executive Summary of the Workload Scheduling And Automation Market Analysis
Our comprehensive assessment highlights robust expansion, with the market projected to reach 9.29 Billion by 2033 at an impressive CAGR of 11.75%. Enterprise focus on digital agility and autonomous operations remains the primary catalyst for sustained economic upside.
Market Forecast and Trajectory from 2027 to 2033
The data suggests exponential acceleration from 2027 through 2033, expanding from the 2026 baseline of 4.27 Billion to culminate at 9.29 Billion. This trajectory is underpinned by an 11.75% CAGR as edge computing and containerized microservices multiply scheduling endpoints.
Segmentation Analysis Across Deployment and End-Use Categories
Market segmentation spans multiple dimensions: By Cloud encompasses Cloud-Based Workload Scheduling Solutions and Cloud-Based Automation Tools; By Deployment features On-premise and Cloud; By Enterprise divides into Large Enterprise and Small And Medium Enterprise; By On-premise covers On-Premise Deployment Solutions and On-Premise Automation Tools; and By End-Use ranges across Banking, Financial Services And Insurance (BFSI), IT And Telecommunication, Retail, Healthcare, Government And Public Sector, Manufacturing, and Other End-Users.
Geographic Distribution and Regional Market Analysis
Regional performance varies significantly, with North America leading due to high cloud maturity, while Asia-Pacific registers the fastest growth. Localized manufacturing hubs and expanding digital infrastructure across emerging economies dictate localized adoption velocities.
In-Depth Regional Review
North America dominates revenue generation, supported by early cloud adoption among Fortune 500 enterprises. Meanwhile, the Asia-Pacific region displays aggressive uptake driven by rapid digital transformation initiatives in manufacturing and financial sectors.
Company Profiles and Strategic Positioning
Key ecosystem participants include Foxconn Technology Group, Dell Technologies Inc., Siemens AG, Hitachi Ltd., and Schneider Electric SE. These industry leaders integrate workload automation capabilities into industrial Internet of Things (IoT) frameworks and smart factory environments.
Porter's Five Forces Analysis
Industry rivalry is intense, mitigated only by high customer switching costs associated with deeply embedded job scheduling scripts. Supplier power remains moderate, while the threat of substitution from native cloud provider tools exerts persistent pricing pressure.
SWOT Analysis of the Market Landscape
Key strengths include robust multi-platform integration capabilities, while weaknesses involve steep initial configuration complexities. Opportunities lie in artificial intelligence-driven predictive scheduling, balanced against threats from open-source orchestration frameworks.
Value Chain Analysis from Development to End-Users
The value chain flows from core algorithmic research and raw code development by software vendors, through systems integrators and cloud providers, ultimately delivering autonomous efficiency to end-user sectors like BFSI and manufacturing.
Investment Insights and High-Potential Areas
Investors should prioritize niche software vendors specializing in hybrid cloud orchestration and AI-driven anomaly detection. These segments offer the highest margin potential as enterprises grapple with multi-cloud infrastructure complexity.
Conclusion and Key Takeaways
The Workload Scheduling And Automation Market represents a high-growth investment frontier, scaling at an 11.75% CAGR toward 9.29 Billion by 2033. Organizations that master hybrid workload orchestration will capture dominant market share.
Research Methodology for Baseline Estimates
Our research methodology triangulates data using primary stakeholder interviews with enterprise Chief Technology Officers, secondary macroeconomic indicators, and rigorous trade registry analysis to establish dependable baseline valuations.
Scope of the Report and Coverage Parameters
This report covers global deployment models, enterprise tiers, and key end-use verticals from 2026 to 2033. Exclusions involve localized custom-built in-house scripting tools that lack commercial enterprise licensing structures.
Recent Developments, Partnerships, and Strategic Moves
Recent market activity is characterized by strategic cloud partnerships and acquisitions aimed at unifying mainframe and cloud workload environments. Industry leaders are actively embedding machine learning algorithms to automate error recovery and resource provisioning.