What is the scope and market size of the Metal Forming Market?
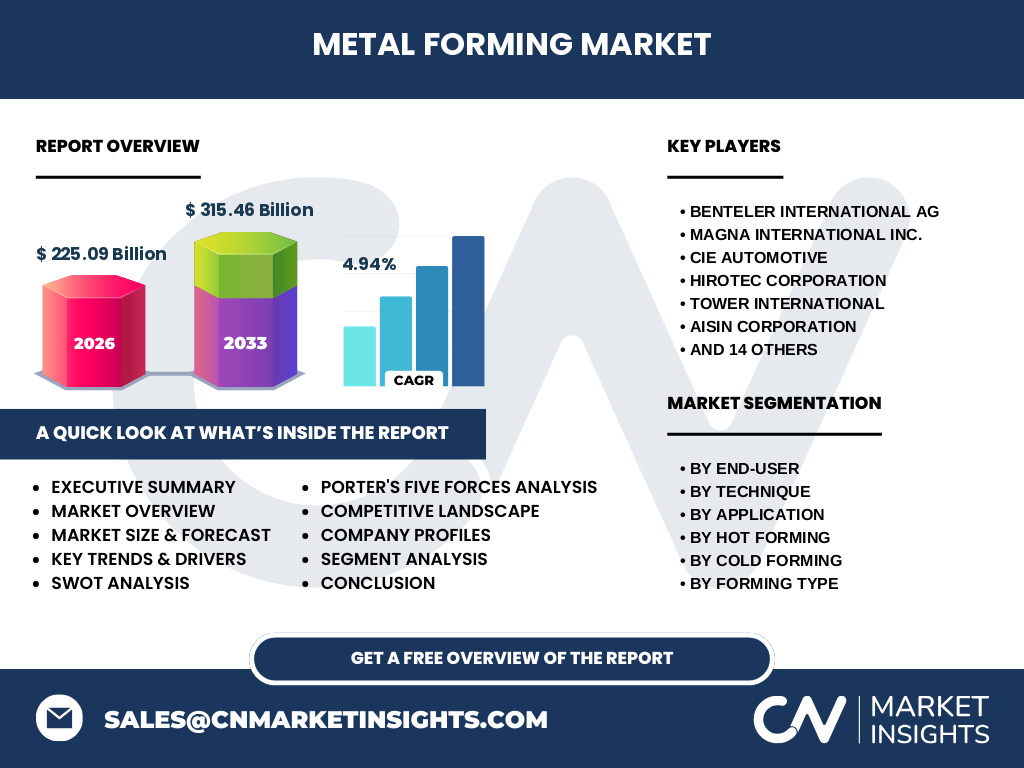
Our analysis indicates that the Metal Forming Market market size is valued at $225.09 Billion in 2026, reflecting its vital role in processing advanced high-strength steel, aluminum, and magnesium alloys into mission-critical structural and closure components for global manufacturing ecosystems.
Structural Growth Drivers and Market Restraints
Based on our research, the industry is propelled by stringent vehicle lightweighting mandates from bodies like the EPA and European Commission. However, volatile alloy input costs and strict OSHA machinery safety regulations act as notable constraints for tier-one stamping and roll-forming operations.
Emerging Industry Trends in Metal Forming
The shift toward hot stamping and press hardening of boron steels dominates current Metal Forming Market industry trends. This evolution allows suppliers like ArcelorMittal Tailored Blanks to deliver exceptional crash-safety performance for electric vehicle body-in-white structures.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains across key logistics hubs and major ports, forcing sudden line stoppages. The subsequent recovery trajectory highlights a decisive rebound driven by automated hydroforming and advanced cold heading technologies in precision engineering.
Competitive Benchmarking and Industry Concentration
The competitive landscape features high concentration among multinational tier-one heavyweights. Magna International Inc. and Gestamp Automoción leverage massive global press footprints to dominate complex chassis assemblies, whereas specialized players like PMF Industries focus on niche flow forming.
Executive Summary of Key Findings
The data suggests exceptional momentum, driving the global valuation from $225.09 Billion in 2026 to a forecasted $315.46 Billion by 2033 at a 4.94% CAGR. Success requires strategic integration of warm and cold forming methodologies.
Market Forecast from 2027 to 2033
Our projections confirm steady expansion, lifting the market from its 2026 baseline to reach $315.46 Billion by 2033. This trajectory represents a robust 4.94% CAGR, fueled by heavy infrastructure outlays and rising demand for industrial machinery.
Segmentation Analysis Across Techniques and Applications
The market is heavily segmented by technique—encompassing Roll Forming, Stretch Forming, Stamping, Deep Drawing, and Hydroforming—and by application across Body in White (BIW), Chassis, and Closures, supporting diverse structural demands in automotive and construction.
Regional Market Performance and Distribution
Geographic performance remains heavily skewed toward industrialized manufacturing corridors in North America, Europe, and Asia-Pacific. Localized environmental compliance standards heavily influence whether regional plants invest in energy-intensive hot forming or efficient cold drawing setups.
In-Depth Regional Review
Our regional insights reveal that North American and European markets prioritize lightweight aluminum BIW applications to meet fleet emissions targets, while Asian markets rapidly expand steel roll forming capacities to supply booming industrial machinery and local automotive sectors.
Strategic Company Profiles
Industry leaders maintain distinct strategic positioning. Benteler International AG and CIE Automotive focus heavily on modular chassis components, while Voestalpine AG and Thyssenkrupp Automotive Body Solutions pioneer proprietary ultra-high-strength steel tailoring techniques.
Porter's Five Forces Analysis
The industry experiences moderate-to-high supplier power due to fluctuating raw material prices for steel and aluminum. Meanwhile, buyer power remains intense among major OEMs, pressuring tier-one suppliers like Kirchhoff Automotive and Martinrea International Inc. on cost efficiency.
SWOT Analysis of the Metal Forming Sector
Key strengths include proprietary tooling expertise and advanced automation. Weaknesses involve high initial capital expenditure for hydraulic presses. Opportunities lie in electric vehicle architecture, while threats emerge from alternative composite materials replacing metallic components.
Value Chain Analysis from Raw Materials to End-Users
The value flow begins with primary metal producers supplying coils of steel and aluminum. Intermediate processors like Paramount Roll & Forming Inc. and Corrugated Metals Inc. shape these materials before tier-ones assemble them for final automotive and construction end-users.
Investment Insights and High-Potential Areas
High-potential investment opportunities concentrate in automated hydroforming and precision deep drawing for electric vehicle battery enclosures. Facilities investing in real-time IoT press monitoring secure distinct operational advantages over traditional manufacturers.
Conclusion and Strategic Takeaways
With the market scaling toward $315.46 Billion by 2033 at a 4.94% CAGR, stakeholders must embrace advanced multi-material forming capabilities. Long-term viability depends on adapting to strict environmental regulations and evolving lightweighting requirements.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data from international metal forming associations, primary stakeholder interviews with executives at Aisin Corporation and Toyota Boshoku Corporation, and secondary macroeconomic indicators.
Scope of the Report and Coverage Parameters
This report covers global production dynamics, material classifications including steel and aluminum, and technological subsets spanning cold, warm, and hot forming. Limitations exclude localized underground mining equipment production not captured in tier-one automotive supply data.
Recent Industry Developments and Strategic Moves
Recent developments highlight aggressive capacity expansions and technological partnerships. Companies like Miro Manufacturing Inc. and Metalspun Products Co. Inc. have upgraded facility robotics, while major groups secure long-term supply contracts for sustainable, low-carbon aluminum coil inputs.