What is the market overview and scope of the Vanadium Ore Market?
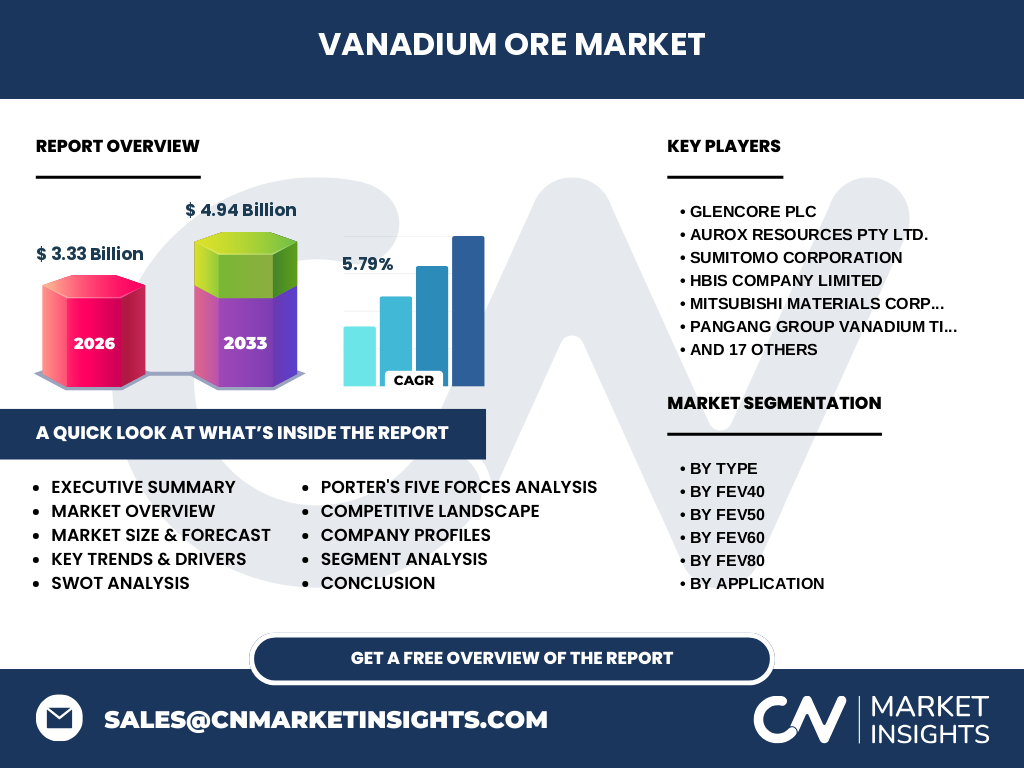
Our analysis indicates that the Vanadium Ore Market is valued at 3.33 Billion in 2026. This sector encompasses the extraction, processing, and distribution of vanadium-bearing raw materials like titaniferous magnetite, stone coal, and petcoke residues. The industry is critical for high-strength steel production and advanced energy storage systems, serving as a foundational element for heavy manufacturing and clean tech applications globally.
Key market drivers, restraints, challenges, and opportunities shaping Vanadium Ore Market
Growth is propelled by surging demand for high-strength low-alloy (HSLA) steels in automotive manufacturing. However, high energy intensity during pyro-metallurgical extraction acts as a major restraint. Market opportunities lie in expanding Vanadium Redox Flow Batteries (VRFBs) for grid storage, though operators must navigate stringent environmental regulations enforced by bodies like the EPA and EU directives.
Emerging trends and growth patterns in Vanadium Ore Market
The industry is experiencing a decisive shift toward sustainability, with miners optimizing low-carbon roasting techniques. Vanadium Ore Market industry trends highlight a rising preference for co-extraction from titaniferous magnetites. Furthermore, major producers are forging direct supply agreements with renewable energy project developers to secure long-term offtake for stationary storage electrolytes.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted supply chains, causing temporary shutdowns in South African and Chinese mines. Despite initial volatility, the recovery trajectory has been robust, fueled by post-lockdown stimulus packages targeting infrastructure and green energy grids. Prices rebounded sharply as structural deficits emerged between constrained mine output and surging post-pandemic steel consumption.
Competitive landscape and strategic dynamics
The Vanadium Ore Market analysis reveals a moderately consolidated landscape dominated by vertically integrated giants. Key players like Glencore plc, Largo Inc., and Pangang Group Vanadium Titanium & Resources Co. Ltd. control significant primary output. Strategic dynamics center on securing high-grade assets and optimizing vanadium recovery rates from slag and secondary industrial wastes to maintain cost leadership.
Executive summary of the Vanadium Ore Market report
Our comprehensive evaluation confirms that the Vanadium Ore Market will expand from 3.33 Billion in 2026 to reach 4.94 Billion by 2033, registering a robust 5.79% CAGR. This growth is underpinned by escalating structural consumption in metallurgical applications and an exponential surge in energy storage deployment, presenting lucrative entry points for strategic investors.
Market forecast and growth trajectory from 2027 to 2033
Based on our research, the 5.79% CAGR will drive the valuation from 3.33 Billion in 2026 to 4.94 Billion by 2033. This expansion is acceleration-backed by massive infrastructural investments in developing economies and the rapid commercialization of Vanadium Redox Flow Batteries, transforming the demand profile away from pure steel dependency.
Segmentation analysis across types, applications, and end-use industries
The Vanadium Ore Market market size is segmented by type (FeV40, FeV50, FeV60, FeV80), application (Iron and Steel, Chemical, Energy Storage), and end-use industry (Automotive, Aerospace and Defense, Steel Industry). FeV40 divides into powdered and granulated variants, while FeV80 includes heat-resistant and corrosion-resistant grades tailored for specialized metallurgical alloying.
Regional market analysis and geographic distribution
Geographic performance is heavily weighted toward regions with extensive steel manufacturing capacity and rich titaniferous magnetite reserves. Asia-Pacific dominates consumption due to massive steel output in China and India, while Latin America and Africa serve as vital extraction hubs driven by major producers like Largo Inc. and local mining conglomerates.
In-depth regional review of key markets
China remains the epicenter of both production and consumption, heavily influencing global pricing dynamics through domestic environmental inspections. Meanwhile, North American markets focus on securing critical mineral supply chains, with players like American Resources Corporation advancing domestic extraction projects to reduce import reliance for defense and aerospace applications.
Company profiles and strategic positioning
Industry leaders employ distinct strategies: Largo Inc. focuses on high-purity vanadium production for aerospace and energy storage, whereas Sumitomo Corporation and Mitsubishi Materials Corp. leverage extensive trading networks to secure reliable supply. Meanwhile, firms like Australian Vanadium Limited and Neometals Ltd. pioneer innovative processing technologies to enhance extraction yields.
Porter's Five Forces analysis of the sector
Supplier power is moderate due to high capital expenditure barriers in mining, but threatened by secondary slag recycling. Buyer power remains constrained by the specialized nature of ferrovanadium alloys. Threat of substitutes is low in high-strength steel, though moderate in stationary energy storage against lithium-ion alternatives.
SWOT analysis of the Vanadium Ore Market
Strengths include the unmatched metallurgical properties of vanadium in steel and long-duration storage capabilities. Weaknesses involve high sensitivity to steel industry cycles. Opportunities abound in grid-scale VRFB adoption. Threats encompass potential regulatory bottlenecks and volatile commodity price fluctuations driven by geopolitical shifts.
Value chain analysis from raw materials to end-users
The value chain initiates with open-pit or underground mining of titaniferous magnetite or stone coal. Ores undergo crushing, milling, and roasting with sodium salts, followed by leaching and precipitation to produce vanadium pentoxide. This intermediate is then reduced to ferrovanadium alloys before reaching steel mills and battery manufacturers.
Investment insights and strategic recommendations
Investors should target vertically integrated producers possessing direct exposure to both steel alloying and energy storage sectors. Funding innovative extraction technologies that lower carbon footprints will yield sustainable competitive advantages, especially as ESG mandates tighten across mining jurisdictions in Australia, South Africa, and North America.
Conclusion and key takeaways for stakeholders
The Vanadium Ore Market presents compelling growth prospects, scaling from 3.33 Billion to 4.94 Billion at a 5.79% CAGR. Stakeholders must capitalize on the dual-demand engine of traditional steel reinforcement and emerging energy storage applications while proactively managing environmental compliance risks.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registries, primary stakeholder interviews with C-suite executives at Glencore plc and Largo Inc., and secondary macroeconomic indicators from the World Steel Association and geological surveys, ensuring high-fidelity market sizing.
Scope of the report and coverage parameters
This report covers global revenue estimations and volume metrics for the Vanadium Ore Market from 2026 to 2033. It analyzes primary extraction, intermediate processing, and end-use consumption across four distinct ferrovanadium grade categories, while excluding non-commercialized laboratory-scale extraction techniques.
Recent developments in the industry
Recent strategic moves feature increased joint ventures between exploration juniors like Australian Vanadium Limited and energy storage integrators. Companies are actively investing in green-processing facilities and securing long-term supply pacts to insulate themselves against raw material volatility and meet rising demand from the clean energy sector.