Market overview of the Department Stores And Other General Merchandise Stores Market
Our analysis indicates that the Department Stores And Other General Merchandise Stores Market stands as a foundational pillar of global retail commerce, encompassing massive physical footprints and omnichannel distribution networks. Industry significance is underscored by its massive employment generation and critical role in consumer discretionary spending across urban and suburban nodes.
What are the core drivers and restraints shaping the Department Stores And Other General Merchandise Stores Market?
The market is propelled by aggressive supply chain digitization and shifting consumer habits favoring value retail. However, stringent labor regulations and rising commercial real estate lease costs act as notable restraints, challenging traditional margin structures for legacy operators.
Emerging trends and growth patterns in the Department Stores And Other General Merchandise Stores Market
Recent Department Stores And Other General Merchandise Stores Market industry trends reveal a profound pivot toward experiential retail and automated inventory tracking. Retailers are increasingly repurposing sprawling floor plans into localized fulfillment hubs to accelerate last-mile delivery.
COVID-19 impact analysis on the Department Stores And Other General Merchandise Stores Market
The pandemic drastically accelerated digital transformation across the Department Stores And Other General Merchandise Stores Market, forcing non-essential brick-and-mortar closures. Recovery trajectories varied wildly, favoring nimble enterprises with robust curbside pickup capabilities over traditional mall-anchor department stores.
Competitive benchmarking and strategic dynamics in the sector
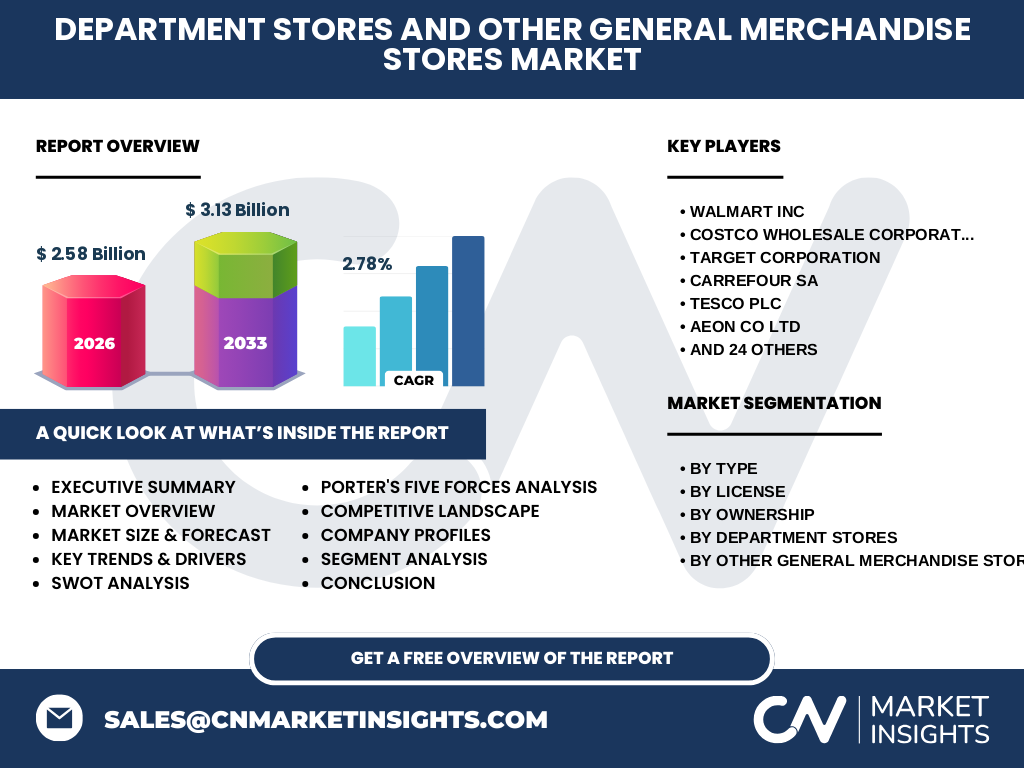
Market concentration remains moderately fragmented, dominated by retail giants like Walmart Inc, Target Corporation, and Amazon.com Inc. Strategic differentiation now relies heavily on proprietary private-label development and advanced logistics automation to withstand margin compression.
Executive summary of the Department Stores And Other General Merchandise Stores Market analysis
Our comprehensive research values the Department Stores And Other General Merchandise Stores Market at 2.58 Billion in 2026, expanding steadily toward future horizons. Executive synthesis highlights that omnichannel integration and aggressive value-tier positioning are the definitive prerequisites for sustained stakeholder profitability.
Long-term market forecast for the Department Stores And Other General Merchandise Stores Market
The data projects the Department Stores And Other General Merchandise Stores Market to reach 3.13 Billion by 2033, expanding at a steady CAGR of 2.78% from 2027. This trajectory reflects sustained consumer demand and structural efficiency gains across both physical and digital retail channels.
Segmentation analysis across product types, licenses, and ownership structures
The market bifurcates across multiple operational tiers: By Type (Department Stores, Other General Merchandise Stores), By License (Branded, Brand Licensed, Unbranded), and By Ownership (Retail Chain, Independent Retailer). Further granular categories include Full-Line Department Stores, Warehouse Clubs, Supercenters, and Dollar Stores, each serving distinct consumer demographics and shopping missions.
Geographic distribution and regional performance dynamics
Regional performance is heavily influenced by localized disposable income levels, urbanization rates, and regional logistics infrastructure. North America maintains a dominant revenue share, while Asia-Pacific registers the fastest growth, driven by rapid urbanization and the proliferation of hypermarket formats.
In-depth regional review of key geographic territories
North American performance is anchored by dominant discounting models, whereas European markets face stricter retail zoning laws and sustainability mandates. Latin American and emerging Asian sectors showcase immense greenfield potential, led by major regional players expanding their footprint into secondary cities.
Company profiles and strategic positioning of key industry participants
Industry titans such as Costco Wholesale Corporation, Carrefour SA, and Tesco PLC leverage massive procurement scale to maintain competitive pricing. Department store stalwarts like Macys Inc and Kohls Corporation focus heavily on digital marketplace integration and curated brand partnerships.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers remains exceptionally high due to low switching costs and transparent online pricing. Competitive rivalry is fierce among established retail chains, while the threat of new entrants is mitigated by the massive capital expenditure required for global supply chain infrastructure.
SWOT analysis of the global general merchandise retail sector
Key strengths include extensive supply chain networks and high brand equity, contrasted with weaknesses like thin operating margins. Opportunities lie in predictive retail analytics, while threats stem from persistent macroeconomic inflation and volatile consumer confidence.
Value chain analysis from raw material sourcing to end-users
The value chain initiates with global raw material sourcing and manufacturing hubs, passing through maritime and rail logistics terminals into centralized distribution centers. Final value is realized through storefront merchandising, e-commerce fulfillment, and seamless reverse logistics for returns management.
Investment insights and high-potential strategic areas
Capital deployment should prioritize automated warehouse robotics, AI-driven demand forecasting, and omnichannel fulfillment optimization. Investors are advised to target value-oriented retail formats like Dollar General Corporation and Ollies Bargain Outlet Holdings Inc for defensive portfolio shielding.
Conclusion and key takeaways for industry stakeholders
Sustained success in the Department Stores And Other General Merchandise Stores Market demands absolute operational agility and continuous technology adoption. Companies that successfully bridge physical store experiences with frictionless digital ecosystems will capture outsized market share through 2033.
Research methodology governing our market estimation
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with retail executives, and secondary macroeconomic indicators. Analytical validation involves econometric modeling to reconcile conflicting data streams and ensure high statistical confidence.
Scope of the report, coverage parameters, and analytical limitations
This report evaluates global market dynamics for department stores and general merchandise retail from 2026 through 2033. Limitations include unforeseen macroeconomic disruptions, sudden regulatory shifts in international trade policy, and localized currency volatility that may impact baseline valuations.
Recent developments, corporate announcements, and strategic maneuvers
Recent strategic maneuvers feature aggressive omnichannel expansions by enterprises like Target Corporation and localized supply chain regionalization by Amazon.com Inc. Partnerships with fintech providers for embedded consumer credit solutions have also become a dominant focal point for major retail groups.