Market Overview: Defining the Scope of the Retail Automation Market
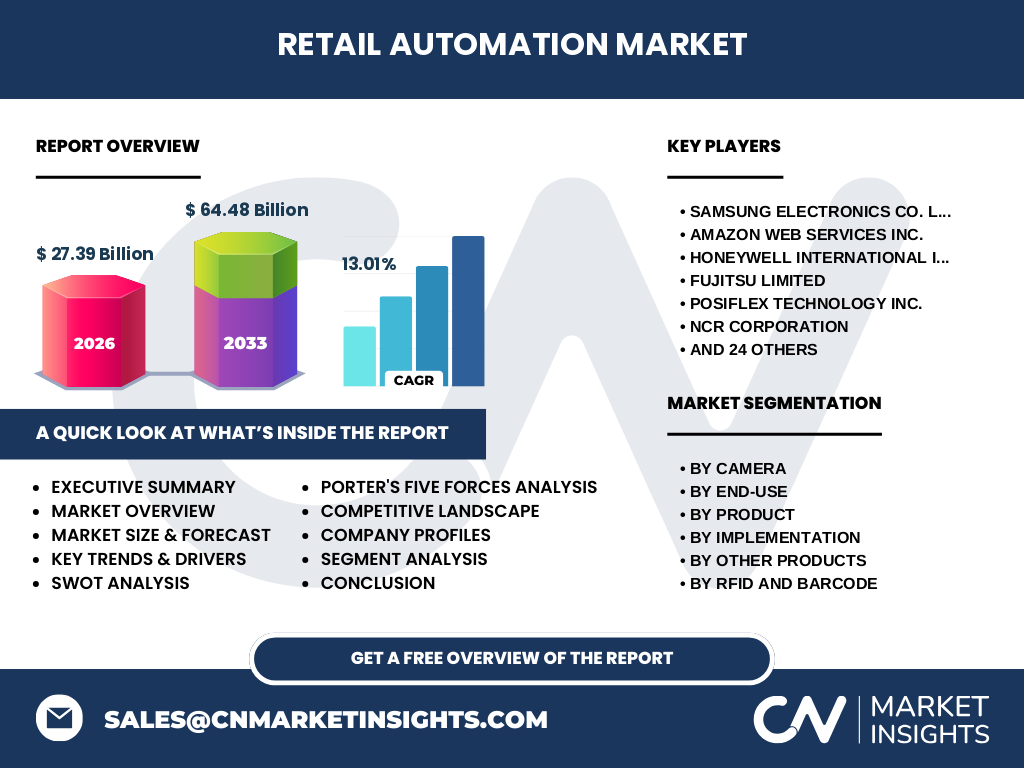
Our analysis indicates that the Retail Automation Market encompasses a comprehensive ecosystem of hardware, software, and integrated services designed to streamline storefront and warehouse operations. Valued at $27.39 Billion in 2026, this industry is foundational for modern supply chain execution. Driven by labor shortages and rising consumer expectations, market participants utilize advanced solutions ranging from Point-Of-Sale systems to Warehouse Robotics to optimize inventory accuracy, accelerate throughput, and eliminate friction across hypermarket and specialty store formats.
Structural Growth Drivers, Restraints, and Opportunities
The Retail Automation Market industry trends highlight several critical catalysts. Structural growth drivers include escalating minimum wage pressures and the imperative for real-time inventory visibility. Conversely, high upfront capital expenditure for automated infrastructure serves as a primary market restraint, particularly for single-item stores. However, emerging opportunities in cloud-native payment solutions and IoT-enabled electronic shelf labels present lucrative avenues for vendors like Zebra Technologies Corporation and Honeywell International Inc. to capture expanding enterprise wallet share.
Emerging Trends and Growth Patterns in Retail Automation
The Retail Automation Market analysis reveals a profound migration toward autonomous inventory tracking and cashierless checkout environments. Smart cameras for analytics and autonomous mobile robots are transforming traditional brick-and-mortar setups into data-driven fulfillment hubs. This evolution favors agile innovators capable of integrating edge computing with legacy retail architectures, significantly reducing shrinkage and optimizing labor allocation across major urban commercial centers.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The pandemic served as an unprecedented stress test for global supply chains, accelerating adoption within the Retail Automation Market. Lockdowns and social distancing mandates forced traditional supermarkets and fuel stations to fast-track self-service kiosks and contactless payment solutions. Our research shows that post-pandemic recovery has institutionalized these technologies, transforming temporary pandemic-era workarounds into permanent operational efficiencies that continue to buffer retailers against ongoing labor market volatility.
Competitive Benchmarking and Market Concentration Dynamics
The competitive landscape of the Retail Automation Market is characterized by moderate fragmentation at the software layer and higher concentration among hardware heavyweights. Industry leaders such as NCR Corporation, Fujitsu Limited, and Toshiba Global Commerce Solutions Inc. dominate through comprehensive end-to-end portfolios. Strategic M&A activity remains brisk as incumbents acquire niche robotics specialists and cloud POS providers to defend their market share against aggressive digital-first entrants.
Executive Summary: High-Level Synthesis of Key Findings
Our comprehensive evaluation confirms that the Retail Automation Market is positioned for robust expansion, scaling from $27.39 Billion in 2026 to reach an impressive $64.48 Billion by 2033. Propelled by a stellar 13.01% CAGR, the sector represents a critical investment frontier. Stakeholders must pivot toward integrated warehouse automation and intelligent point-of-sale platforms to maintain competitive parity in an increasingly consolidated retail landscape.
Long-Term Market Forecast from 2027 to 2033
Based on our research, the Retail Automation Market forecast projects explosive commercial momentum over the 2027 to 2033 timeframe. Achieving a projected valuation of $64.48 Billion by 2033 at a compound annual growth rate of 13.01%, the sector will outpace broader macroeconomic indicators. This trajectory is underpinned by surging enterprise investments in warehouse robotics, automated guided vehicles, and advanced RFID inventory management systems.
Granular Segmentation Analysis Across Core Categories
Our Retail Automation Market market size breakdown evaluates multiple intersecting categories: By Camera (Surveillance, Smart Analytics, Customer Behavior Tracking); By End-Use (Hypermarkets, Supermarkets, Fuel Stations, Retail Pharmacies); By Product (POS, RFID/Barcode, Cameras, Electronic Shelf Labels, Warehouse Robotics); By Implementation (In-Store, Warehouse); and specialized sub-segments including self-service kiosks, digital signage, automated guided vehicles, and cloud-based POS architectures.
Geographic Distribution and Regional Performance Dynamics
Regional performance within the Retail Automation Market varies significantly based on labor costs, regulatory frameworks, and retail density. North America maintains a dominant revenue share, driven by early adoption of automated micro-fulfillment centers. Meanwhile, the Asia-Pacific region demonstrates the fastest growth velocity, fueled by rapid urbanization, expanding hypermarket chains, and aggressive investments by technology innovators in densely populated metropolitan commercial districts.
In-Depth Regional Review of Commercial Hotspots
Examining specific regional nuances reveals that European markets prioritize strict data privacy compliance—such as GDPR—when deploying customer behavior tracking cameras and electronic shelf labels. Conversely, North American retailers focus heavily on mitigating labor shortages through aggressive deployments of autonomous mobile robots and cloud-based POS systems. Emerging markets in Latin America and Southeast Asia showcase high growth potential centered around mobile POS adoption and basic inventory management upgrades.
Strategic Positioning and Company Profiles of Industry Leaders
Leading participants in the Retail Automation Market deploy distinct competitive strategies to secure market dominance. Amazon Web Services Inc. and Samsung Electronics Co. Ltd. leverage cloud infrastructure and advanced hardware ecosystems to power seamless in-store intelligence. Concurrently, specialized robotics firms like 6 River Systems LLC and KUKA AG focus on warehouse fulfillment optimization, while established POS providers like Diebold Nixdorf Inc. and PAX Technology Inc. anchor traditional checkout evolution.
Porter's Five Forces Analysis of Competitive Pressures
Applying Porter's framework to the Retail Automation Market indicates moderate-to-high competitive rivalry driven by rapid technological obsolescence. Bargaining power of buyers remains elevated as major hypermarket chains demand customized, cost-effective solutions. Threat of substitutes is subdued due to the specialized nature of industrial warehouse robotics, while supplier power is moderate, balanced by component availability for RFID tags and barcode scanners.
SWOT Analysis: Internal Capabilities and External Realities
An assessment of the Retail Automation Market reveals compelling strategic positions. Strengths include high operational efficiency and robust inventory accuracy. Weaknesses involve steep initial implementation costs and integration complexities with legacy architectures. Opportunities center on emerging AI-driven analytics and cashierless stores, while threats encompass rising cybersecurity vulnerabilities and stringent global regulatory compliance requirements surrounding consumer data collection.
Value Chain Analysis from Raw Materials to End-Users
The Retail Automation Market value chain spans raw material procurement—such as semiconductor silicon and durable plastics for hardware manufacturing—through component assembly by tech innovators, down to software integration and final deployment in hypermarkets and retail pharmacies. Value concentration heavily favors upstream software developers and proprietary robotics manufacturers who control the intellectual property powering automated checkout and warehouse logistics.
Strategic Investment Insights and High-Potential Areas
Our analysis indicates that high-yield investment opportunities within the Retail Automation Market lie at the intersection of artificial intelligence and warehouse robotics. Venture capital and corporate allocators should prioritize scalable cloud-based POS solutions and autonomous mobile robot developers. These segments offer superior margin expansion potential as retailers race to automate sprawling supply chain nodes and reduce labor dependency.
Conclusion and Definitive Industry Takeaways
In summary, the Retail Automation Market is transitioning from an experimental technology phase into a core operational necessity. With market valuation set to reach $64.48 Billion by 2033, enterprises failing to adopt automated warehouse robotics and smart POS solutions risk severe margin compression. Strategic foresight and agile technological integration will define the ultimate market winners over the forecast period.
Research Methodology and Data Triangulation Protocols
Our baseline estimates for the Retail Automation Market are formulated through rigorous data triangulation. We synthesize primary stakeholder interviews with C-level retail executives, comprehensive trade registry data, and secondary macroeconomic indicators. This multi-tiered analytical approach reconciles shipment data from hardware manufacturers with enterprise software adoption metrics to ensure high fidelity across all market sizing forecasts.
Scope of the Report, Coverage Parameters, and Limitations
This research report covers the global Retail Automation Market across key product categories, implementation models, and end-use verticals from 2026 through 2033. Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Limitations include potential macroeconomic disruptions and unforeseen regulatory shifts that could alter projected adoption curves for nascent autonomous retail technologies.
Recent Developments: Strategic Partnerships and Product Launches
Recent milestones in the Retail Automation Market emphasize aggressive product innovation and strategic channel expansion. Industry incumbents have forged key partnerships to integrate cloud-based POS platforms with advanced inventory management systems. Recent product launches focus heavily on enhanced autonomous mobile robots and energy-efficient electronic paper shelf labels, reflecting corporate commitments to sustainability and operational cost reduction.