Market overview of the Retail Oil And Gas Logistics Market
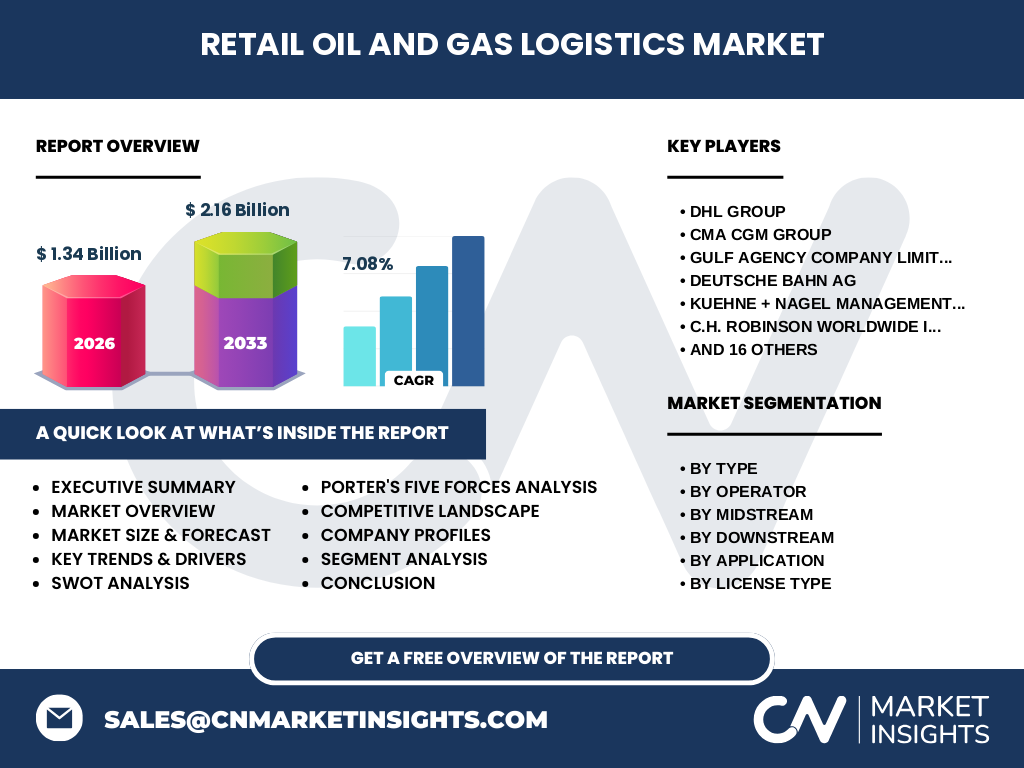
Our analysis indicates that the Retail Oil And Gas Logistics Market governs the complex supply chain movement for refined petroleum and energy commodities. Valued at 1.34 Billion in 2026, this sector encompasses critical midstream and downstream activities, ensuring hazardous products safely reach Company Owned Company Operated and Dealer Owned Dealer Operated retail fuel stations globally through stringent regulatory compliance.
Structural Growth Drivers and Restraints in Retail Oil And Gas Logistics
The market is propelled by surging tanker trucks transportation demands and expanding retail distribution networks. However, growth faces headwinds from volatile crude pricing, stringent environmental mandates enforced by bodies like the EPA, and the logistical friction of managing hazardous railroad transportation assets across constrained geographic corridors.
Emerging Industry Trends in Energy Supply Chains
The shift toward automated asset tracking and digitized terminal management is redefining operational efficiency. Forward-thinking logistics providers are deploying IoT sensors on storage and terminals infrastructure to monitor fuel integrity, reducing transit losses and optimizing inventory flow across complex downstream supply networks.
COVID-19 Impact Analysis and Market Recovery
The pandemic triggered unprecedented demand contraction, severely disrupting refining and marketing operations worldwide. As global mobility rebounded, the recovery trajectory accelerated, pushing the market toward a projected 2.16 Billion valuation by 2033, driven by a surge in commercial fuel consumption and resilient onshore logistics channels.
Competitive Landscape and Market Concentration
The market features a fragmented yet consolidated core of global logistics giants like DHL Group, Kuehne + Nagel Management AG, and CMA CGM Group. These players leverage extensive multimodal networks to dominate high-volume industrial or commercial applications, establishing deep competitive moats through proprietary hazmat handling technologies.
Executive Summary of Key Findings
Our comprehensive research confirms robust expansion in the Retail Oil And Gas Logistics Market, projecting a steady 7.08% CAGR from 2027 to 2033. Strategic investments in midstream infrastructure and optimized company owned dealer operated networks will dictate future market leadership and profitability.
Retail Oil And Gas Logistics Market Forecast (2027 to 2033)
The data suggests sustained upward momentum, scaling the market from 1.34 Billion in 2026 to 2.16 Billion by 2033. This trajectory is underpinned by rising energy consumption in emerging economies and the continuous modernization of downstream distribution and retail petroleum supply chains.
Segmentation Analysis of Energy Logistics Operations
Segmentation spans multiple operational vectors: Midstream (transportation, storage, terminals) and Downstream (refining, distribution, marketing, retail). Operators are split between Private and Public entities, utilizing company owned company operated, dealer owned dealer operated, and company owned dealer operated licensing frameworks.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with North America and Europe leading in asset sophistication, while Asia-Pacific demonstrates the highest volume growth. Regional performance directly correlates with the density of onshore extraction sites and the expansion of urban retail fuel distribution infrastructure.
In-Depth Regional Review of Energy Corridors
Key regional markets face unique logistical hurdles, including stringent European carbon reduction directives and North American pipeline capacity constraints. Logistics providers in these regions must dynamically balance tanker trucks transportation fleets with localized storage and terminal capacities to maintain supply chain continuity.
Company Profiles and Strategic Positioning
Industry leaders such as DB Schenker, Expeditors International, and GEODIS deploy specialized chemical handling divisions. Their strategic positioning focuses on integrated supply chain solutions that seamlessly bridge midstream terminal operations with downstream retail delivery points.
Porter's Five Forces Analysis of the Sector
Bargaining power of buyers remains moderate due to high switching costs for specialized hazmat transport. Threat of new entrants is low, constrained by heavy capital requirements for storage and terminals, strict safety regulations, and established supplier contracts held by incumbents like Agility Public Warehousing Company.
SWOT Analysis of Retail Oil And Gas Logistics
Strengths include robust multimodal networks and proprietary safety protocols. Weaknesses involve high carbon footprints and regulatory vulnerability. Opportunities lie in digital dispatch integration, while threats stem from aggressive shifts toward renewable energy alternatives and recurring geopolitical supply chain shocks.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates at extraction, flowing through midstream transportation and bulk storage and terminals, into downstream refining. Value is finally captured at retail pumps managed via company owned company operated or dealer-operated models serving commercial and retail end-users.
Investment Insights and High-Potential Growth Areas
High-potential investment is concentrated in automated retail terminal infrastructure and green-fleet tanker trucks transportation. Investors should target asset-light logistics providers partnering with established operators like Yusen Logistics Co. Ltd. to capture emerging market share.
Conclusion and Strategic Takeaways
The Retail Oil And Gas Logistics Market offers compelling growth, backed by a projected 7.08% CAGR. Success hinges on technological integration, strict regulatory compliance, and agile management of complex downstream and midstream distribution networks.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining primary executive interviews with global energy logistics providers, secondary macroeconomic indicators, maritime trade registry data, and proprietary volume models to ensure absolute accuracy across all market segments.
Scope of the Report and Coverage Parameters
This report covers global dynamics of the Retail Oil And Gas Logistics Market from 2026 through 2033. Parameters include exhaustive evaluations of midstream, downstream, private, public, onshore, and retail segments, excluding upstream exploration logistics.
Recent Developments and Industry Announcements
Recent strategic moves feature major fleet electrification initiatives by firms like DHL Group and terminal expansion partnerships announced by PSA International Pte Ltd. These developments signal an industry-wide push toward operational decarbonization and enhanced supply chain visibility.