What is the market overview and industry significance of the Mobility Product-Led Growth Playbooks Market?
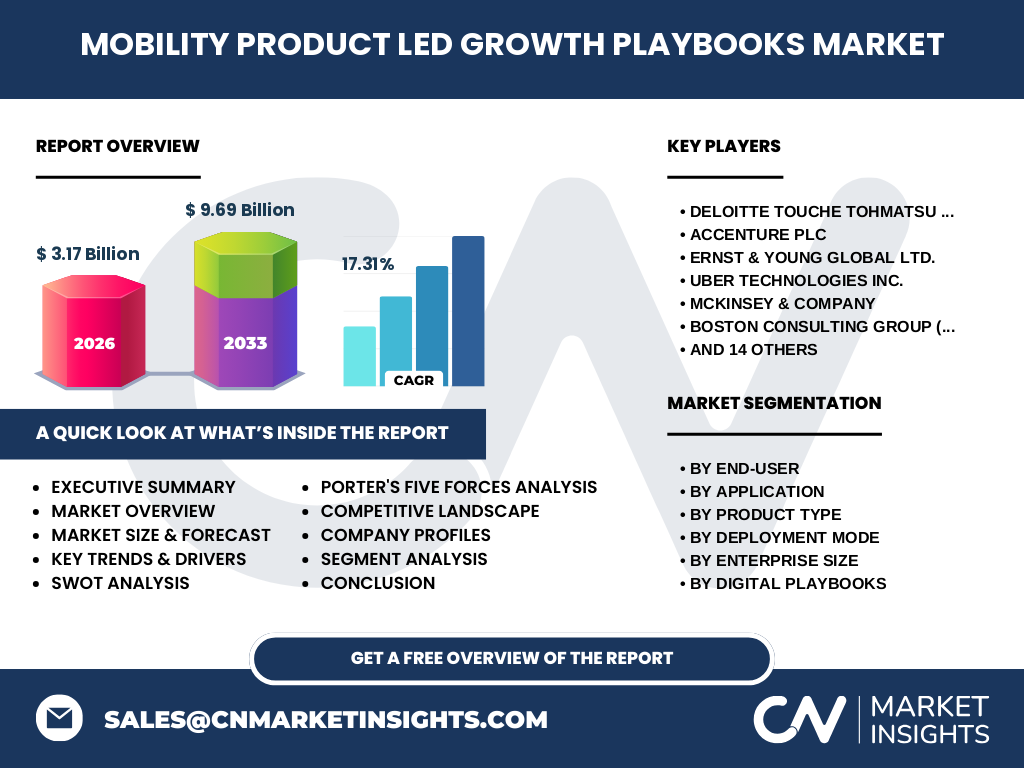
Our analysis indicates that the Mobility Product-Led Growth Playbooks Market reached $3.17 billion in 2026. This specialized sector anchors modern transportation software ecosystems, empowering automotive enterprises and Mobility-As-A-Service providers to drive user acquisition directly through product utility rather than traditional sales funnels.
What are the structural growth drivers, restraints, challenges, and opportunities shaping the market?
The market thrives on accelerated digital adoption, yet faces friction from strict data privacy mandates by regulatory bodies like the European Data Protection Board. Opportunities abound in automated user onboarding for logistics software, allowing innovators to scale rapidly across fragmented urban markets without scaling customer success headcount.
What emerging trends and growth patterns define the sector's evolution?
The shift toward context-sensitive instruction playbooks and behavioural-triggered response frameworks is transforming how mobility apps retain users. Companies are moving away from static guides toward dynamic, event-triggered automation that adapts seamlessly to commuter behavior in dense metropolitan environments.
How did the COVID-19 pandemic impact market dynamics and subsequent recovery trajectories?
Pandemic lockdowns initially disrupted traditional transit models, accelerating an unprecedented pivot toward contactless digital logistics. As urban mobility rebounded, enterprise demand surged for agile digital playbooks that could rapidly retrain remote operators and onboard millions of new delivery drivers overnight.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
Market concentration reflects a mix of management consultancies and product analytics innovators. Firms like Deloitte Touche Tohmatsu Ltd. and McKinsey & Company architect strategic frameworks, while technology specialists like Amplitude Inc. and Pendo provide the underlying instrumentation for interactive adoption workflows.
Executive summary: High-level synthesis of key findings for the Mobility Product-Led Growth Playbooks Market
Driven by compounding software adoption in transportation, the market is poised for exceptional expansion. Strategic investments in cloud-based modular playbooks will separate market leaders from legacy laggards seeking to optimize customer retention across complex multi-modal transit networks.
What is the long-term market forecast and projected growth trajectory from 2027 to 2033?
Based on our research, the market is projected to expand from $9.69 billion by 2033, exhibiting a robust CAGR of 17.31% over the forecast period. This aggressive trajectory is fueled by rising enterprise investments in automated customer success infrastructure.
How is the market structured across end-user, application, product type, deployment, and enterprise size segments?
The ecosystem is segmented by end-user (Automotive, Transportation And Logistics, Mobility-As-A-Service Providers, Technology Companies, Other End-Users), application (User Onboarding, Customer Retention, Feature Adoption, Upselling And Cross-Selling), product type (Digital, Interactive, Automated, Customizable Playbooks), deployment (Cloud-Based, On-Premises), and enterprise size (SMEs, Large Enterprises).
How does geographic distribution influence regional market performance?
Regional performance mirrors local venture capital density and regulatory maturity. North America leads in large-enterprise cloud deployments, while Asia-Pacific exhibits hyper-growth driven by massive scaling of homegrown ride-hailing and super-app ecosystems requiring sophisticated lifecycle automation.
An in-depth regional review of key geographic markets
In North America, high smartphone penetration and mature SaaS ecosystems accelerate adoption among tech companies. Meanwhile, dynamic urban centers across Asia-Pacific present unique logistical hurdles, forcing providers to deploy hyper-localized modular playbooks tailored to diverse regulatory frameworks.
Company profiles and strategic positioning of leading market participants
Industry leaders occupy distinct niches: Uber Technologies Inc., Lyft Inc., and Grab Holdings Inc. utilize internal product-led frameworks, while specialized software vendors like Userpilot Inc. and Slack Technologies LLC supply the infrastructural engagement tools powering modern app retention.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate due to high switching costs once enterprise workflows are embedded. Threat of new entrants remains constrained by the deep domain expertise required to build industry-specific custom playbooks for heavily regulated transport corridors.
SWOT analysis of the Mobility Product-Led Growth Playbooks Market
Key strengths include high recurring revenue potential and seamless software integration. Weaknesses involve initial high setup costs for SMEs. Opportunities lie in emerging autonomous fleet onboarding, while threats stem from tightening global cybersecurity regulations governing user telemetry data.
Value chain analysis from raw software development to end-user deployment
The value chain flows from cloud infrastructure providers and data analytics engines through playbook developers like Figma Inc. and Atlassian Corporation, culminating in integration partners and consultancies such as Accenture plc and Boston Consulting Group (BCG) that implement solutions for transit operators.
What strategic investment insights and high-potential areas emerge from the data?
Investors should target cloud-based, customizable template playbooks targeting mid-market logistics operators. Ernst & Young Global Ltd. and Bain & Company Inc. analyses suggest that integrating behavioral analytics with automated retention workflows yields the highest return on investment.
Conclusion and key strategic takeaways for industry stakeholders
Capturing future upside requires shifting from static documentation to interactive, behavior-triggered walkthroughs. Organizations failing to embrace modular, automated product-led growth strategies risk losing market share to agile platforms optimizing user onboarding in real time.
What research methodology underpins these market estimates and baseline projections?
Our findings are triangulated by combining exhaustive trade registry data, primary qualitative interviews with C-suite executives at Zoom Video Communications Inc. and Dropbox Inc., and secondary macroeconomic indicators tracking enterprise software spending across global transportation hubs.
What is the scope of this research report and its analytical limitations?
This report evaluates the global market across specified deployment models and enterprise sizes through 2033. Excluded from this scope are bespoke, non-commercial proprietary frameworks developed entirely in-house without third-party SaaS tooling or consulting intervention.
Recent developments, product launches, partnerships, and strategic moves shaping the sector
Recent milestones include strategic alliances between tech innovators like Amplitude Inc. and mobility giants like Lime and Gett Co., focused on embedding real-time behavior tracking directly into scooter and ride-share application onboarding flows to drastically reduce user churn.