What is the structural scope of the Pool And Spa Market?
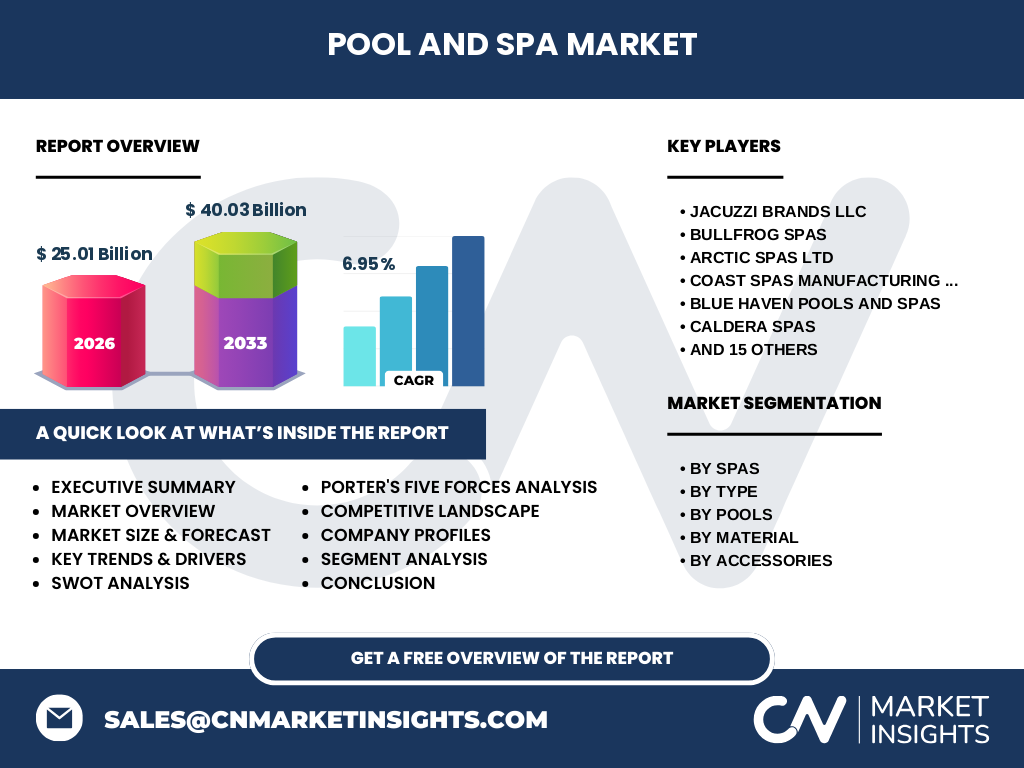
Our research indicates the Pool And Spa Market is valued at 25.01 Billion in 2026. This assessment encompasses residential and commercial installations, spanning raw material sourcing, manufacturing, and advanced filtration logistics governed by strict environmental safety compliance.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising residential remodeling budgets, whereas high raw material costs for stainless steel and fiberglass represent significant logistical hurdles. Regulatory mandates from bodies like the EPA regarding energy-efficient pool pumps heavily shape the operational landscape.
The Shift Toward Smart Hydrotherapy Innovations
Industry trends reveal a rapid consumer migration toward IoT-integrated hot tubs and automated chlorinators. Leading innovators like Jacuzzi Brands LLC and Bullfrog Spas capture market share by embedding remote diagnostic capabilities directly into their portable spa lineups.
Pandemic Aftershocks and Market Recovery
The COVID-19 pandemic catalyzed unprecedented demand for staycation upgrades, artificially accelerating installations. Supply chain bottlenecks for vinyl liners and blowers subsequently tested recovery trajectories, though stabilizing macroeconomic indicators now support a healthy upward correction.
Competitive Benchmarking and Market Concentration
The competitive landscape features aggressive tier-one players like Latham Pool Products and Endless Pools dominating specialized niches. Market concentration remains moderately fragmented, forcing regional manufacturers to leverage proprietary hydrotherapy designs to maintain pricing power against mass-market alternatives.
Executive Summary of the Pool And Spa Market
Our analysis projects the Pool And Spa Market to expand from 25.01 Billion in 2026 to 40.03 Billion by 2033, achieving a robust 6.95% CAGR. Strategic opportunities heavily favor firms investing in energy-efficient heaters and durable composite materials.
Market Forecast Projections (2027 to 2033)
Driven by sustained urbanization and commercial hospitality expansions, the market is poised to scale up to 40.03 Billion by 2033. This trajectory reflects a steady 6.95% CAGR, outperforming historical baseline metrics across key manufacturing hubs.
Comprehensive Segmentation Analysis
The ecosystem is bifurcated by spas and pools, branching into concrete pools, fiberglass pools, and hydrotherapy spas. Essential accessories including filters, pool pumps, and suction fittings dictate aftermarket revenue streams, with plastic and stainless steel serving as foundational structural materials.
Geographic Distribution and Regional Performance
Regional performance varies widely based on climate, zoning laws, and disposable income. North America commands the largest share, bolstered by warm-weather belts, while stringent European building codes influence localized adoption rates for sustainable, energy-efficient filtration systems.
In-Depth Regional Market Review
Regional evaluations highlight suburban sunbelt expansions as primary demand generators. Localized permitting bottlenecks and water conservation regulations in arid zones require manufacturers to adapt by emphasizing low-volume plunge pools and advanced insulated covers.
Strategic Positioning of Leading Companies
Industry stalwarts like Hot Spring Spas, Sundance Spas, and Master Spas differentiate themselves through proprietary Jet engineering and ergonomic shell designs. Meanwhile, builders like Blue Haven Pools And Spas capture regional volume through localized franchise networks and turnkey installation services.
Porter's Five Forces Assessment
Bargaining power of suppliers is moderate due to consolidated fiberglass and resin producers, while competitive rivalry is intense. High switching costs for in-ground concrete construction temper threat of substitutes, though portable spas face fierce retail competition.
SWOT Analysis of the Industry
Strengths include high consumer brand loyalty; weaknesses involve weather-dependent seasonality. Opportunities thrive in smart automation retrofits, whereas threats stem from stringent environmental compliance mandates and fluctuating polymer raw material costs.
Value Chain Analysis and Logistics Flow
The value chain originates with raw material extractors supplying rubber, plastic, and fiberglass to molders. Distributors then route components like chlorinators and blowers to installers, ultimately reaching residential end-users through specialized dealer networks.
Investment Insights and High-Potential Areas
High-potential capital allocation targets energy-saving variable-speed pool pumps and eco-friendly vinyl liners. Investors should prioritize brands with established omnichannel distribution and robust compliance frameworks meeting international safety standards.
Conclusion and Strategic Takeaways
Achieving a 6.95% CAGR through 2033 highlights the sector's resilience. Stakeholders must embrace smart connectivity and sustainable manufacturing to capture surging demand within the 40.03 Billion overarching market valuation.
Research Methodology and Data Triangulation
Baseline estimates are triangulated by synthesizing primary stakeholder interviews with C-suite executives, trade registry import-export logs, and secondary macroeconomic indicators regarding housing starts and discretionary consumer spending indices.
Scope and Methodological Limitations
This report covers global manufacturing, distribution, and retail segments. Limitations include unrecorded custom artisanal builds and fluctuations in localized municipal tax incentives affecting commercial aquatic infrastructure investments.
Recent Industry Developments and Strategic Moves
Recent developments emphasize eco-friendly product launches and cross-border acquisitions. Companies like AquaCal AutoPilot Inc. have unveiled advanced salt-chlorination systems, while major spa builders forge strategic distribution partnerships to bypass ongoing maritime freight bottlenecks.