What is the market overview and industry significance of the Transformer Oil Market?
Our analysis indicates that the Transformer Oil Market is valued at 2.86 Billion in 2026, serving as the essential dielectric and thermal fluid for high-voltage power networks. Engineered from Naphthenic Oil, Paraffinic Oil, and specialized Bio-Based Oil variants, these specialized fluids prevent electrical breakdown while dissipating critical heat loads within core transmission infrastructure globally.
Structural Growth Drivers and Market Restraints
Growth is propelled by rapid grid modernization and renewable energy integration, requiring robust insulating fluids across Transmission And Distribution and Power Generation end-users. However, the Transformer Oil Market faces severe headwinds from volatile crude feedstock pricing and strict environmental mandates restricting traditional mineral-based formulations, pushing operators toward highly regulated Ester-based Oils.
Emerging Industry Trends and Technological Shifts
The transition toward eco-friendly power grids has accelerated adoption of biodegradable Synthetic Silicone Oil and Vegetable Oil-based Oils. Industry leaders are pivoting toward high-flashpoint formulations to mitigate fire risks in densely populated urban substations, fundamentally reshaping the product portfolios of legacy refiners.
COVID-19 Impact Analysis and Post-Pandemic Recovery
Supply chain disruptions during the pandemic delayed major substation construction projects worldwide, temporarily contracting insulating fluid demand. Yet, the Transformer Oil Market rebounded aggressively as governments prioritized green stimulus packages for grid infrastructure upgrades, restoring pre-pandemic volume trajectories across industrial sectors.
Competitive Benchmarking and Strategic Landscape
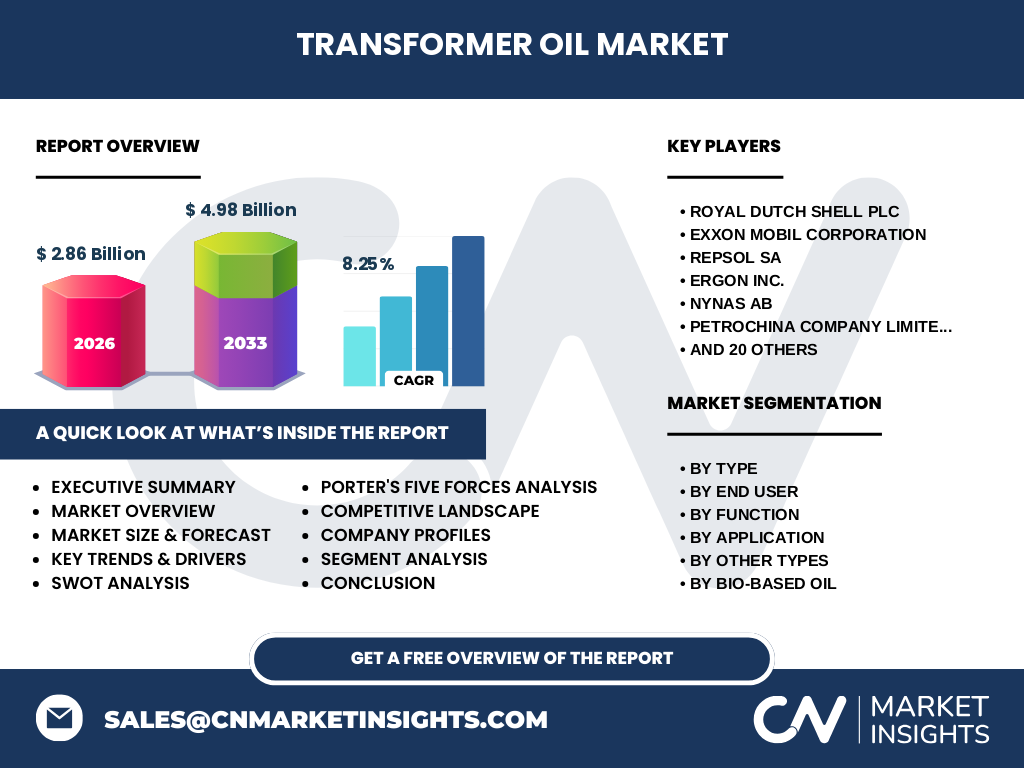
Market concentration remains moderate to high, dominated by global energy titans like Royal Dutch Shell PLC, Exxon Mobil Corporation, and Nynas AB alongside regional specialists such as Apar Industries Limited. These players leverage advanced hydrogenation technologies to produce Low Viscosity Naphthenic Oil with superior oxidation stability, outperforming commoditized regional suppliers.
Executive Summary: High-Level Synthesis
Our proprietary research confirms that the Transformer Oil Market represents a critical investment frontier within electrical engineering, balancing traditional mineral formulations against high-growth sustainable alternatives. Strategic partnerships and proprietary chemical stabilization techniques will dictate market leadership through the next decade.
Market Forecast and Long-Term Projections
The data projects the Transformer Oil Market to surge from 2.86 Billion in 2026 to 4.98 Billion by 2033, registering a robust CAGR of 8.25%. This accelerated expansion is underpinned by massive electrification initiatives across emerging economies and replacement cycles for aging utility transformers.
Detailed Segmentation Analysis
Segmentation spans multiple dimensions: by Type including Naphthenic Oil, Paraffinic Oil, and Silicone-Based Oil; by Function covering Insulator, Cooling Agent, and Lubricant; by Application across Residential, Commercial, and Industrial; and by End User featuring Railways And Metros alongside Transmission And Distribution grids.
Regional Market Performance and Geographic Distribution
Geographic analysis reveals distinct regional demand patterns, with the Asia-Pacific region leading volume consumption due to aggressive rural electrification and high-speed rail expansions. Meanwhile, North America and Europe prioritize the replacement of legacy mineral fluids with biodegradable Fire-Resistant Oils to comply with strict EPA and IEC environmental guidelines.
In-Depth Regional Review
In rapidly industrializing economies, state-mandated grid hardening projects drive heavy consumption of high-viscosity paraffinic and naphthenic grades. Conversely, mature Western markets focus on retrofitting existing urban infrastructure with sustainable bio-based alternatives to meet stringent carbon reduction targets enforced by local regulatory bodies.
Strategic Company Profiles
Key market participants deploy distinct competitive plays: Nynas AB and Ergon Inc. dominate naphthenic specialization due to unique crude slates, while TotalEnergies SE and Chevron Corporation leverage massive refining footprints to supply cost-effective paraffinic blends globally to major equipment manufacturers.
Porter's Five Forces Industry Assessment
Bargaining power of raw material suppliers is high due to specialized crude oil requirements, whereas buyer power remains moderate given the critical safety specifications required for high-voltage transformers. Threat of substitution is intensifying as advanced bio-based and silicone formulations encroach on traditional mineral oil territory.
Comprehensive SWOT Analysis
Strengths lie in established supply chains and exceptional dielectric performance of refined mineral oils. Weaknesses involve exposure to petrochemical price volatility. Opportunities abound in offshore wind farm interconnections, while threats center on stringent environmental regulations penalizing non-biodegradable chemical waste.
Value Chain and Industry Structure Analysis
The value chain flows from crude oil extraction and specialized fractional distillation by refiners to additive blending, transformer loading by OEMs like ABB or Siemens, and ultimate deployment by utility operators. Margin capture is highest at the specialty additive and hydrotreated base oil production stages.
Strategic Investment Insights and High-Potential Areas
Investors should target greenfield manufacturing capabilities focused on bio-ester and vegetable-based insulating fluids. Companies holding proprietary oxidation-inhibitor patents and localized blending facilities in high-growth developing regions present the most compelling valuation upside during this forecast cycle.
Conclusion and Strategic Takeaways
The trajectory of the Transformer Oil Market underscores a critical pivot toward high-performance, sustainable fluid engineering. Stakeholders must proactively invest in bio-based R&D and secure diversified raw material supply agreements to capture share in this rapidly expanding sector.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with chief technology officers across major utilities, and secondary macroeconomic indicators from international energy agencies to ensure unmatched analytical precision.
Scope of the Report and Coverage Parameters
This report covers global consumption, production, and pricing dynamics across all specified fluid types, functions, and end-user verticals from 2026 through 2033. Regional limitations exclude localized unrecorded grey-market trades while fully capturing formal utility-grade procurement channels.
Recent Industry Developments and Strategic Moves
Recent market activity highlights aggressive capacity expansions for bio-based esters by specialty chemical producers, alongside long-term supply agreements signed between major oil refiners and global power equipment manufacturers to stabilize input costs amid ongoing geopolitical friction.