What is the market overview of the Oil Country Tubular Goods (OCTG) Market?
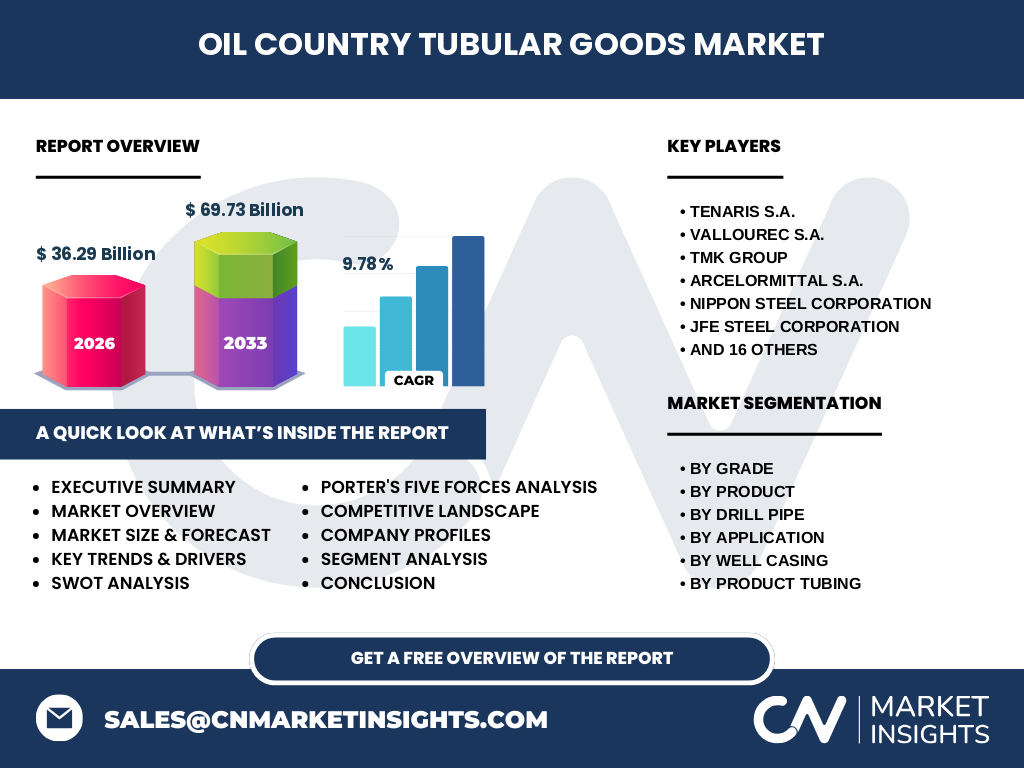
The Oil Country Tubular Goods (OCTG) Market represents a critical industrial backbone for global energy extraction, valued at $36.29 Billion in 2026. Our analysis indicates that this sector encompasses specialized rolled steel products including drill pipes, well casings, and production tubing designed to withstand extreme downhole pressures, corrosive sour gas environments, and deepwater mechanical stresses regulated by API specifications.
Structural Growth Drivers and Market Restraints
The Oil Country Tubular Goods (OCTG) Market industry trends are heavily propelled by a resurgence in complex horizontal drilling and unconventional shale plays. However, growth faces headwinds from stringent EPA environmental mandates and volatile iron ore raw material costs. Market participants must constantly navigate these supply chain bottlenecks to maintain project profitability.
Emerging Trends in the Oil Country Tubular Goods (OCTG) Market
Operators are aggressively pivoting toward proprietary proprietary connection designs and corrosion-resistant alloys to combat aggressive downhole H2S and CO2 environments. Based on our research, this shift favors premium mills capable of delivering ultra-tight dimensional tolerances that prevent catastrophic joint failures during high-pressure hydraulic fracturing operations.
COVID-19 Impact and Recovery Trajectory
The pandemic caused an unprecedented demand shock across the Oil Country Tubular Goods (OCTG) Market market size, as upstream capital expenditures plummeted by over 30%. The recovery trajectory has since been characterized by disciplined capital allocation among exploration and production firms, prioritizing brownfield optimization over speculative wildcat drilling.
Competitive Benchmarking and Strategic Dynamics
Industry consolidation defines the competitive landscape, where global titans like Tenaris S.A., Vallourec S.A., and TMK Group leverage extensive international distribution networks and localized heat-treatment facilities. Market concentration remains high, forcing regional players to carve out defensive niches in specialized non-magnetic drill string configurations.
Executive Summary of the Oil Country Tubular Goods (OCTG) Market
This comprehensive evaluation highlights a robust expansion phase for the Oil Country Tubular Goods (OCTG) Market, driven by deepwater offshore exploration and rigorous well integrity standards. Key findings confirm that technological integration and lightweight alloy development will separate market leaders from commoditized tube manufacturers over the next decade.
Market Forecast and Long-Term Projections
Our proprietary models project the Oil Country Tubular Goods (OCTG) Market to surge from $36.29 Billion in 2026 to reach $69.73 Billion by 2033. This expansion unfolds at a remarkable CAGR of 9.78%, fueled by persistent global energy security demands and the acceleration of complex offshore extraction projects.
Comprehensive Segmentation Analysis
The Oil Country Tubular Goods (OCTG) Market analysis segments the industry by grade into API and Premium grades, by product into Well Casing, Product Tubing, and Drill Pipe, and by manufacturing process into Seamless and Electric Resistance Welded (ERW). Each segment addresses specific mechanical load profiles and geological formations encountered during drilling.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America leading consumption due to extensive Permian Basin shale activity, while offshore developments in the Middle East and Latin America drive substantial premium grade demand. Logistical infrastructure and local steel mill proximity dictate regional market share distribution and pricing power.
In-Depth Regional Review
North America anchors baseline demand through prolific onshore plays, whereas offshore basins in the Gulf of St. Lawrence and South America require advanced corrosion-resistant tubulars. Regional regulatory bodies such as the API impose strict quality audits, raising barriers to entry for non-certified international steel mills.
Company Profiles and Strategic Positioning
Industry heavyweights such as Nippon Steel Corporation, JFE Steel Corporation, and ArcelorMittal S.A. focus heavily on proprietary high-collapse casing designs. Meanwhile, domestic powerhouses like United States Steel Corporation and Jindal SAW Ltd. optimize regional supply chains to hedge against shifting international trade tariffs and logistical friction.
Porter's Five Forces Competitive Assessment
Rivalry within the Oil Country Tubular Goods (OCTG) Market is intense, driven by high fixed production costs of seamless rolling mills. Buyer power remains moderate to high among major E&P conglomerates, while the threat of substitution is mitigated by the unmatched structural integrity of forged steel tubulars in high-pressure wells.
SWOT Analysis of the Industry
Strengths include proprietary thread-sealing technologies and established API manufacturing accreditations. Weaknesses stem from high capital expenditure requirements and exposure to cyclical crude oil price swings. Opportunities lie in geothermal energy wells, while threats involve accelerated capital shifts toward renewable energy sectors.
Value Chain Analysis and Industry Structure
The value chain originates with iron ore and scrap metal extraction, progressing through electric arc furnaces or blast furnaces into billet casting, hot rolling, threading, and heat treatment. Downstream integration by firms like Sandvik AB and Tata Steel ensures quality control from raw metallurgical inputs to final downhole deployment.
Investment Insights and High-Potential Areas
Strategic capital deployment should target manufacturers specializing in high-collapse resistance casing and non-magnetic drill pipes utilized in directional and horizontal steering applications. High-potential areas also include automated threading plants and digital inventory tracking solutions designed to reduce E&P operational downtime.
Conclusion and Strategic Key Takeaways
The Oil Country Tubular Goods (OCTG) Market presents compelling growth vectors underpinned by a robust 9.78% CAGR toward 2033. Long-term success belongs to manufacturers who successfully blend metallurgical innovation with agile, localized supply chain footprints to serve increasingly demanding onshore and offshore operators.
Research Methodology and Data Triangulation
Our baseline estimates are derived through rigorous data triangulation, combining international trade registry customs data, primary stakeholder interviews with procurement directors, and macroeconomic indicators. Secondary research encompasses annual reports, regulatory filings from bodies like the API, and proprietary database regressions to ensure forecast accuracy.
Scope of the Report and Coverage Parameters
This report evaluates the global Oil Country Tubular Goods (OCTG) Market across key dimensions including product type, manufacturing process, grade, and application from 2027 through 2033. Exclusions include downstream refinery piping networks and standard structural steel profiles not certified for oil and gas downhole well operations.
Recent Developments and Strategic Moves
Recent market activities feature aggressive joint ventures and capacity expansions aimed at bolstering low-carbon steel production capabilities. Key industry players including EVRAZ PLC, Baosteel Group Corporation, and Hyundai Steel Company have prioritized digitalized thread inspection systems to meet tightening international quality benchmarks and reduce operational environmental footprints.