Market overview and structural scope of the Corporate Management Services Market
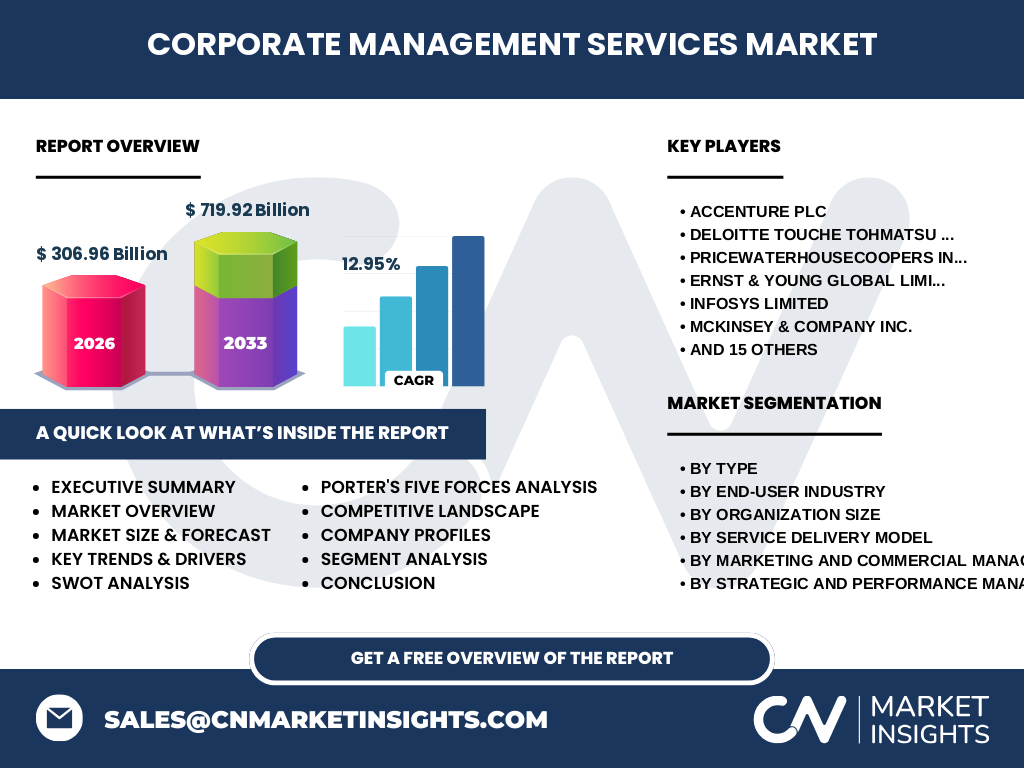
Our analysis indicates that the Corporate Management Services Market is valued at $306.96 Billion in 2026. This sector encompasses critical advisory, operational, and governance solutions designed to optimize enterprise structures, spanning strategic consulting, commercial oversight, supply chain engineering, and regulatory compliance across global jurisdictions.
What are the primary growth drivers and market restraints shaping the industry?
The market is propelled by escalating regulatory complexity enforced by bodies like the SEC and EU directives, alongside surging demand for operational agility. However, integration friction and high deployment costs for legacy enterprises act as notable restraints, forcing firms to balance digital transformation budgets against macroeconomic headwinds.
Emerging trends and transformation patterns across global enterprises
Based on our research, the Corporate Management Services Market industry trends highlight a massive pivot toward cloud-native delivery models and AI-driven analytics. Enterprises increasingly demand specialized consulting for ESG compliance, digital marketing strategies, and agile supply chain re-engineering to navigate geopolitical trade fragmentation.
How did the COVID-19 pandemic reshape operational resilience and market recovery?
The pandemic exposed severe vulnerabilities in global supply chains and workforce deployment, permanently accelerating remote governance frameworks. Our analysis suggests that the recovery trajectory has mainstreamed hybrid service delivery models, driving accelerated demand for third-party business continuity and enterprise risk management services.
Competitive benchmarking and strategic positioning of major industry participants
The competitive landscape features dominant global integrators and specialized advisory firms. Industry titans like Accenture Plc, Deloitte, and PwC leverage proprietary tech stacks and vast global footprints, while specialized players such as Vistra and TMF Group capture high-margin compliance niches.
Executive summary of the Corporate Management Services Market analysis
Our comprehensive Corporate Management Services Market analysis projects the market to surge from $306.96 Billion in 2026 to $719.92 Billion by 2033, expanding at a robust CAGR of 12.95%. This exceptional growth is underpinned by enterprise digitization and heightened governance demands across BFSI and healthcare sectors.
Long-term market forecast and trajectory from 2027 to 2033
The data suggests sustained, aggressive expansion throughout the forecast period, culminating in a market valuation of $719.92 Billion by 2033. This trajectory reflects compounding adoption rates among mid-market enterprises scaling operations internationally while managing stringent cross-border regulatory frameworks.
Segmentation analysis across core service categories and delivery models
The market breaks down by type into Strategic Management, Marketing, Operations, and Governance services. End-users span BFSI, Healthcare, Retail, Manufacturing, and IT, delivered through On-Premise, Cloud-Based, and Hybrid models. Cloud-based governance and specialized supply chain planning represent the highest-velocity micro-segments.
Regional distribution and macroeconomic performance across international markets
Geographic performance is led by North America and Europe, driven by dense corporate headquarters and complex regulatory regimes like GDPR and SOX. Meanwhile, Asia-Pacific exhibits the fastest regional growth rate, propelled by rapid industrialization, expanding manufacturing hubs, and surging domestic consumption in corporate IT.
In-depth regional review of regulatory hurdles and adoption dynamics
North American buyers prioritize digital transformation and advanced analytics integration, whereas European firms focus heavily on sustainability reporting and labor compliance. Emerging APAC markets present unique logistical hurdles, requiring localized corporate advisory partnerships to navigate shifting trade policies and labor laws.
Company profiles and strategic advantages of leading advisory firms
Market leaders utilize distinct competitive moats. McKinsey & Company and Boston Consulting Group dominate high-end strategic transformation, while technology-focused giants like Infosys and HCL Technologies embed digital operations directly into enterprise workflows, merging management consulting with advanced IT execution.
Porter's Five Forces assessment of competitive intensity
Supplier power remains moderate due to specialized talent scarcity, while buyer power is high given the abundance of tier-one consultancies. Threat of substitution is mitigated by the deep domain expertise required for regulatory compliance, though agile digital platforms increasingly challenge traditional consulting engagement models.
SWOT analysis highlighting internal capabilities and macro vulnerabilities
Strengths include deep proprietary methodologies and vast global talent pools; weaknesses involve high billing rates and integration friction. Opportunities lie in emerging AI-driven advisory tools and automated compliance workflows, while threats include economic recession pressures and tightening data privacy regulations globally.
Value chain analysis from foundational advisory input to enterprise execution
The industry value chain flows from raw intellectual capital and proprietary research data to diagnostic consulting, technical implementation, and ongoing managed services. Value capture is shifting away from traditional advisory toward recurring cloud-based operational and compliance monitoring platforms.
Investment insights and high-potential opportunity areas for stakeholders
Investors should target niche providers offering cloud-native governance solutions and automated supply chain optimization. The data indicates that firms integrating AI-powered analytics into their service delivery models will achieve superior margin expansion through 2033.
Conclusion and strategic takeaways for industry stakeholders
Surpassing $719.92 Billion by 2033, the industry rewards adaptability. Organizations must embrace hybrid delivery models and specialized compliance tech. Strategic partnerships and technology acquisitions will separate market leaders from legacy laggards in this rapidly expanding economic landscape.
Research methodology for baseline estimations and data triangulation
Our baseline estimates are rigorously triangulated by combining corporate registry data, extensive primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators from global trade bodies. This multi-layered validation ensures high-fidelity market sizing and growth projections.
Scope of the report, coverage parameters, and analytical limitations
This report covers global corporate management services across four primary service verticals, three organization size tiers, and six end-user industries from 2026 to 2033. Exclusions include informal advisory services and internal corporate restructuring executed entirely without external third-party vendor contracts.
Recent developments, strategic partnerships, and market announcements
Recent industry momentum is defined by aggressive M&A activity and technology partnerships. Firms like KPMG and Ernst & Young have expanded their digital governance portfolios through strategic acquisitions, while Wipro and ZS Associates continue launching proprietary AI suites to automate commercial analytics.