What is the scope and industry significance of the Golf Simulator Market?
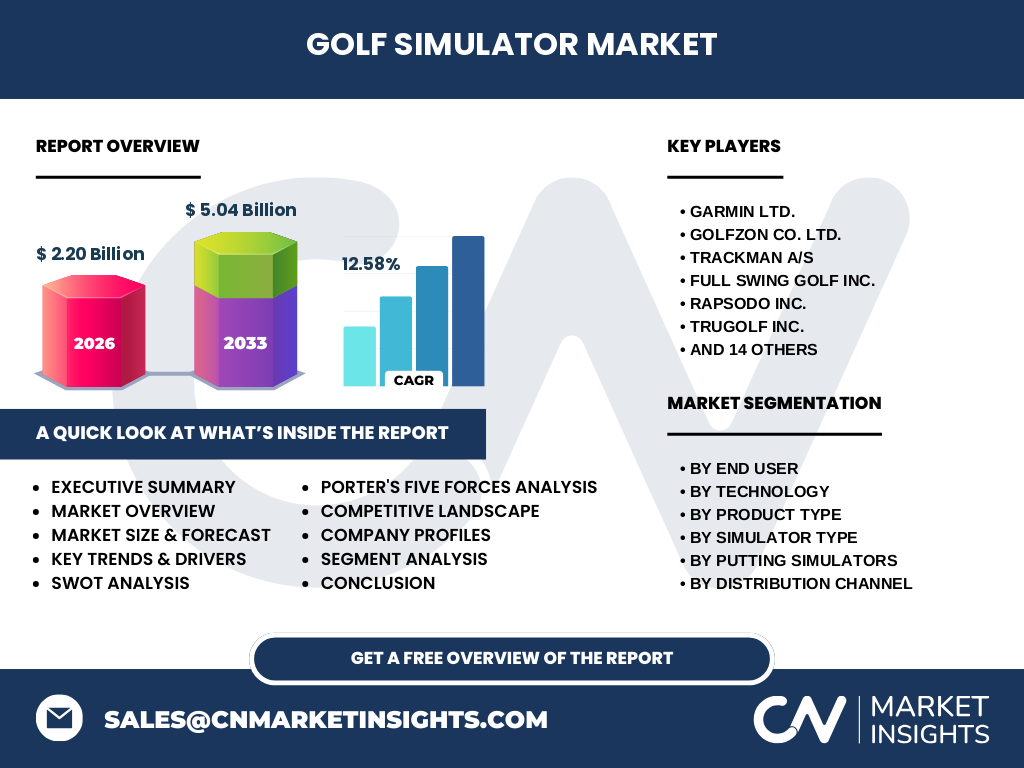
The Golf Simulator Market is valued at 2.20 Billion in 2026, encompassing high-tech hardware, precision optical sensors, and proprietary software. Our analysis indicates this sector is reshaping golf entertainment by bridging physical play with advanced digital analytics.
What are the core market drivers, restraints, challenges, and opportunities?
Growth is accelerated by urban space constraints and a surge in home entertainment investments. However, high initial hardware costs and complex calibration requirements remain notable restraints. Opportunities thrive in integrating cloud-based tracking software with portable consumer units.
Emerging trends and growth patterns shaping the industry
The industry is witnessing a definitive shift toward immersive, cloud-connected multiplayer environments. Camera-Based Technology and high-definition projection systems are replacing legacy radar setups, driven by consumer demand for photorealistic ball-flight analytics in residential spaces.
How did the COVID-19 pandemic impact market trajectory and recovery?
Pandemic-era social distancing forced commercial venues to close temporarily, causing a brief contraction. Conversely, it catalyzed a massive boom in Residential setups as consumers invested heavily in home recreation, accelerating long-term market adoption well past baseline forecasts.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high among specialized innovators like TrackMan A/S, Full Swing Golf Inc., and Golfzon Co. Ltd. Competition centers on proprietary ball-tracking accuracy, software ecosystem lock-in, and aggressive expansion into commercial entertainment franchises.
Executive Summary of Key Findings
Our comprehensive research confirms robust health for the sector, projecting the market to reach 5.04 Billion by 2033. Strategic investments should target camera-based sensors and portable configurations to capture surging consumer demand.
Market Forecast and Trajectory from 2027 to 2033
Driven by robust consumer adoption and commercial entertainment expansion, the market will scale from its 2026 baseline to 5.04 Billion by 2033, expanding at a notable 12.58% CAGR over the forecast timeline.
Segmentation Analysis Across End Users, Technology, and Product Types
The market fragments across End Users (Commercial, Residential, Educational), Technology (Infrared, Camera, Radar, Projection), Product Types (Indoor, Portable, High-Definition), and Simulator Types (Full-Swing, Putting, Optical Sensor), catering to diverse consumer and enterprise training requirements.
Geographic Distribution and Regional Performance Overview
Regional performance mirrors golf participation demographics and disposable income levels. North America retains dominance due to established golf culture, while Asia-Pacific emerges as the fastest-growing region fueled by urban indoor entertainment complexes.
In-Depth Regional Review of Key Markets
North America leads through high residential penetration and commercial venues like X-Golf. Meanwhile, South Korea and Japan exhibit massive demand for commercial screen-golf bays, serving as crucial hubs for Asia-Pacific market expansion.
Strategic Positioning of Leading Industry Companies
Industry leaders differentiate through specialized tech stacks. Garmin Ltd. and Rapsodo Inc. dominate portable consumer segments, whereas TrackMan A/S and Foresight Sports Inc. capture elite coaching and professional fitting markets with precision sensors.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to specialized optical component sourcing. However, buyer power is high given intense retail competition, while the threat of new entrants is mitigated by steep R&D barriers in proprietary ball-flight algorithms.
SWOT Analysis of the Golf Simulator Industry
Key strengths include advanced sensor precision and immersive software graphics. Weaknesses involve high price points. Opportunities lie in educational sports programs, while threats include consumer discretionary spending shifts and economic headwinds.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from rare earth minerals and semiconductor procurement through hardware assembly of cameras and projectors, culminating in software integration by firms like TruGolf E6 Connect LLC and final installation at residential or commercial sites.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize scalable, portable golf simulators and software-as-a-service (SaaS) subscription platforms. These segments offer lower entry barriers and recurring revenue streams compared to capital-intensive commercial full-swing hardware builds.
Conclusion and Strategic Takeaways
The Golf Simulator Market represents a high-growth intersection of sports and digital entertainment. Sustained expansion at a 12.58% CAGR rewards firms that balance high-definition visual fidelity with accessible price points.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data, primary qualitative interviews with C-level executives across leading manufacturers, and secondary macroeconomic indicators tracking leisure spending and real estate trends.
Scope of the Report and Coverage Parameters
This report evaluates global market dynamics from 2026 to 2033. Limitations include fluctuations in global supply chains for optical sensors and regional variations in consumer discretionary income impacting luxury home installations.
Recent Industry Developments, Partnerships, and Product Launches
Recent market momentum features strategic hardware launches by Uneekor Inc. and SkyTrak LLC, alongside cross-industry partnerships integrating gaming engines into simulator software to elevate user engagement and realism.