What is the market overview and scope of the Automotive Wheel Market?
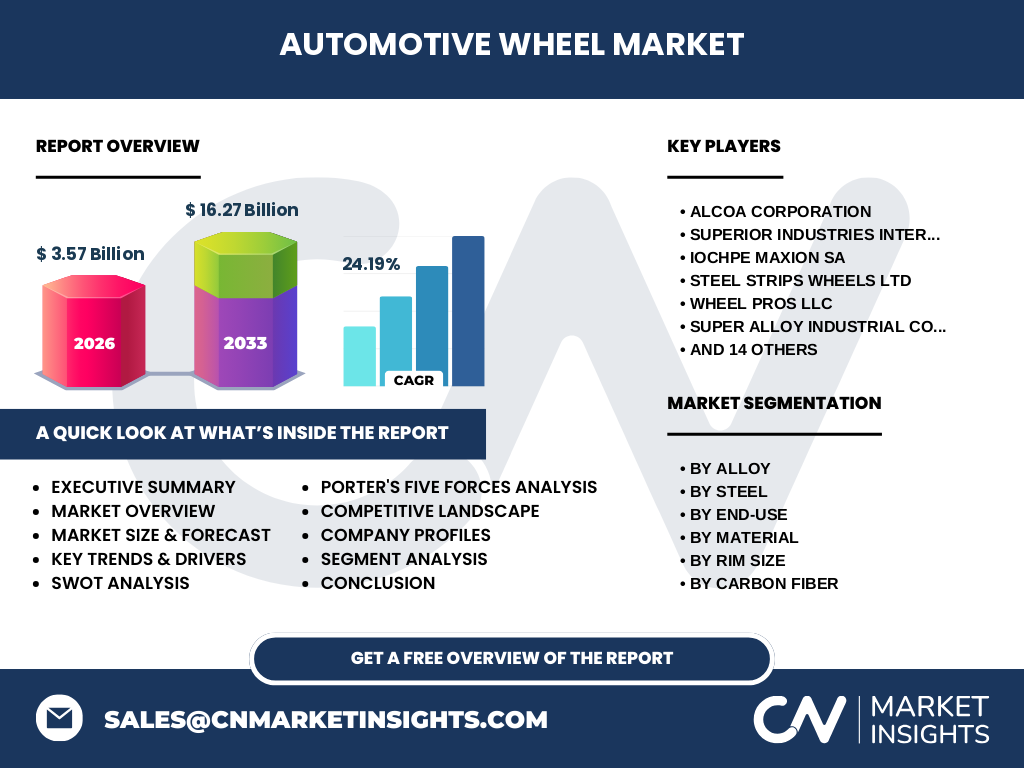
Our analysis indicates the Automotive Wheel Market reached a valuation of 3.57 Billion in 2026, driven by rising vehicle production. This sector encompasses steel, alloy, and carbon fiber configurations serving global OE and aftermarket channels, regulated by stringent standards from organizations like the Society of Automotive Engineers (SAE).
Structural Growth Drivers and Restraints
The primary catalyst is consumer demand for lightweight vehicle components to improve fuel economy. Conversely, volatile raw material costs for aluminum and steel pose significant restraints. Industry leaders like Alcoa Corporation and Superior Industries International Inc navigate these headwinds through advanced metallurgical engineering and supply chain resilience.
The Shift Toward Lightweight Materials
Industry trends reveal a rapid pivot from standard steel rims to cast alloy wheels and forged options. This transition reduces unsprung mass, directly enhancing vehicle handling. Manufacturers such as Enkei Corporation and BBS Kraftfahrzeuge GmbH are capitalizing on this shift through proprietary casting technologies.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains and port logistics across major trade hubs. However, the Automotive Wheel Market industry trends show a robust V-shaped recovery, bolstered by aggressive digital transformation and localized sourcing strategies adopted by firms like IOCHPE Maxion SA.
Competitive Benchmarking
The market exhibits a moderately consolidated landscape where tier-one suppliers dominate OEM contracts. Strategic agility defines leaders like Ronal Group and Accuride Corporation, which leverage localized manufacturing near major automotive assembly plants in North America, Europe, and Asia to mitigate freight costs.
Executive Summary of the Automotive Wheel Market
Our comprehensive Automotive Wheel Market analysis highlights a monumental expansion from 2027 to 2033. The convergence of strict carbon emission mandates and luxury vehicle adoption makes this sector a prime target for strategic investments, particularly in advanced alloy and carbon fiber manufacturing.
Long-Term Market Forecast (2027 to 2033)
The data projects the Automotive Wheel Market market size to surge to 16.27 Billion by 2033, expanding at a remarkable CAGR of 24.19%. This explosive trajectory is fueled by electric vehicle adoption requiring specialized, high-load capacity wheel assemblies.
Segmentation Analysis Across Key Categories
Market segmentation spans multiple dimensions: by alloy (Cast Alloy Wheels, Forged Alloy Wheels, Multi-piece), by steel (Standard, Spoke, Rims), by material (Steel, Alloy, Carbon Fiber), by rim size (13"-15" up to Above 21"), by vehicle type (Passenger, Light and Heavy Commercial), and by vehicle class (Economy, Mid-Priced, Luxury-Priced).
Regional Market Distribution and Performance
Geographic performance varies significantly, with Asia-Pacific leading volume production due to extensive manufacturing hubs in China and India. Meanwhile, North America and Europe drive demand for premium luxury-priced and lightweight forged wheels, complying with stringent regional environmental regulations.
In-Depth Regional Review
Regional analysis underscores Asia-Pacific as the primary growth engine, supported by high domestic vehicle sales. Simultaneously, European markets prioritize advanced sustainability metrics, forcing suppliers like BORBET GmbH to implement closed-loop aluminum recycling programs within their manufacturing facilities.
Strategic Positioning of Leading Companies
Key market participants deploy distinct differentiation strategies. Steel Strips Wheels Ltd focuses on high-volume steel solutions, while Super Alloy Industrial Co Ltd and OZ Group capture high-margin segments through bespoke forged and motorsport-derived wheel designs tailored for luxury applications.
Porter's Five Forces Analysis
Supplier power remains moderate due to fluctuating aluminum ingot prices, while buyer power is high given the consolidation among global automotive OEMs. Threat of substitutes is mitigated by rigorous homologation standards enforced by regulatory bodies like the Econol and international safety agencies.
SWOT Analysis of the Industry
Strengths include advanced manufacturing automation and lightweight material expertise. Weaknesses involve high capital expenditure for precision forging machinery. Opportunities lie in electric vehicle OE contracts, while threats stem from geopolitical trade tariffs impacting bauxite and raw aluminum imports.
Value Chain Analysis
The value chain initiates with bauxite mining and primary metal smelting, progressing to precision foundry casting, CNC machining, and finishing. Finished products flow through OE assembly lines or aftermarket distributors like Wheel Pros LLC, ensuring end-user availability globally.
Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in single-piece carbon fiber wheels and lightweight magnesium wheels. These high-performance segments offer superior margin potential as electric vehicle manufacturers seek maximum range extension through extreme weight reduction.
Conclusion and Key Takeaways
The Automotive Wheel Market represents a high-growth sector set to reach 16.27 Billion by 2033. Success hinges on technological innovation in lightweight alloys, strategic regional expansion, and robust alignment with electric vehicle manufacturing trends.
Research Methodology
Our baseline estimates are triangulated using a rigorous mix of trade registry data, primary stakeholder interviews with C-suite executives from Topy Industries Limited and CLN Group, and secondary macroeconomic indicators gathered from international automotive trade associations.
Scope of the Report
This report covers global deployment parameters across passenger and commercial vehicle classes from 2027 to 2033. Limitations include localized currency fluctuations and unpredicted geopolitical trade policy shifts that could temporarily alter raw material procurement costs.
Recent Industry Developments and Strategic Moves
Recent market activities feature aggressive joint ventures and facility expansions. For instance, companies like Zhejiang Wanfeng Auto Wheel Co Ltd and Foshan Nanhai Zhongnan Aluminum Wheel Co Ltd have scaled up automated production lines to supply lightweight alloy solutions to multinational electric vehicle startups.