What is the scope and industry significance of the Drill Pipe Market?
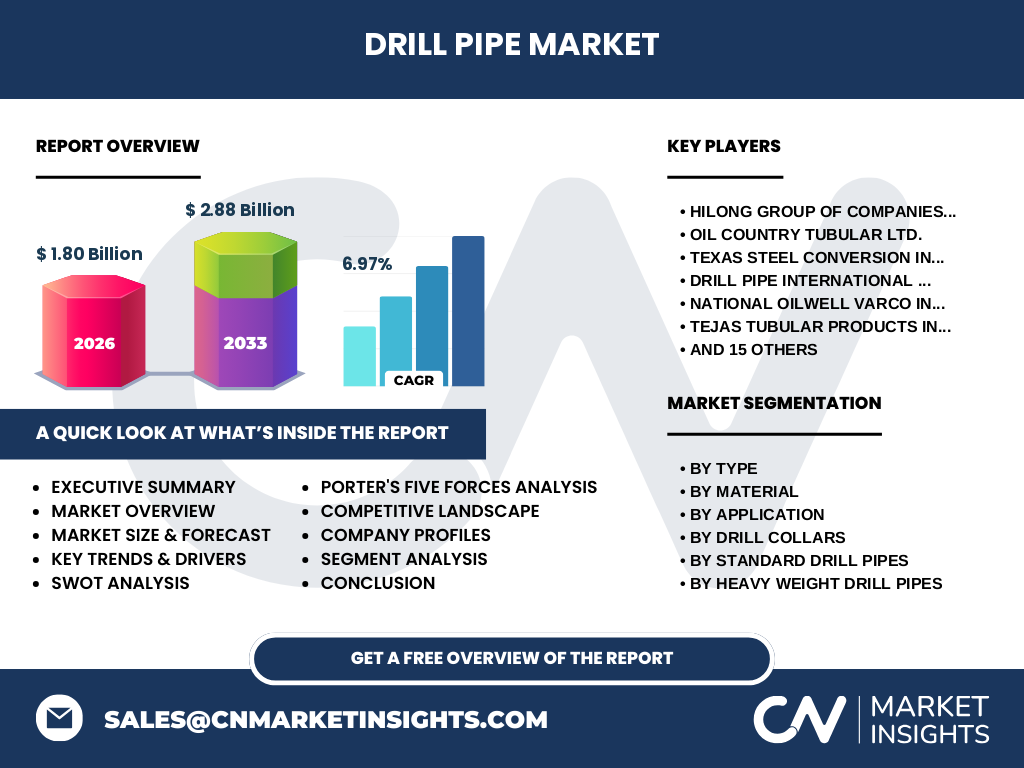
Our analysis indicates that the Drill Pipe Market reached a valuation of 1.80 Billion by 2026, serving as the foundational backbone for global oil, gas, and geothermal drilling operations. This sector encompasses critical tubular goods designed to transmit rotational torque and drilling fluid downhole under extreme mechanical stress and corrosive environments.
Key market drivers, restraints, challenges, and opportunities shaping Drill Pipe Market
Growth is propelled by rising offshore exploration and complex unconventional plays demanding high-strength Alloys and Composites. Conversely, stringent API regulatory compliance, volatile raw material costs, and logistical hurdles in remote basins act as primary restraints. Significant opportunities lie in deepwater drilling innovations spearheaded by leaders like Tenaris S.A. and Vallourec SA.
Emerging trends and growth patterns in Drill Pipe Market
The sector is witnessing a definitive shift toward proprietary sour-service connections and non-magnetic grades to support complex directional drilling trajectories. Based on our research, operators increasingly prioritize premium fatigue-resistant strings, favoring advanced manufacturing techniques adopted by National Oilwell Varco Inc. and TMK Steel Limited to minimize catastrophic downhole failures.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and a sharp contraction in rig counts globally, temporarily stalling procurement cycles. However, the subsequent post-pandemic recovery trajectory has been robust, driven by energy security imperatives and aggressive upstream capital redeployments into high-yield shale and offshore assets.
Competitive benchmarking and strategic dynamics
The competitive landscape features high market concentration among established multinational tubular giants and specialized regional manufacturers. Market leaders leverage backward integration and extensive global distribution networks—spanning key ports in Houston, Rotterdam, and Singapore—to outmaneuver competitors, with prominent players like Hilong Group of Companies Ltd. and Hunting PLC securing vital supply contracts.
Executive summary of the Drill Pipe Market
Our proprietary research confirms that the Drill Pipe Market size is projected to expand from 1.80 Billion in 2026 to 2.88 Billion by 2033, registering a solid CAGR of 6.97%. This expansion is underpinned by technological advancements in metallurgy and sustained global demand for hydrocarbon extraction.
Market forecast from 2027 to 2033
The data suggests steady, compounding expansion, lifting the global market from its 2026 baseline to 2.88 Billion by 2033 at a 6.97% CAGR. This trajectory reflects sustained long-term commitments to deepwater and ultra-deepwater projects requiring specialized drill string configurations.
Segmentation analysis by type, material, and application
The market is segmented by type into Standard Drill Pipes (API and Premium), Heavy Weight Drill Pipes (Conventional and Enhanced), and Drill Collars (Steel and Non-Magnetic). Material categories comprise Alloys, Composites, and Other Materials, deployed across Offshore and Onshore applications.
Geographic distribution and regional performance
Regional performance varies significantly, dictated by local regulatory frameworks such as EPA mandates in North America and offshore licensing rounds in the North Sea and Asia-Pacific. North America remains a dominant revenue generator, while the Middle East and Latin America display high growth potential driven by offshore mega-projects.
In-depth regional review of key markets
North America benefits from mature shale plays requiring continuous replacement of high-wear drill strings. Meanwhile, the Asia-Pacific region, anchored by key manufacturing hubs in China and Japan involving firms like Shandong Molong Petroleum Machinery Co. Ltd. and JFE Steel Corporation, dominates export volumes for standard and heavy-weight variants.
Strategic positioning of leading companies
Industry leaders differentiate through proprietary metallurgical treatments and stringent quality control. Companies such as Oil Country Tubular Ltd., Tejas Tubular Products Inc., and DP-Master Manufacturing Ltd focus on high-torque connections, while specialized firms like Drill Pipe International LLC cater to niche rental and inspection markets.
Porter's Five Forces analysis
Bargaining power of buyers is moderate to high due to standardized API specifications, yet mitigated by the specialized nature of premium sour-service alloys. Threat of substitutes remains low, as no viable alternative currently matches the mechanical load-bearing capacity of steel and composite drill strings in subterranean rotary drilling.
SWOT analysis of the Drill Pipe Market
Key strengths include advanced proprietary metallurgy and established global logistics networks. Weaknesses involve high sensitivity to upstream capital expenditure cycles. Opportunities emerge from digitalization and IoT-enabled smart drill pipe telemetry, whereas threats include volatile raw material tariffs and stringent environmental regulations.
Value chain analysis from raw materials to end-users
The value chain initiates with high-grade iron ore and alloy suppliers, progressing through seamless pipe extrusion, upset forging, friction welding of tool joints, and heat treatment. Finished products flow through global distribution networks to E&P operators and drilling contractors navigating complex onshore and offshore environments.
Investment insights and high-potential areas
Investors should target manufacturers specializing in corrosion-resistant alloys and composite-hybrid drill strings designed for extreme high-pressure, high-temperature (HPHT) wells. Strategic partnerships with regional service providers offer robust entry barriers against commoditized manufacturing competition.
Conclusion and key takeaways
The Drill Pipe Market industry trends highlight an industry transitioning toward higher technological sophistication and durability. Achieving a forecasted valuation of 2.88 Billion by 2033 at a 6.97% CAGR, the sector rewards innovation in metallurgy, corrosion resistance, and sustainable manufacturing practices.
Research methodology for baseline estimations
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with C-suite executives across major pipe mills, and secondary macroeconomic indicators from agencies like the EIA and IEA to ensure absolute market data integrity.
Scope of the report and coverage parameters
This comprehensive report evaluates the global market from 2026 to 2033, analyzing volumetric demand and revenue generation across defined product segments, material classifications, and geographic territories, while explicitly accounting for macroeconomic trade policies and regional drilling rig activity metrics.
Recent developments, partnerships, and strategic moves
Recent market activity features strategic capacity expansions and joint ventures focused on lowering carbon footprints in steel production. Notable moves by firms like EVRAZ North America and Jiangyin Long Bright Drill Pipe Manufacture Co. Ltd. emphasize localized supply chain resilience and enhanced digital asset tracking for drill string fleets.