Executive Summary of the Molybdenum Market
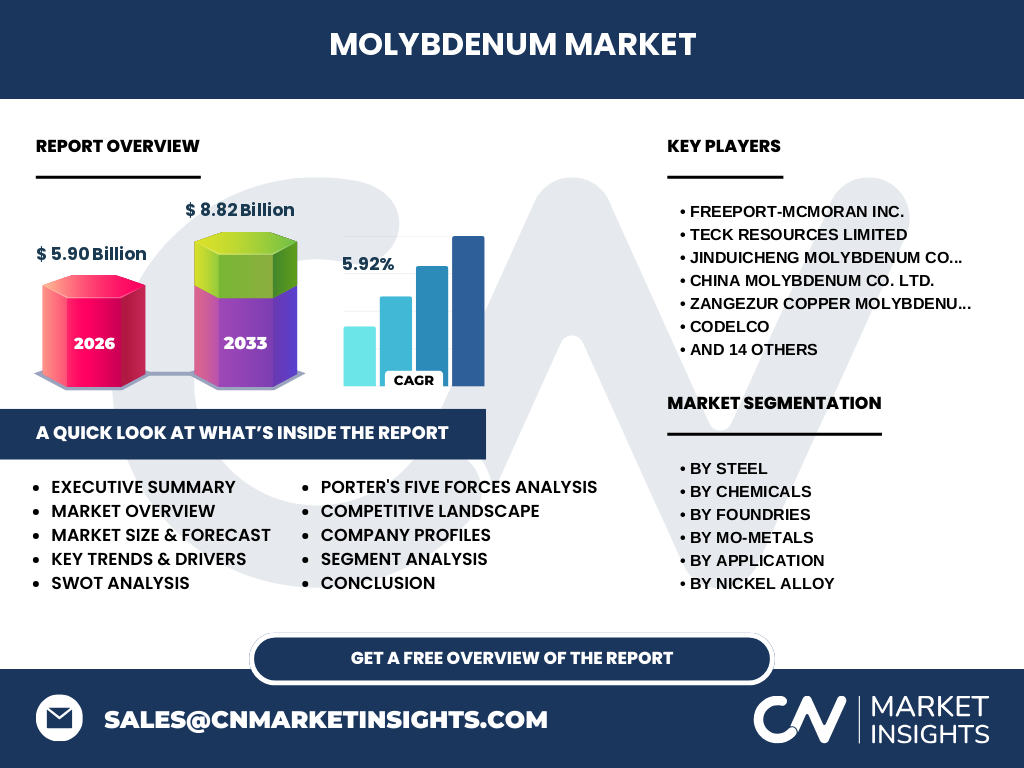
Our analysis indicates that the global Molybdenum Market is valued at 5.90 Billion in 2026 and is projected to expand significantly to reach 8.82 Billion by 2033, driven by a robust CAGR of 5.92%. This proprietary overview synthesizes critical data across raw material extraction, chemical processing, and end-user deployment.
Market Overview and Industry Significance of the Molybdenum Market
The Molybdenum Market occupies a foundational role in global metallurgy, supplying critical refractory metallic elements essential for high-strength steel alloys. Industry significance stems from molybdenum's unique ability to enhance hardenability, creep resistance, and corrosion inhibition in harsh chemical and aerospace operating environments.
Key Market Drivers, Restraints, Challenges, and Opportunities in the Molybdenum Market
Growth is heavily propelled by escalating infrastructure investments in emerging economies and stringent pipeline safety standards in the oil and gas sector. Conversely, volatile mining ore grades and strict environmental compliance mandates from bodies like the EPA pose operational hurdles, while creating opportunities for advanced hydrometallurgical recycling.
Structural Growth Trends and Emerging Patterns
The shift toward advanced high-strength low-alloy (HSLA) steels in automotive manufacturing is accelerating demand for specialized molybdenum grades. Furthermore, rising adoption of renewable energy infrastructure requires heavy-gauge structural plates fortified with molybdenum to withstand extreme offshore wind and geothermal conditions.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
Pandemic-induced supply chain bottlenecks and temporary automotive assembly shutdowns caused severe disruptions across major molybdenum mining hubs. However, the subsequent recovery trajectory has outpaced baseline projections, fueled by government-backed stimulus packages targeting green energy grid modernizations and heavy industrial capital expenditures.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features dominant mining conglomerates such as Freeport-McMoRan Inc., Teck Resources Limited, and China Molybdenum Co. Ltd., which control primary output through massive open-pit copper-molybdenum operations. Strategic dynamics focus on securing low-cost primary assets, optimizing by-product recovery, and forging direct long-term supply agreements with specialty alloy manufacturers.
Molybdenum Market Growth Forecast (2027 to 2033)
Our forecasting models demonstrate steady upward momentum, taking the market from its 2026 baseline to the 2033 valuation of 8.82 Billion at a 5.92% CAGR. This expansion is sustained by accelerating electrification trends and sustained demand for specialized nickel alloys across chemical processing plants.
Segmentation Analysis of Product Types and Applications
Segmentation is categorized by product types including steel, chemicals, foundries, and mo-metals, alongside end-user demands spanning aerospace, electronics, and oil and gas. Molybdenum Trioxide (MoO₃) and ammonium molybdate dominate the chemical segment, while stainless and alloy steel remain the largest volumetric consumers.
Geographic Distribution and Regional Market Performance
Regional performance is anchored by Asia-Pacific, driven by extensive stainless steel production in China and specialized industrial usage in South Korea and Japan. Meanwhile, North America and Latin America maintain strong foundational shares through major extraction sites managed by industry leaders like Codelco and Southern Copper equivalents.
In-Depth Regional Review and Localized Constraints
Latin American operations face ongoing water scarcity challenges and strict local permitting constraints, directly impacting daily ore processing throughput. In contrast, European markets contend with stringent REACH chemical regulations, pushing regional processors to prioritize closed-loop recycling and high-purity molybdenum disulphide formulations.
Strategic Positioning of Leading Companies
Key market participants leverage distinct operational strategies to defend their market share. Major primary producers like Jinduicheng Molybdenum Co. Ltd. and Zangezur Copper Molybdenum Combine focus on large-scale output efficiency, whereas specialty processors concentrate on high-purity molybdenum rods, sheets, and electronic-grade powders.
Porter's Five Forces Analysis of the Molybdenum Sector
Bargaining power of suppliers remains moderate due to the consolidated nature of primary mining operations, while buyer power is tempered by the specialized technical specifications required for aerospace and defense applications. Threat of substitution is low given molybdenum's irreplaceable high-temperature mechanical properties.
SWOT Analysis of the Molybdenum Market Ecosystem
Strengths include exceptional thermal stability and alloy strengthening capabilities. Weaknesses involve high energy intensity during roasting and conversion processes. Opportunities lie in expanding catalyst applications for green hydrogen production, while threats encompass geopolitical trade tariffs and substitution risks in lower-tier carbon steels.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with mining and beneficiation of molybdenite ore, proceeding through roasters that convert concentrates into technical-grade molybdenum trioxide. Subsequent processing yields ferro-molybdenum and pure metal forms utilized by end-users in automotive, chemical, and structural engineering applications.
Investment Insights and High-Potential Areas
Strategic investors should focus on hydrometallurgical recycling facilities and high-purity powder production lines tailored for the electronics and medical sectors. Companies investing in low-carbon roasting technologies will capture premium margins amid tightening global environmental regulations.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Molybdenum Market presents highly lucrative growth avenues, anchored by a projected valuation of 8.82 Billion by 2033. Stakeholders must navigate complex supply chains and environmental pressures by investing in advanced processing technologies and securing reliable primary mining partnerships.
Research Methodology and Baseline Triangulation
Our market sizing relies on exhaustive data triangulation combining official customs trade registries, primary stakeholder interviews with mining executives, and secondary macroeconomic indicators. Baseline estimates for 2026 are cross-referenced with quarterly financial reports from major publicly traded producers.
Scope of the Report and Coverage Parameters
This report covers global demand trends, regional performance metrics, and detailed product segmentation from 2027 through 2033. Limitations include inherent fluctuations in spot market pricing and confidential proprietary output data from state-owned enterprises in select non-disclosure jurisdictions.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum highlights strategic joint ventures aimed at optimizing by-product recovery and lowering carbon emissions during roasting. Leading firms have ramped up capital expenditures for high-purity molybdenum wire and sheet production facilities to satisfy surging requirements in semiconductor manufacturing.