What is the market overview and industry significance of the Wholesale Electronic Markets And Agents And Brokers Market?
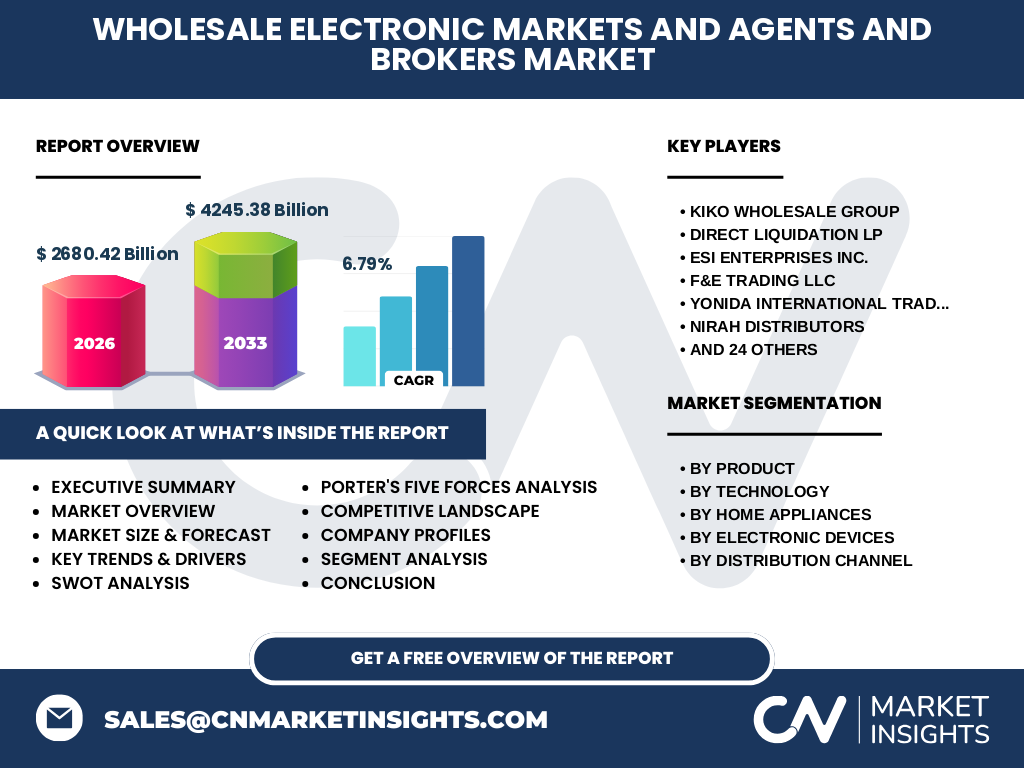
Our analysis indicates that the Wholesale Electronic Markets And Agents And Brokers Market represents a foundational pillar of global commerce, valued at $2,680.42 Billion in 2026. This sector orchestrates the complex B2B distribution of electronic devices, home appliances, and advanced components through intermediaries, agents, and specialized digital platforms. By bridging semiconductor foundries, major original equipment manufacturers, and downstream commercial buyers, this market ensures supply chain resilience across high-tech industries globally.
What are the key market drivers, restraints, challenges, and opportunities shaping the Wholesale Electronic Markets And Agents And Brokers Market?
The market is propelled by exponential enterprise demand for computers and accessories and mobile phones and accessories, alongside surging integration of Artificial Intelligence across brokerage workflows. However, persistent supply chain bottlenecks and strict international trade compliance regarding rare-earth materials act as primary restraints. Strategic opportunities abound for forward-thinking distributors leveraging automated inventory management to capture untapped B2B ecommerce demand.
What are the emerging trends and growth patterns in the Wholesale Electronic Markets And Agents And Brokers Market?
Industry trends highlight a decisive shift toward omnichannel B2B portals and the deployment of Near Field Communication (NFC) and Generation PCL Technology within logistics tracking. Enterprises are rapidly adopting automated procurement ecosystems, moving away from legacy transactional brokering toward data-driven vendor-managed inventory agreements that guarantee rapid fulfillment for high-turnover consumer electronics.
How did the COVID-19 pandemic impact the Wholesale Electronic Markets And Agents And Brokers Market and what is the recovery trajectory?
The pandemic caused severe supply chain fractures and component shortages across audio and video equipment and gaming consoles and accessories supply chains. Yet, this crisis catalyzed long-overdue digital transformation. The recovery trajectory is characterized by aggressive diversification of sourcing channels, accelerated migration toward cloud-enabled brokerage networks, and robust post-pandemic demand stabilization.
What defines the competitive landscape, major players, market concentration, and strategic dynamics of this sector?
The competitive ecosystem features a mix of multinational broadline distributors and specialized brokers. Industry leaders such as Arrow Electronics Inc. and Avnet Inc. dominate semiconductor distribution, while giants like Ingram Micro Inc. and Tech Data Corporation command IT hardware channels. Strategic dynamics center on mergers, proprietary supply chain analytics, and value-added technical support services.
Executive Summary: High-level synthesis of key findings about the Wholesale Electronic Markets And Agents And Brokers Market
This comprehensive research reveals a robust macroeconomic expansion, forecasting the market to scale from $2,680.42 Billion in 2026 to $4,245.38 Billion by 2033 at a CAGR of 6.79%. Growth is anchored by surging corporate spending on smart home infrastructure, enterprise mobility, and digital transformation initiatives that require seamless intermediary logistics.
What is the projected market forecast for the Wholesale Electronic Markets And Agents And Brokers Market from 2027 to 2033?
Based on our research, the market will achieve remarkable expansion, advancing from $2,680.42 Billion in 2026 to reach $4,245.38 Billion by the end of 2033. This growth reflects a steady compound annual growth rate (CAGR) of 6.79%, driven by rising disposable incomes, rapid commercialization of 5G infrastructure, and automated B2B transaction platforms.
How is the market structured across its primary segmentation categories?
The market segmentation spans distinct operational categories designed to capture nuanced commercial demand: By Product: Electronic Devices and Home Appliances. By Technology: Near Field Communication (NFC), Magnetic Secure Transmission (MST), Artificial Intelligence, Virtual Reality Technology, Generation PCL Technology, and Other Technologies. By Home Appliances: Major Appliances, Small Appliances, HVAC Equipment, and Kitchen Appliances. By Electronic Devices: Computers And Accessories, Mobile Phones And Accessories, Audio And Video Equipment, Cameras And Photography Equipment, and Gaming Consoles And Accessories. By Distribution Channel: Online and Offline.
What are the geographic distribution and performance trends across regional markets?
Geographic performance highlights North America and Asia-Pacific as the undisputed commercial engines of the sector, supported by advanced manufacturing hubs and dense consumer electronics adoption. European markets exhibit steady, regulation-driven growth focused on energy-efficient HVAC Equipment and sustainable electronics sourcing, whereas Latin America and the Middle East demonstrate high-growth potential driven by expanding digital infrastructure.
Provide an in-depth regional review of key markets within the global distribution ecosystem.
North America maintains leadership due to early enterprise adoption of AI-driven supply chain platforms and massive data center investments boosting demand for enterprise hardware. Meanwhile, Asia-Pacific remains the primary manufacturing and consumption nexus, propelled by massive component assembly operations in Greater China, South Korea, and Southeast Asia that rely heavily on specialized broker networks.
How are leading companies strategically positioned within the Wholesale Electronic Markets And Agents And Brokers Market?
Market participants deploy distinct competitive strategies to capture share. Firms like Future Electronics Inc. and D&H Distributing Co. focus on deep technical inventory specialization, whereas specialized liquidators like Direct Liquidation LP and goTRG optimize reverse logistics and excess inventory monetization. Broadline players like Synnex Corporation scale through extensive value-added service portfolios.
Porter's Five Forces analysis of the Wholesale Electronic Markets And Agents And Brokers Market
Our analysis of competitive forces indicates moderate-to-high bargaining power of buyers due to numerous alternative brokers, offset by high switching costs for integrated enterprise IT platforms. Supplier power remains moderate, governed by major component manufacturers. Threat of substitutes is low given the specialized logistics required, while industry rivalry is fierce among established distributors.
SWOT Analysis: Internal strengths, weaknesses, opportunities, and threats
Key strengths include established global warehousing networks and robust manufacturer relationships. Weaknesses involve vulnerability to semiconductor cyclicality and low operating margins. Opportunities lie in expanding B2B e-commerce penetration and Artificial Intelligence integration. Threats include geopolitical trade tensions, tariff escalations, and cybersecurity risks targeting digital brokerage platforms.
Value Chain Analysis: Industry structure and value flow from raw materials to end-users
The industry value chain initiates with upstream raw material suppliers and silicon foundries, flowing through component manufacturers and original equipment manufacturers. Wholesale electronic markets, agents, and brokers then step in to manage intermediate distribution, bulk aggregation, regulatory compliance, and localized logistics before products reach retail channels, enterprise end-users, and specialized e-commerce platforms.
What investment insights and strategic recommendations emerge from this research?
Investors should target technology-enabled distributors and brokers specializing in Artificial Intelligence hardware components and sustainable HVAC Equipment distribution. High-potential areas include automated B2B procurement platforms, reverse logistics providers like goTRG, and specialized regional operators capable of navigating complex cross-border trade regulations and localized supply chain constraints.
Conclusion and key takeaways for executive stakeholders
The Wholesale Electronic Markets And Agents And Brokers Market offers exceptional investment and operational potential, scaling confidently toward $4,245.38 Billion by 2033. Success in this evolving ecosystem requires disciplined inventory management, adoption of automated digital sales channels, and strategic alignment with high-growth technology sectors like mobile communications and enterprise computing.
Research methodology: How are baseline estimates triangulated across industry sources?
Our research methodology combines exhaustive triangulation of primary stakeholder interviews—including C-suite executives from ScanSource Inc. and Almo Corporation—with secondary macroeconomic indicators, national trade registry statistics, customs import-export data, and proprietary econometric modeling to ensure uncompromised data accuracy and market intelligence integrity.
What is the scope of the report and what parameters govern its market coverage?
This report encompasses a comprehensive global assessment of the wholesale electronic markets, agents, and brokers sector, analyzing market revenues from 2026 through the forecast horizon to 2033. Coverage parameters rigorously evaluate product categories, distribution channels, technological integrations, and regional performance dynamics while excluding direct retail-to-consumer transactions.
What recent developments, partnerships, and strategic moves characterize active industry participants?
Recent developments underscore aggressive strategic maneuvers, including Arrow Electronics Inc. expanding its automated logistics hubs, Ingram Micro Inc. enhancing its cloud brokerage capabilities, and specialized players forging strategic partnerships to optimize reverse logistics for consumer electronics, ultimately streamlining supply chain efficiency across global trade corridors.