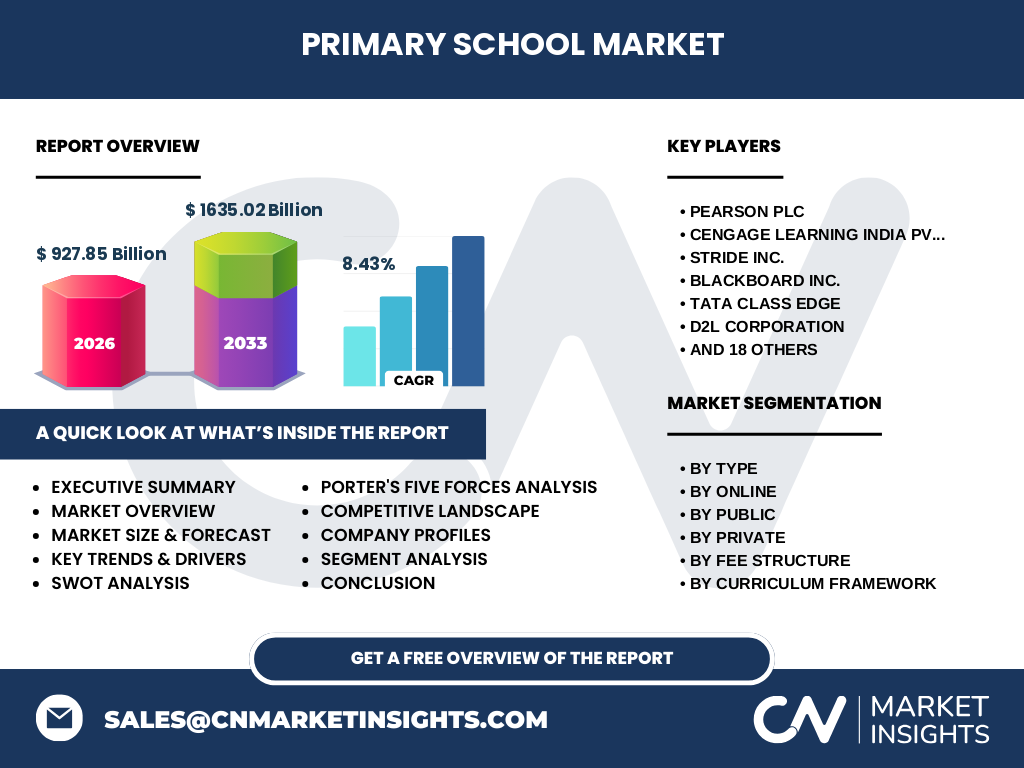
Market overview of the Primary School Market
The Primary School Market reaches a valuation of $927.85 Billion in 2026, encompassing foundational education delivery across public, private, and online channels. Our analysis indicates this sector is vital for foundational cognitive development, influenced heavily by regulatory mandates from bodies like the Department of Education and localized district constraints.
Key market drivers, restraints, challenges, and opportunities shaping the Primary School Market
Key drivers include surging digitalization and urban migration, while funding deficits pose a severe restraint. Logistical hurdles involve equitable broadband access in rural zones. Growth opportunities lie in specialized curriculum frameworks such as IB Primary Years and Montessori, favored by progressive institutions.
Emerging trends and growth patterns in the Primary School Market
The shift toward hybrid online-offline schools and AI-driven adaptive learning defines current industry trends. This growth pattern favors technology innovators capable of integrating seamlessly with traditional national curricula while offering personalized pacing for young learners.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically accelerated virtual adoption, straining legacy infrastructure. The recovery trajectory highlights robust institutional investments in cloud platforms and blended classrooms, permanently altering how foundational education is administered across district and private networks.
Competitive benchmarking and strategic dynamics in the Primary School Market
Market concentration is moderate, featuring established publishers alongside agile EdTech providers. Strategic dynamics center on digital content ecosystems. Companies like Pearson plc and McGraw-Hill Education leverage deep content libraries, while firms like Stride Inc. dominate virtual delivery.
Executive summary of the Primary School Market industry trends
Driven by technological integration, the Primary School Market is set to surge from $927.85 Billion in 2026 to $1635.02 Billion by 2033 at a CAGR of 8.43%. Institutional restructuring and demand for international curricula remain primary value catalysts.
Market forecast from 2027 to 2033
Our forecasting models project the market to expand from $927.85 Billion to $1635.02 Billion through 2033, achieving a steady 8.43% CAGR. This trajectory is underpinned by rising public-private partnerships and increased per-student digital expenditure globally.
Segmentation analysis across operational and curriculum categories
Segmentation spans Public (District, Charter, Magnet), Private (Religious, Independent, International), and Online tiers. Fee structures range from Low-Income to High-Income models, utilizing frameworks from National standards to Waldorf and Montessori methodologies.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America leading in EdTech adoption, while Asia-Pacific exhibits the fastest expansion driven by surging middle-class demographics demanding international and premium private school placements.
In-depth regional review of high-growth territories
Urban centers in developing economies face severe classroom density issues, accelerating demand for hybrid models. Meanwhile, mature markets focus on replacing aging physical infrastructure with smart-classroom hardware and localized regulatory compliance.
Company profiles and strategic positioning of leading participants
Industry leaders occupy distinct niches: GEMS Education and Nord Anglia Education dominate premium international schooling, whereas TAL Education Group and Benesse Corporation spearhead high-tech supplemental and foundational tutoring models across Asian markets.
Porter's Five Forces analysis of the Primary School Market
Bargaining power of buyers is moderate due to school choice programs, while supplier power from curriculum developers remains high. Threat of substitution rises via alternative homeschooling networks, intensifying rivalry among established private institutions.
SWOT analysis for primary education sector stakeholders
Strengths include steady demographic demand. Weaknesses involve regulatory compliance friction. Opportunities exist in emerging virtual academies. Threats include macroeconomic budget cuts affecting public school district disbursements and capital expenditure projects.
Value chain analysis from raw educational materials to end-users
The value chain flows from content creators, raw print/digital publishers, and software developers to institutional distributors, culminating in delivery by teachers to students within structured physical or virtual environments.
Investment insights and high-potential areas for capital allocation
High-potential areas target hybrid online-offline infrastructure and specialized international curricula providers. Investors should prioritize enterprises scaling adaptive learning software with proven institutional sales pipelines.
Conclusion and key takeaways for industry decision-makers
The sector presents compelling growth through 2033, rewarding organizations that successfully bridge traditional pedagogy with scalable digital delivery models and robust regulatory alignment.
Research methodology for baseline estimates and data triangulation
Baseline figures are triangulated by combining official trade registry data, primary stakeholder interviews with school administrators, and secondary macroeconomic indicators from global education ministries.
Scope of the report, coverage parameters, and analytical limitations
This report covers global primary education from 2026 to 2033 across specified public, private, and online segments, excluding informal homeschooling networks lacking formal accreditation.
Recent developments, corporate announcements, and strategic partnerships
Recent market activity highlights major publishing houses partnering with AI platform developers to embed automated assessment tools directly into core mathematics and literacy curricula.