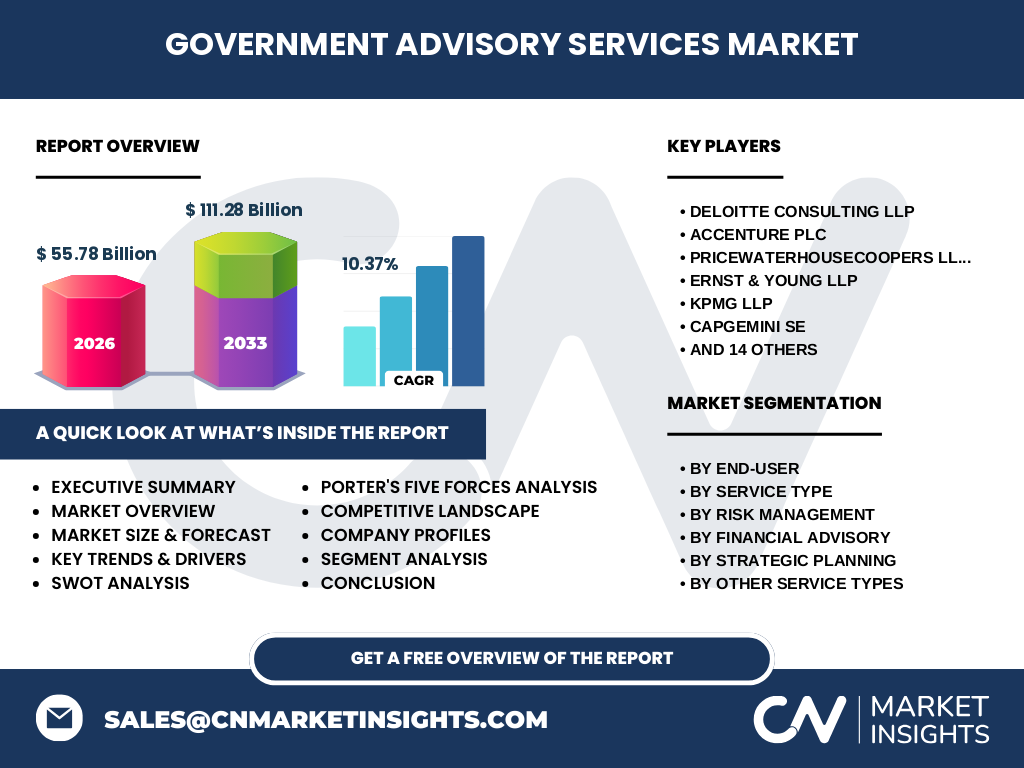
Market overview of the Government Advisory Services Market
Our analysis indicates the Government Advisory Services Market valued at 55.78 Billion in 2026 encompasses specialized consulting for public sector entities. This vital industry navigates complex regulatory frameworks involving agencies like the SEC and EPA, delivering critical insights across federal, state, and local governments to optimize public service delivery and operational efficacy.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating demands for digital transformation and stringent compliance mandates. However, restrained by prolonged procurement cycles and rigid bureaucratic budgets, growth requires firms to deploy robust risk identification and crisis management strategies to help agencies overcome operational bottlenecks.
Emerging Trends in the Government Advisory Services Market
The shift toward e-governance solutions consulting and cybersecurity framework implementation defines modern industry trends. Public sector entities increasingly rely on specialized advisors to modernize legacy IT systems, protect critical infrastructure from sophisticated threats, and enhance citizen engagement portals.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic served as an unprecedented catalyst, forcing rapid adaptation in public debt management, grant and subsidy management, and crisis response. Our research shows that recovery has accelerated spending toward resilience building, driving sustained demand for agile financial risk assessment and workforce planning.
Competitive Benchmarking in the Consulting Ecosystem
The competitive landscape features dominant players like Deloitte Consulting LLP, Accenture plc, and Booz Allen Hamilton Holding Corporation leveraging deep federal relationships. Mid-tier firms and specialists like Guidehouse Inc. and PA Consulting Group Limited carve out niches via bespoke technological and digital transformation advisory.
Executive Summary of Key Industry Findings
Driven by robust public sector modernization, the Government Advisory Services Market is poised for significant expansion. With a projected market size reaching 111.28 Billion by 2033, strategic investments in cloud services advisory and public infrastructure planning will yield high returns for forward-thinking firms.
Long-Term Market Forecast from 2027 to 2033
Our forecasting models project the market to expand from 2027 to 2033 at a steady CAGR of 10.37%, culminating in a valuation of 111.28 Billion by the end of the forecast period. This trajectory underscores sustained government outlays toward strategic planning and compliance monitoring.
Segmentation Analysis Across Service Types and End-Users
The market divides by end-user into Federal Government, State Government, and Local Government. Service types span Strategic Planning, Policy And Regulation, Financial Advisory, and Risk Management, with each segment addressing unique administrative and regulatory compliance mandates.
Geographic Distribution and Regional Performance
Regional performance varies based on centralized federal spending and local government budgetary constraints. North America remains the dominant revenue generator due to heavy federal defense and cybersecurity investments, while Europe and Asia-Pacific exhibit accelerated growth driven by public sector digitization initiatives.
In-Depth Regional Review of Administrative Markets
North American advisory demand centers on complex federal compliance and infrastructure management. Meanwhile, European markets prioritize stringent environmental and social risk analysis alongside GDPR-aligned digital transformation, creating specialized advisory pockets for firms like Roland Berger Holding GmbH and Oliver Wyman Inc.
Strategic Positioning of Leading Companies
Industry leaders such as PricewaterhouseCoopers LLP (PwC), Ernst & Young LLP, and KPMG LLP utilize extensive global footprints to dominate audit and compliance advisory. Concurrently, specialized strategy powerhouses like Boston Consulting Group Inc. and McKinsey & Company Inc. focus on high-level organizational strategy formulation.
Porter's Five Forces Analysis of Competitive Pressures
Rivalry is intense among established tier-one consultants, while the threat of new entrants remains moderate due to stringent government security clearances and past performance requirements. Buyer power is counterbalanced by the specialized, mission-critical nature of advanced cybersecurity and financial advisory services.
SWOT Analysis of the Government Advisory Sector
Strengths include deep domain expertise and entrenched client relationships. Weaknesses involve high dependency on shifting political budgets. Opportunities lie in expanding e-governance solutions, while threats encompass tightening regulatory scrutiny on government contracting and potential macroeconomic austerity measures.
Value Chain Analysis from Expertise to Public Implementation
The value chain flows from foundational regulatory research and data analytics to strategic formulation, policy drafting, and eventual implementation by government workforce teams. Value capture concentrates heavily at the diagnostic and technological advisory stages, favoring firms with robust proprietary tools.
Strategic Investment Insights and High-Potential Areas
Investors should target consultancies possessing advanced Cybersecurity Framework Implementation and Data Analytics And Cloud Services Advisory capabilities. These high-margin niches address urgent public sector vulnerabilities and align directly with ongoing legislative mandates for secure government infrastructure.
Conclusion and Key Takeaways for Market Stakeholders
The Government Advisory Services Market offers lucrative expansion pathways anchored by a 10.37% CAGR through 2033. Success demands marrying traditional public sector acumen with cutting-edge digital transformation and risk mitigation methodologies to secure long-term government contracts.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining public procurement registry data, primary stakeholder interviews with senior public sector consultants, and secondary macroeconomic indicators to ensure high fidelity across all market sizing and growth projections.
Scope of the Report and Coverage Parameters
This report covers global advisory expenditures across federal, state, and local administrative bodies. Limitations include the exclusion of internal government payroll costs and non-advisory IT hardware procurement, focusing strictly on specialized professional consulting and advisory engagements.
Recent Developments and Strategic Industry Moves
Recent market activities feature major consulting firms forging public-private partnerships to deploy advanced AI-driven compliance monitoring tools. Strategic acquisitions by players like Capgemini SE and Alvarez & Marsal Holdings LLC highlight a concerted push to enhance sovereign cloud and emergency management offerings.