What is the scope and industry significance of the Metal Mining Support Activities Market?
Our analysis indicates that the Metal Mining Support Activities Market represents an indispensable pillar of the global resource extraction framework. Valued at 227.23 Billion in 2026, this sector encompasses critical operational services—ranging from specialized drilling to complex water management—that enable miners to extract essential ores safely and efficiently while navigating stringent environmental regulations set by bodies like the EPA and ICMM.
Key market drivers, restraints, challenges, and opportunities shaping Metal Mining Support Activities Market
The market is propelled by surging demand for energy transition metals such as copper and lithium. However, high capital intensity and stringent ESG compliance act as major restraints. Opportunities abound for tech-driven contractors offering automated surface drilling services and advanced water treatment services to mitigate severe logistical hurdles in remote extraction hubs across Western Australia and Latin America.
Emerging trends and growth patterns in Metal Mining Support Activities Market
Industry trends highlight an aggressive pivot toward automation and electrification underground. Major service providers are increasingly adopting remote-controlled geophysical survey services and zero-emission material handling fleets. This shift improves worker safety in deep underground environments while optimizing operational expenditure for tier-one mining houses.
How did the COVID-19 pandemic affect the Metal Mining Support Activities Market and its recovery trajectory?
The pandemic triggered severe supply chain bottlenecks, workforce shortages, and temporary site suspensions globally. Yet, our research shows a robust post-crisis rebound driven by aggressive fiscal stimulus and soaring commodity prices. Companies like Major Drilling Group International Inc. and Boart Longyear Ltd. leveraged expedited remote operations to stabilize project pipelines and accelerate recovery.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a mix of specialized contractors and diversified global conglomerates. Market concentration is moderate, with tier-one firms like Perenti Global Ltd. and Weir Group plc dominating through proprietary technological capabilities. Strategic mergers and localized joint ventures remain the primary mechanisms for expanding geographic footprints and securing long-term service contracts.
Executive Summary: High-Level Synthesis of Key Findings
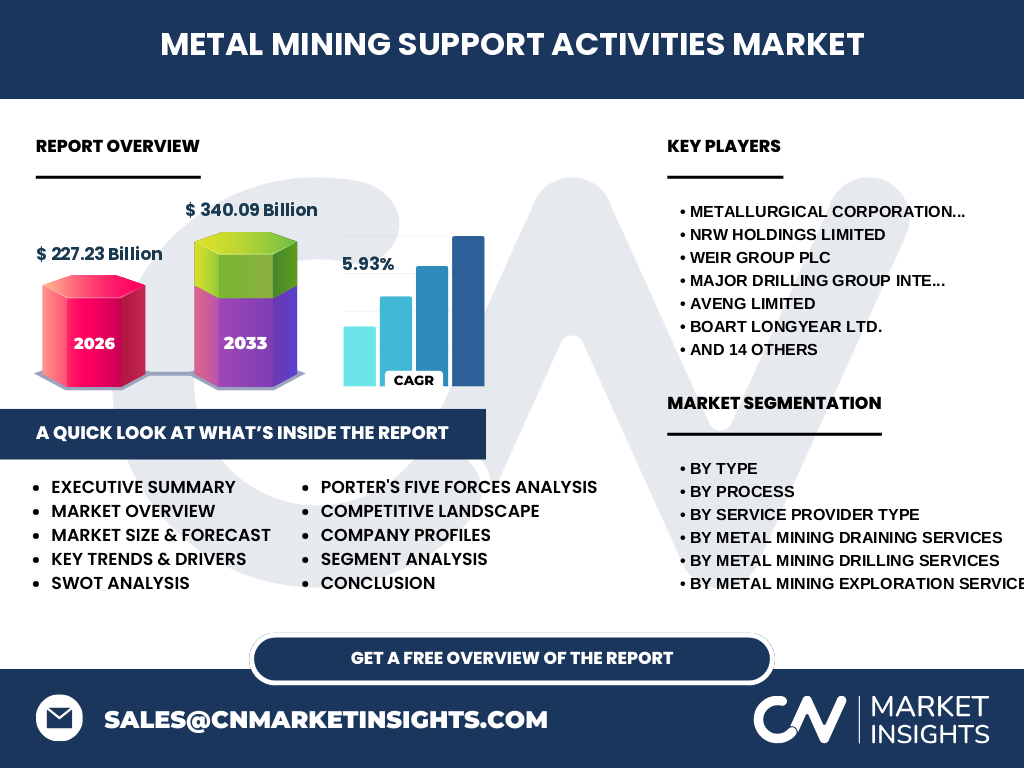
The global Metal Mining Support Activities Market is on a robust upward trajectory, projected to surge from 227.23 Billion in 2026 to 340.09 Billion by 2033 at a CAGR of 5.93%. Accelerated by rising mineral demand and technological innovation, the sector offers high-yield opportunities for strategic investors focusing on specialized exploration drilling services and environmental compliance solutions.
Market Forecast: Projected Growth from 2027 to 2033
Based on our econometric modeling, the industry will expand steadily at a 5.93% CAGR over the forecast period. Total market revenue will climb from its 2026 baseline of 227.23 Billion to reach 340.09 Billion by 2033. This expansion is heavily underpinned by sustained capital expenditure in complex opencast and deep underground metalliferous extraction projects worldwide.
Segmentation Analysis of the Metal Mining Support Activities Sector
The market is segmented by type into Metal Mining Drilling Services, Metal Mining Exploration Services, Metal Mining Draining Services, and Other Support Activities. Process-wise, it divides into Underground and Opencast operations, serviced by independent contractors and captive corporate entities. Specialized segments like blasting services and dewatering services remain vital for mitigating geotechnical risks.
Geographic Distribution and Regional Performance
Regional performance varies significantly based on mineral endowment and infrastructure maturity. The Asia-Pacific region commands the largest revenue share, driven by extensive mining operations in Australia and China. Meanwhile, Latin America and Africa represent high-growth frontiers, heavily reliant on specialized geological survey services and heavy-duty material handling services to unlock remote deposits.
In-Depth Regional Review of Core Mining Jurisdictions
In Australia, stringent safety mandates and remote logistics favor established domestic contractors such as NRW Holdings Limited and Barminco Holdings Pty Limited. In North America, strict environmental reviews by agencies like the EPA elevate the demand for advanced environmental and waste management services, directly benefiting specialized engineering firms operating near major rail and port facilities.
Company Profiles: Strategic Positioning of Leading Industry Participants
Industry leaders maintain distinct competitive moats through specialized service portfolios. Metallurgical Corporation of China Limited leverages massive engineering scale, while Boart Longyear Ltd. and Major Drilling Group International Inc. lead in specialized diamond and surface drilling services. Firms like Ausenco Limited and DRA Global Limited focus heavily on turnkey project delivery and complex metallurgical processing support.
Porter's Five Forces Analysis of the Support Sector
The threat of new entrants remains low due to high capital expenditure requirements for specialized drilling rigs and stringent safety accreditations. Bargaining power of buyers is moderate to high, as major mining houses demand competitive pricing. Meanwhile, rivalry among established contractors like Downer EDI Limited and Foraco International SA drives continuous technological innovation and service diversification.
SWOT Analysis: Strategic Strengths, Weaknesses, Opportunities, and Threats
Key strengths include deep technical expertise and proprietary machinery fleets held by players like Cementation USA Inc. Weaknesses involve high exposure to commodity price volatility. Opportunities lie in automated sampling services and greenfield exploration, while threats stem from tightening regulatory frameworks and geopolitical friction affecting critical mineral supply chains.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with early-stage geological mapping and geophysical survey services, progressing through exploratory drilling and resource estimation. Mid-stream activities involve site development, dewatering services, and active ore extraction via underground or opencast processes. Downstream integration culminates in environmental rehabilitation and waste management executed by specialized providers like Dyno Nobel Inc. and Bis Industries Holdings Limited.
Investment Insights and High-Potential Areas
Our analysis highlights water treatment services and automated underground drilling services as prime areas for venture capital and strategic M&A. Investors should prioritize tech-enabled contractors operating in stable jurisdictions with rich critical mineral reserves, as these firms exhibit superior margin resilience and alignment with global ESG investment mandates.
Conclusion and Key Strategic Takeaways
The Metal Mining Support Activities Market offers compelling growth, scaling to 340.09 Billion by 2033. Success in this landscape requires rigorous adherence to ESG standards, rapid integration of automation, and deep technical specialization. Forward-thinking participants positioning themselves in advanced environmental and exploration niches will capture disproportionate market share.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with mining executives, trade registry data from global mining chambers, and secondary macroeconomic indicators. We cross-reference corporate earnings reports from key market players like Perenti Global Ltd. and Weir Group plc with official government trade statistics to ensure absolute forecast accuracy.
Scope of the Report and Coverage Parameters
This report covers global revenue streams for Metal Mining Support Activities Market segments from 2026 through 2033. Excluded from this scope are non-metal aggregate quarrying, oil and gas extraction support services, and downstream smelting operations. Geographic scope encompasses North America, Latin America, Europe, Asia-Pacific, and the Middle East & Africa.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is defined by strategic cross-border acquisitions and green technology partnerships. Leading firms are heavily investing in autonomous fleet integrations and low-carbon drilling technologies. For instance, companies like AusGroup Limited and Aveng Limited have recently restructured service contracts to prioritize sustainable, low-emissions operational support for tier-one global mining clients.