What is the market overview and industry significance of the Distributor Market?
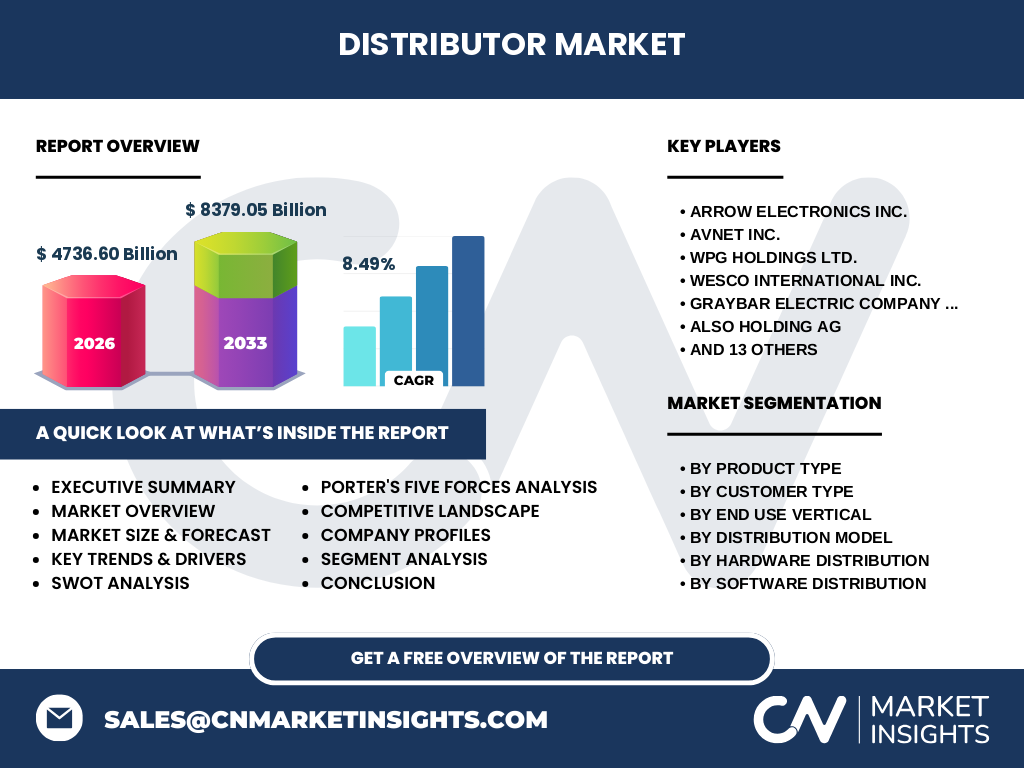
Our analysis indicates that the Distributor Market market size reaches 4736.60 Billion by 2026, serving as the critical transactional backbone connecting tier-one component manufacturers with global resellers and system integrators. Global supply chain resilience heavily relies on these intermediaries to navigate complex trade compliance and localized logistics.
What are the core market drivers, restraints, challenges, and opportunities shaping the Distributor Market?
The Distributor Market industry trends highlight accelerated cloud migration as a primary driver, while ongoing semiconductor shortages present severe logistical restraints. Strategic expansion into digital marketplace models allows major players to overcome regional trade barriers and capture high-margin software revenues.
Structural Growth Drivers in the Distributor Market
Rapid enterprise adoption of Infrastructure as a Service (IaaS) and Cybersecurity Solutions Distribution fuels unprecedented growth. Based on our research, distributors shifting from traditional hardware provisioning to recurring cloud revenue models achieve significantly higher valuation multiples.
COVID-19 impact analysis and recovery trajectory for the Distributor Market
The pandemic exposed extreme vulnerabilities in global supply chains, forcing distributors to diversify inventory sourcing away from single-region manufacturing hubs. Recovery has been spearheaded by heavy investments in automated distribution platforms and enhanced inventory visibility tools.
Competitive Benchmarking and Industry Concentration
The competitive landscape features dominant global giants like Arrow Electronics Inc., Avnet Inc., and TD SYNNEX Corporation leveraging massive economies of scale. Market concentration remains high in enterprise IT hardware, while niche distributors carve out defensible positions in cybersecurity and embedded systems.
Executive Summary of the Distributor Market Report
Our comprehensive analysis reveals a soaring market trajectory, projecting expansion from 4736.60 Billion in 2026 to 8379.05 Billion by 2033 at a robust 8.49% CAGR. Success requires aggressive pivoting toward hybrid cloud platforms and specialized value-added services.
Distributor Market Forecast and Long-Term Projections (2027 to 2033)
The data suggests sustained economic momentum, with the Distributor Market valuation scaling from 4736.60 Billion in 2026 to a projected 8379.05 Billion by 2033. This growth is underpinned by enterprise digitization initiatives and surging demand for advanced data center hardware.
Comprehensive Segmentation Analysis of the Distributor Market
The market breaks down across diverse verticals and product categories:
- Product Type: Hardware, Software, Cloud Services, Cybersecurity, Networking, Enterprise Applications
- Customer Type: Resellers, SIs, MSPs, End Customers
- End Use Vertical: BFSI, Healthcare, Retail, Manufacturing, Government, Telecom
Geographic Distribution and Regional Performance Analysis
Regional performance varies significantly, with North America leading in software and cloud distribution adoption, while Asia-Pacific dominates industrial hardware and consumer IT distribution. European markets exhibit stringent compliance frameworks favoring localized cybersecurity and data protection offerings.
In-Depth Regional Review and Market Dynamics
North American growth is anchored by extensive enterprise data center investments and mature MSP ecosystems. Meanwhile, Asia-Pacific benefits from robust electronics manufacturing clusters, creating high-volume distribution demands for enterprise servers and embedded hardware.
Strategic Positioning of Leading Companies in the Distributor Market
Firms like WESCO International Inc. and Ingram Micro Inc. utilize sophisticated digital platforms to streamline indirect distribution through resellers. Specialized distributors such as Digi-Key Electronics focus on electronic components, maintaining distinct competitive moats against broadline giants.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of suppliers is moderate due to consolidated OEM manufacturing, while buyer power remains high among large enterprise customers demanding custom pricing. The threat of substitutes is low, but new entrants face intense capital barriers in global logistics infrastructure.
SWOT Analysis of the Distributor Market
Strengths include entrenched global logistics networks and deep OEM relationships. Weaknesses involve thin operating margins in hardware distribution. Opportunities lie in cloud migration services, while threats stem from macroeconomic volatility and direct-to-enterprise manufacturer sales.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw material silicon and mineral suppliers to OEM component manufacturers, through global distributors like Arrow Electronics Inc. and Avnet Inc., and onward to system integrators, managed service providers, and final enterprise end-users.
Investment Insights and High-Potential Growth Areas
Investors should prioritize distributors scaling their Cloud Based Digital Distribution Platforms and Cybersecurity Solutions Distribution portfolios. These segments command superior margins and exhibit recession-resistant recurring revenue characteristics compared to legacy hardware.
Conclusion and Strategic Takeaways for Industry Stakeholders
Reaching 8379.05 Billion by 2033 requires distributors to aggressively embrace digital transformation and hybrid distribution models. Companies failing to transition from physical hardware transit to software-defined service delivery risk margin compression.
Research Methodology and Baseline Estimation Techniques
Our baseline estimates are triangulated by combining exhaustive trade registry data, primary stakeholder interviews with C-level distribution executives, and secondary macroeconomic indicators from global trade organizations, ensuring rigorous top-down and bottom-up validation.
Scope of the Report and Coverage Parameters
This report covers global distribution dynamics from 2026 to 2033 across specified hardware, software, cloud, cybersecurity, and networking verticals. Limitations include unforeseen geopolitical disruptions and sudden trade tariff implementations that could alter regional baseline forecasts.
Recent Developments, Strategic Partnerships, and Corporate Announcements
Recent industry activity features major players like TD SYNNEX Corporation and ALSO Holding AG forming strategic alliances with hyper-scale cloud providers. These partnerships aim to expand automated software provisioning capabilities and enhance SMB cloud migration efficiency.