Market overview and structural scope of the Advertising Agencies Market
Our analysis indicates that the Advertising Agencies Market size stands at $441.79 Billion in 2026, representing a foundational ecosystem of creative, digital, and media-buying enterprises. This sector orchestrates global brand communication across diverse channels, navigating strict data privacy mandates from regulatory bodies like the FTC and GDPR while managing complex logistical supply chains for physical and digital ad placements.
Key market drivers, restraints, challenges, and opportunities
The market is propelled by rapid digital transformation and programmatic buying efficiencies, though constrained by tightening cookie deprecation protocols and economic headwinds. Agencies face acute talent retention hurdles. However, significant growth opportunities lie in emerging retail media networks and AI-driven hyper-personalization, favoring tech-forward firms over legacy operators.
Emerging trends and growth patterns in the Advertising Agencies Market
The industry is witnessing an aggressive shift toward in-house agency models and immersive metaverse activations. Consumers increasingly demand hyper-targeted digital video and social commerce integrations, forcing agencies to overhaul traditional workflows. Firms embracing automated performance marketing are capturing disproportionate wallet shares.
COVID-19 impact analysis and recovery trajectory
The pandemic triggered severe budget contractions across offline channels like print and out-of-home, compelling an immediate pivot to digital performance marketing. Recovery has been uneven; while traditional mediums faced structural declines, digital spend surged, cementing a permanent structural shift toward measurable, ROI-focused campaigns managed by agile agency networks.
Competitive landscape and strategic market concentration
The sector features intense competition among holding giants like WPP PLC, Publicis Groupe, and Omnicom Group Inc., alongside nimble independents. Market concentration remains high at the enterprise level, but specialized digital boutiques are capturing market share by offering localized agility that traditional monoliths struggle to match.
Executive summary of key findings in the Advertising Agencies Market
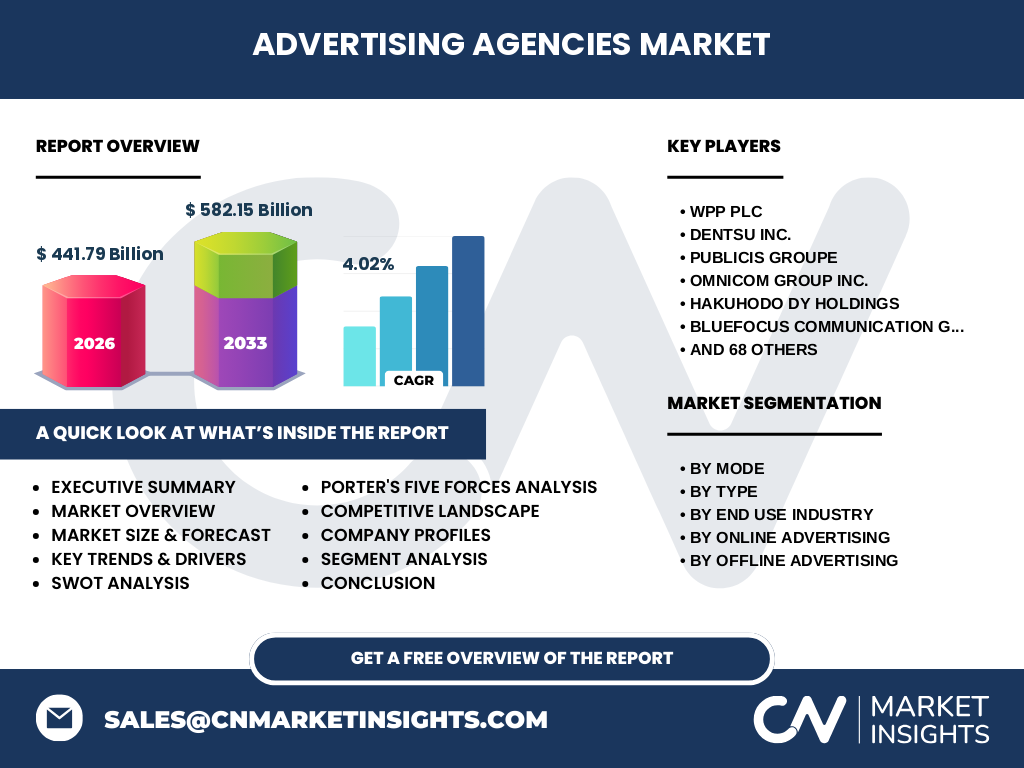
Driven by robust digital demand, the Advertising Agencies Market industry trends point toward a steady expansion path, projecting growth from $441.79 Billion in 2026 to $582.15 Billion by 2033 at a CAGR of 4.02%. Strategic consolidation and AI integration remain critical imperatives for long-term survival.
Market forecast from 2027 to 2033
Based on our research, the sector is projected to expand from $582.15 Billion by 2033, maintaining a steady CAGR of 4.02% starting from its $441.79 Billion valuation in 2026. This expansion is underpinned by sustained enterprise investments in programmatic media and connected television ecosystems.
Segmentation analysis across operational modes and mediums
The market divides fundamentally by mode into Online Advertising and Offline Advertising, spanning formats like TV, Digital, Radio, Print, and OOH. End-use verticals range from BFSI and Retail to Government and IT & Telecom, each requiring specialized compliance frameworks and audience targeting strategies.
Regional market analysis and geographic performance distribution
Geographic performance reflects stark disparities in digital infrastructure maturity. North America leads in digital spend volume, while Asia-Pacific exhibits the fastest growth velocity, fueled by mobile-first consumer bases in Southeast Asia and regulatory shifts in major APAC economies.
In-depth regional review of key advertising hubs
North America anchors global revenues due to high concentrations of Fortune 500 brands and advanced ad-tech stacks. Meanwhile, European markets operate under strict GDPR constraints, pushing agencies in London, Paris, and Frankfurt to pioneer privacy-compliant contextual targeting solutions.
Company profiles and strategic positioning of leading players
Industry leaders like Dentsu Inc., Hakuhodo DY Holdings, and The Interpublic Group of Companies leverage global scale and proprietary data platforms. Meanwhile, consultancies like Accenture Interactive blur traditional agency boundaries by embedding deep IT consulting directly into creative execution.
Porter's Five Forces analysis of the advertising sector
Rivalry is fierce due to low switching costs and intense pitch culture. Buyer power is moderate-to-high as enterprise clients demand lower retainers and performance-based compensation. Threat of substitutes remains elevated as brands increasingly build internal creative capabilities.
SWOT analysis of the global agency ecosystem
Strengths lie in established creative talent and global client networks. Weaknesses involve margin compression from procurement-led fee slashing. Opportunities exist in burgeoning retail media networks, while threats stem from generative AI platforms potentially disintermediating junior creative labor.
Value chain analysis from raw data to end-user engagement
The industry value chain flows from raw consumer data inputs and software platforms through strategic media planning and creative production, culminating in multi-channel distribution via publishers, OOH networks, and broadcasters to reach final end-users.
Investment insights and high-potential growth areas
High-potential capital allocation targets include boutique agencies specializing in retail media networks, generative AI workflow optimization startups, and agencies with robust cross-border capabilities navigating fragmented Asian digital ecosystems.
Conclusion and key strategic takeaways
Achieving sustainable growth in the Advertising Agencies Market analysis requires migrating away from archaic retainer models toward outcome-based pricing, heavily anchored in proprietary data infrastructure and AI-driven creative production efficiencies.
Research methodology for baseline estimation and triangulation
Our baseline estimates are rigorously triangulated by synthesizing trade registry filings, primary stakeholder interviews with holding company executives, and secondary macroeconomic indicators from regional advertising bureaus to ensure absolute market sizing accuracy.
Scope of the report and coverage parameters
This report covers global agency billing revenues, fee incomes, and digital media spend across North America, Europe, Asia-Pacific, Latin America, and MEA. Exclusions apply to in-house brand spending that does not flow through third-party agency intermediaries.
Recent developments, mergers, and strategic partnerships
Recent market activity is dominated by holding group acquisitions of boutique commerce-media specialists, strategic partnerships between agency holding companies and major cloud providers, and the rapid rollout of proprietary generative AI content generation tools.