Market overview and structural significance of the Aluminum Die Casting Market
Our analysis indicates that the Aluminum Die Casting Market is valued at $76.05 Billion in 2026. This sector encompasses the production of non-ferrous metal components using high-pressure, low-pressure, and vacuum techniques. As stringent EPA and Euro 7 emissions standards force automakers to seek lightweight alternatives to iron, aluminum die casting has become foundational to modern automotive and industrial manufacturing.
Key market drivers, restraints, challenges, and opportunities shaping the sector
The primary catalyst is the aggressive pursuit of vehicle lightweighting by OEMs, balanced against volatile primary aluminum ingot pricing. Regulatory pressure from bodies like the National Highway Traffic Safety Administration (NHTSA) drives demand. However, casting porosity defects and high tooling capital expenditures present persistent operational challenges. Opportunities lie in developing thin-walled structural battery housings for electric vehicles.
The Shift Toward Advanced Foundry Technologies and Industry Trends
The market is experiencing a massive pivot toward Vacuum Assisted High Pressure Die Casting to eliminate entrapped gas and improve structural integrity for heat-treatable components. Industry trends highlight the adoption of IoT-enabled smart foundries utilizing real-time thermal imaging and automated molten metal dosing to drastically reduce scrap rates and optimize cycle times for complex geometries.
COVID-19 impact analysis and pandemic recovery trajectory
The pandemic severely disrupted the supply chain, causing widespread Tier-1 automotive shutdowns and acute shortages of primary alloy inputs. Recovery has been spearheaded by a strong rebound in industrial automation and aggressive government stimulus packages targeting green manufacturing infrastructure, restoring robust momentum across major foundry operations globally.
Competitive Benchmarking and Market Concentration
The Aluminum Die Casting Market exhibits a moderately consolidated landscape dominated by global heavyweights like Nemak SAB de CV and GF Casting Solutions. Strategic dynamics revolve around mega-casting capabilities, where Tier-1 suppliers invest heavily in ultra-large 4,000+ ton locking force machines to produce single-piece underbody frames, displacing traditional multi-part welded assemblies.
Executive summary of key findings and valuation metrics
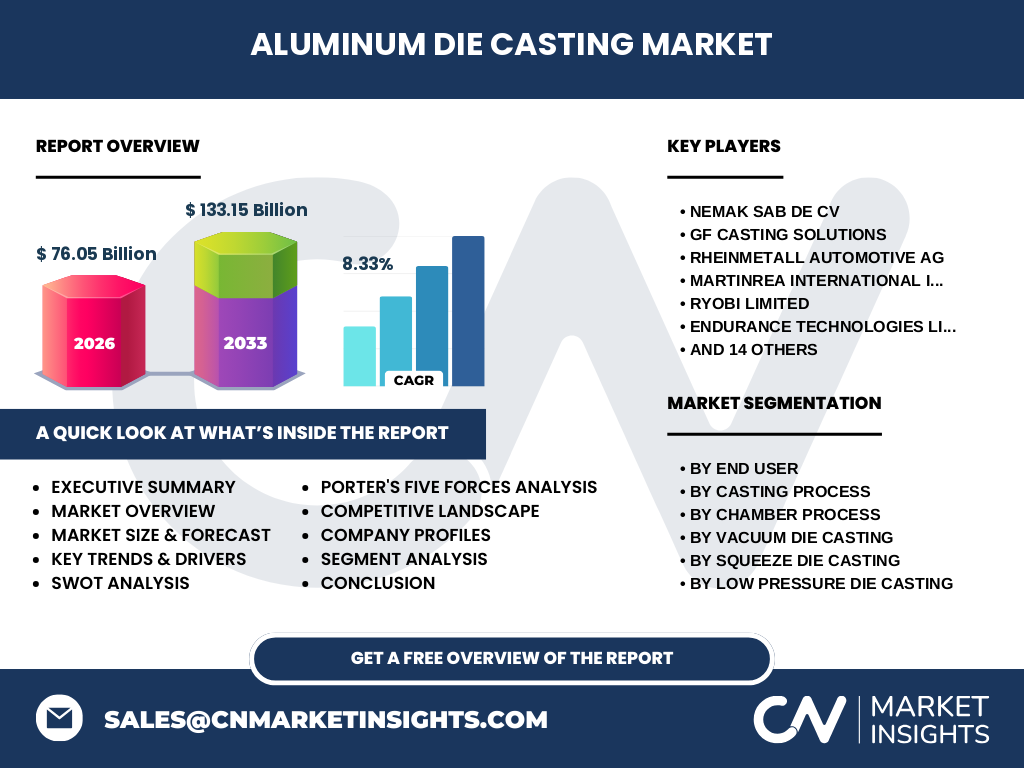
Our proprietary research reveals robust expansion, projecting the market to surge from $76.05 Billion in 2026 to $133.15 Billion by 2033 at a notable CAGR of 8.33%. This trajectory is underpinned by rapid electrification in mobility sectors and rising demand for corrosion-resistant pump and valve housings in fluid management systems.
Market forecast trajectory from 2027 to 2033
Driven by compounding adoption across alternative powertrain architectures, the market will scale aggressively over the forecast window. Reaching $133.15 Billion by 2033 from its $76.05 Billion 2026 baseline, the sector will maintain a steady 8.33% CAGR, rewarding early investors in automated cold chamber machinery and high-integrity squeeze casting operations.
Segmentation analysis by end-user and casting process
The market segments into critical verticals: Automotive Components, Pumps And Valves, Industrial Component, Engineering Components, Construction, and Other End Users. By process, it spans High Pressure Die Casting, Low Pressure Die Casting, Vacuum Die Casting, and Squeeze Die Casting. Chamber variations include Hot Chamber and Cold Chamber processes tailored to specific melting points and alloy fluidity requirements.
Geographic distribution and regional market analysis
Regional performance is heavily skewed toward industrialized manufacturing hubs with established automotive supply chains. Asia-Pacific leads volume consumption due to massive localized EV production in China, while North America and Europe focus heavily on high-margin structural engineering components and stringent regulatory compliance managed through regional trade registries.
In-depth regional review of manufacturing hubs and logistics
Proximity to major automotive clusters dictates regional success. North American foundries leverage localized scrap aluminum supplies, while European manufacturers navigate strict carbon border adjustment mechanisms (CBAM). Asian markets benefit from deeply integrated supply ecosystems centered around high-throughput coastal ports, driving continuous export competitiveness for complex powertrain castings.
Strategic positioning of leading companies in the ecosystem
Industry leaders employ distinct specialization strategies. Rheinmetall Automotive AG and Nemak SAB de CV focus on advanced powertrain and structural closures, while specialists like Dynacast International Inc. dominate miniature, high-precision components. Companies such as Ryobi Limited and Gibbs Die Casting Corporation leverage proprietary die design and alloy development to secure long-term OEM platform contracts.
Porter's Five Forces analysis of the foundry sector
Supplier power remains moderate, dictated by global aluminum pricing fluctuations controlled by major metal exchanges. Buyer power is high due to concentrated automotive OEM demands. Threat of substitutes is mitigated by aluminum’s superior strength-to-weight ratio, while high capital equipment costs and proprietary die engineering create a formidable barrier to new market entrants.
SWOT analysis of the Aluminum Die Casting Market
Strengths include exceptional strength-to-weight properties and high-volume repeatability. Weaknesses involve high initial tooling costs and energy-intensive melting phases. Opportunities emerge from lightweight electric vehicle architectures and renewable energy infrastructure brackets. Threats stem from volatile raw material tariffs and emerging carbon-fiber structural composite technologies encroaching on traditional metal applications.
Value chain analysis from raw material input to end-user delivery
The value chain initiates with primary aluminum smelters and secondary scrap recyclers supplying alloy ingots to die casting foundries. Foundries utilize precision tooling and advanced thermal simulation software before passing rough castings through CNC machining, heat treatment, and surface finishing, ultimately supplying fully assembled modules to tier-one systems integrators.
Strategic investment insights and high-potential focus areas
Investors should prioritize facilities equipped for Vacuum Assisted High Pressure Die Casting and mega-casting cells. Capital allocated toward closed-loop aluminum recycling programs within foundries yields immediate margin protection against primary metal price spikes, positioning portfolio companies to capture high-growth EV structural component contracts.
Conclusion and critical industry takeaways
The Aluminum Die Casting Market represents a vital, technology-driven sector poised to capture significant value as global industries decarbonize. With a forecasted expansion to $133.15 Billion by 2033, success will favor technologically agile foundries capable of integrating advanced digital quality control with high-integrity structural casting capabilities.
Research methodology and data triangulation practices
Our baseline estimates are rigorously triangulated by cross-referencing primary stakeholder interviews with foundry executives, comprehensive customs and trade registry data, and secondary macroeconomic indicators from industrial manufacturing indices. This multi-tiered validation approach guarantees high-fidelity market sizing and accurate growth projections.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue and volume projections from 2026 through 2033, segmented rigorously by casting process, chamber type, and end-user vertical. Limitations include unforeseen macroeconomic trade policy shifts, sudden localized energy tariff adjustments, and rapid fluctuations in primary raw material commodity pricing.
Recent developments, strategic partnerships, and capacity expansions
Recent market activities highlight aggressive capital expenditure by major players such as Martinrea International Inc. and Pace Industries, focusing on multi-thousand-ton press installations. Strategic joint ventures between tier-one casters and primary aluminum producers aim to secure predictable low-carbon metal supply chains amidst tightening global environmental regulations.