What is the scope and market size of the Halal Cosmetics Market?
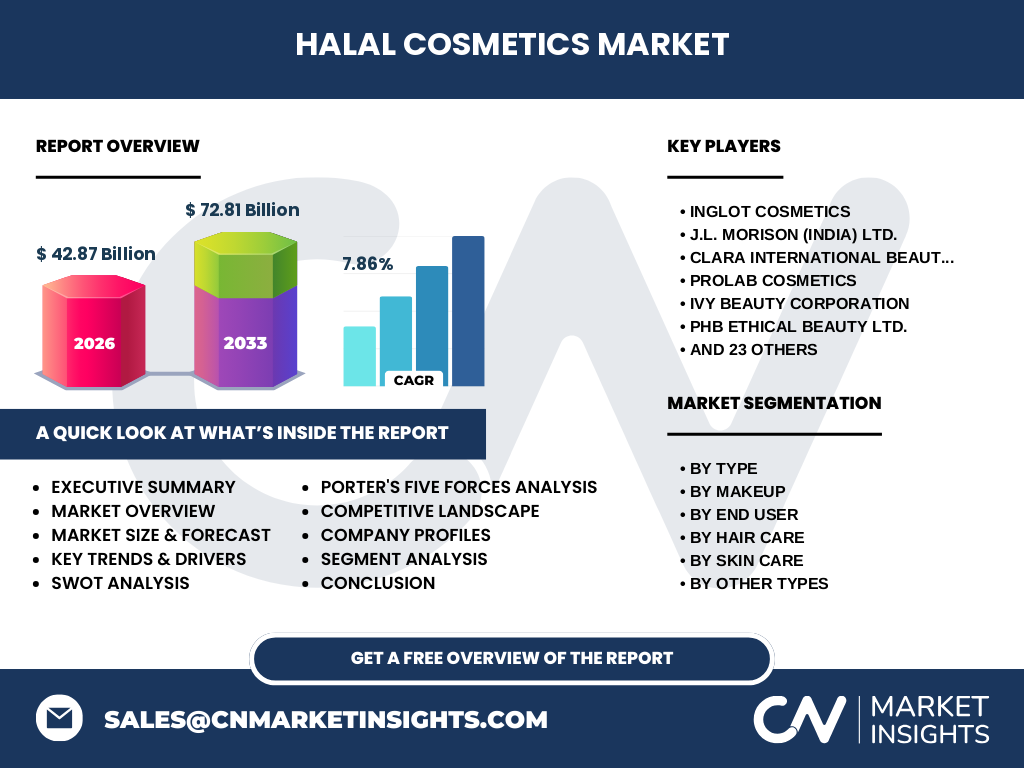
Our analysis indicates that the Halal Cosmetics Market market size is valued at $42.87 Billion in 2026. The sector spans ethical, alcohol-free, and cruelty-free personal care items compliant with Islamic law, governed by strict raw material sourcing and manufacturing standards.
Structural Growth Drivers and Market Restraints
Growth is accelerated by rising disposable incomes in Southeast Asia and the Middle East, alongside expanding Muslim demographic cohorts. However, market expansion faces regulatory friction due to fragmented certification standards across different national bodies like JAKIM and MUI.
The Shift Toward Ethical Consumerism and Clean Beauty
Industry trends reveal a powerful convergence between halal compliance and vegan, organic formulations. Brands like PHB Ethical Beauty Ltd. and INIKA Organic Australia capitalize on this by marketing transparent, plant-based supply chains that appeal to both Muslim and non-Muslim consumers.
Pandemic Aftershocks and Recovery Trajectory in Halal Personal Care
COVID-19 temporarily disrupted supply chains for key botanicals and packaging materials, depressing retail sales in 2020 and 2021. Nevertheless, the market rebounded strongly as digital e-commerce adoption surged, positioning the industry for a robust 7.86% CAGR from 2027 to 2033.
Competitive Benchmarking and Industry Concentration
The landscape is highly fragmented, featuring local pioneers and multinational conglomerates. Key players like Wardah Cosmetics and INGLOT Cosmetics compete aggressively through localized product innovations, leveraging digital marketing to capture share in urban hubs.
Executive Summary of Halal Cosmetics Market Industry Trends
Our research forecasts the Halal Cosmetics Market industry trends to reach $72.81 Billion by 2033, driven by a 7.86% CAGR starting in 2027. Demand is shifting from niche domestic markets to mainstream global retail channels.
Long-Term Market Forecast from 2027 to 2033
The data suggests exceptional momentum, expanding from the 2026 valuation of $42.87 Billion to culminate at $72.81 Billion by 2033. This growth trajectory reflects mainstream acceptance and deeper penetration into Western retail markets.
Segmentation Analysis of Product Categories and End Users
The market is structured into Skin Care (Moisturizers, Cleansers, Sunscreen, Face Masks, Serums), Hair Care (Shampoos, Conditioners, Hair Oils, Hair Masks, Styling Products), Makeup (Foundation, Lipstick, Eyeliner, Mascara, Blush), Other Types (Fragrances, Deodorants, Personal Care), and Distribution Channel (Offline, Online) across Men, Women, and Unisex users.
Regional Market Analysis and Geographic Performance
Geographic performance is led by Asia-Pacific, fueled by Indonesia and Malaysia, followed by the Middle East and Africa. Western markets in Europe and North America represent high-growth frontiers driven by multicultural consumer bases seeking ethical beauty alternatives.
In-Depth Regional Review of Key Halal Hubs
Southeast Asia acts as the manufacturing epicenter, supported by robust government backing for halal ecosystems. Meanwhile, Middle Eastern markets prioritize luxury formulations, demanding sophisticated supply chain integrity and premium packaging from regional and international participants.
Strategic Positioning of Leading Companies
Market leaders deploy distinct strategies: Wardah Cosmetics dominates mass retail in Indonesia with accessible pricing, whereas The dUCk Group Sdn Bhd targets premium lifestyle consumers through exclusive collaborations and high-end positioning.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of suppliers is moderate due to specialized halal-certified ingredients, while buyer power remains high owing to numerous emerging indie brands. Threat of substitutes is low, protected by strict religious compliance mandates.
SWOT Analysis of the Halal Personal Care Sector
Strengths include high consumer trust and ethical appeal; weaknesses involve complex cross-border certification hurdles. Opportunities lie in digital-first global expansion, while threats emerge from counterfeit certifications and non-halal brands launching greenwashed alternatives.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with ethically sourced, plant-based or synthetic ingredients free from animal derivatives and alcohol. Processing occurs in dedicated halal-certified facilities before moving through optimized offline and online distribution channels to end consumers.
Investment Insights and High-Potential Areas
High-potential investment areas include digital-native cosmetics brands catering to Gen Z consumers, and contract manufacturing facilities holding multi-jurisdictional halal accreditations to facilitate seamless international trade.
Conclusion and Key Strategic Takeaways
Reaching $72.81 Billion by 2033, the market offers lucrative avenues for stakeholders prioritizing supply chain transparency, digital expansion, and rigorous product certification to capture discerning consumer segments.
Research Methodology and Baseline Triangulation
Our findings are synthesized by combining primary interviews with regulatory officials and brand executives, cross-referenced with trade registry data, customs import-export logs, and secondary macroeconomic indicators to ensure robust baseline accuracy.
Scope of the Report and Coverage Parameters
This report covers global consumption, production, and regulatory frameworks of halal personal care products from 2026 to 2033, excluding non-certified conventional cosmetics that fail to meet strict Islamic compliance standards.
Recent Developments and Strategic Industry Moves
Recent milestones feature major partnerships between indie brands and regional e-commerce giants, alongside aggressive product line expansions into halal-certified anti-aging serums and eco-friendly color cosmetics by innovators like Flora & Noor Cosmetics LLC.