What is the scope and industry significance of the Phosphorus Ore Market?
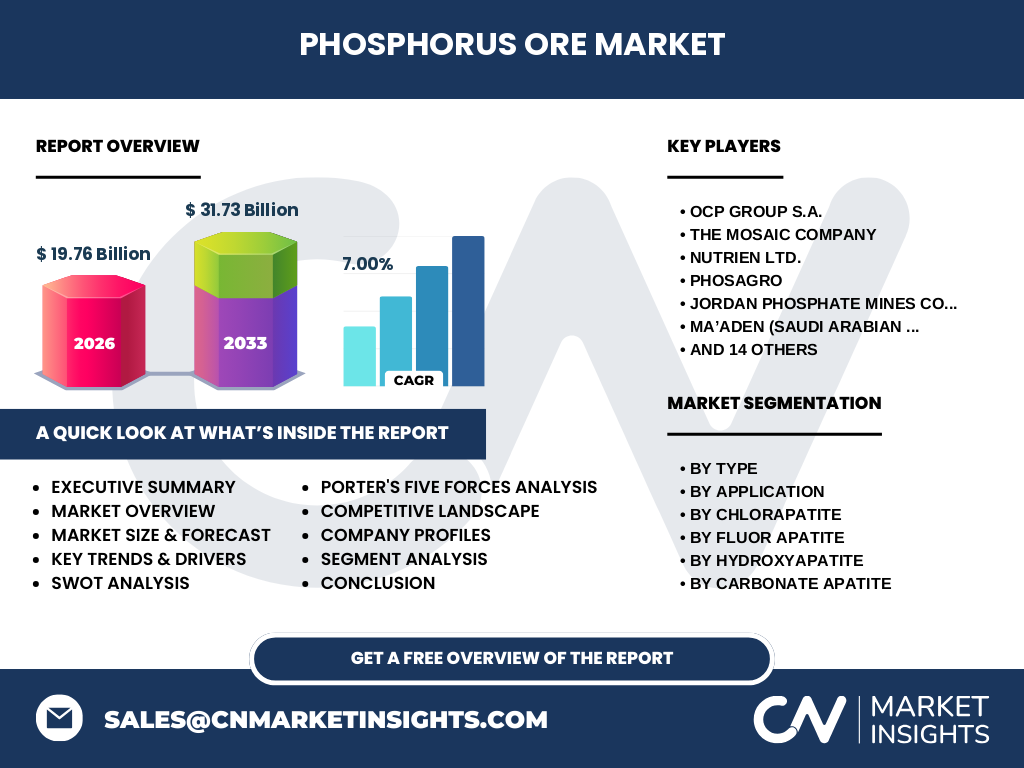
Our analysis indicates that the Phosphorus Ore Market reached a valuation of 19.76 Billion, serving as the foundational raw material for global agricultural fertilizers and advanced industrial chemicals. This sector underpins vital supply chains governed by complex trade regulations from bodies like the International Fertilizer Association.
What are the core drivers, restraints, and opportunities shaping the industry?
The market thrives on surging agricultural demand for high-grade Carbonate Fluorapatite and Fluor Apatite. However, stringent environmental compliance enforced by agencies like the EPA restricts open-pit mining expansion. Opportunities lie in upgrading low-grade ores via advanced flotation technologies to meet rising global food security mandates.
Emerging trends and growth patterns in the sector
Industry trends highlight a rapid pivot toward high-purity inputs for lithium-ion battery precursors. Major producers like OCP Group S.A. and The Mosaic Company are heavily investing in sustainable beneficiation methods to minimize ecological footprints while maximizing recovery yields from complex sedimentary deposits.
How did COVID-19 impact the sector and drive its recovery trajectory?
Pandemic-induced logistical bottlenecks severely disrupted maritime freight for key players like PhosAgro and Nutrien Ltd.. Nevertheless, post-pandemic food security priorities accelerated a sharp V-shaped recovery, boosting consumption across agricultural and industrial chemical applications.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is consolidated around state-backed giants and multinational conglomerates. Key participants such as Ma’aden, Yunnan Phosphate Group, and EuroChem Group AG leverage vertical integration—from captive mining assets to downstream phosphoric acid production—to insulate themselves against raw material volatility.
Executive Summary: Key Findings
Our comprehensive report reveals that the Phosphorus Ore Market is poised to expand from 19.76 Billion to 31.73 Billion by 2033, registering a robust 7.00% CAGR. Strategic asset acquisitions and technological investments in flotation processing will dictate future market leadership.
Market Forecast from 2027 to 2033
Based on our research, the market will scale rapidly to reach 31.73 Billion by 2033 at a 7.00% CAGR. This expansion is heavily propelled by escalating consumption of Industrial Chemicals and specialized animal feed formulations across developing economies.
Segmentation Analysis of Ore Types and Applications
The sector breaks down by type into Carbonate Fluorapatite, Fluor Apatite, Chlorapatite, Hydroxyapatite, and Carbonate Apatite. Application segments span Fertilizers, Animal Feed, Industrial Chemicals, and Food Additives. Processing methods like Crushing, Grinding, and Flotation determine final ore purity.
Geographic Distribution and Regional Performance
Regional performance is heavily skewed toward geographies with massive sedimentary reserves, such as North Africa, the Middle East, and Asia-Pacific. Companies like Jordan Phosphate Mines Company and Wengfu Group Company capitalize on strategic proximity to major export ports to dominate regional trade flows.
In-Depth Regional Review
Asia-Pacific commands significant volume due to intensive domestic fertilizer manufacturing by firms like Kailin Group and Guizhou Phosphate Chemical Group. Meanwhile, North American operations emphasize stringent environmental reclamation standards, while North African producers control the lion's share of global export reserves.
Company Profiles and Strategic Positioning
Leading entities exhibit distinct strategic advantages: OCP Group S.A. leverages unmatched North African reserves, The Mosaic Company focuses on vertically integrated North American distribution, and Vale S.A. phosphate division optimizes South American asset portfolios for high-efficiency agricultural deployment.
Porter's Five Forces Analysis
Bargaining power of suppliers remains moderate due to geographically concentrated reserves controlled by state enterprises. Threat of substitutes is remarkably low since phosphorus is biologically irreplaceable, though intense rivalry among established titans like PhosAgro and Nutrien Ltd. keeps pricing competitive.
SWOT Analysis of the Industry
Strengths include immense captive reserves and essential end-use demand. Weaknesses center on high carbon footprints from acidulation processes. Opportunities emerge in rare-earth element extraction from tailings, while threats involve tightening regulatory caps enforced by global environmental ministries.
Value Chain Analysis from Raw Material to End-User
The value chain initiates with open-pit extraction, followed by physical beneficiation through Crushing, Grinding, and Flotation. Processed ore transitions into phosphoric acid via wet-process methods before specialized manufacturers convert it into finished Fertilizers and Food Additives.
Investment Insights and High-Potential Areas
Investors should target technological innovators focusing on low-grade ore upgrading and phosphogypsum waste valorization. Companies integrating green ammonia with regional phosphate assets—exemplified by moves from Ma’aden—present compelling risk-adjusted entry points for long-term capital deployment.
Conclusion and Strategic Takeaways
The Phosphorus Ore Market offers compelling growth backed by a projected 7.00% CAGR reaching 31.73 Billion. Stakeholders must prioritize sustainable extraction technologies and strategic regional partnerships to navigate tightening environmental mandates successfully.
Research Methodology
Our baseline estimates are rigorously triangulated by combining proprietary trade registry data, primary stakeholder interviews with executives at firms like Foskor (Pty) Ltd. and Kazphosphate LLC, and secondary macroeconomic indicators sourced from international mining councils.
Scope of the Report and Limitations
This report covers global production, consumption, and trade dynamics across five primary mineral types and four key processing methodologies from 2026 through 2033. Limitations exclude clandestine domestic artisanal mining volumes and unverified state-subsidized reserve expansions.
Recent Developments and Strategic Moves
Recent industry momentum features joint ventures by Groupe Chimique Tunisien and strategic asset expansions by Centrex Metals. Industry leaders are actively forging cross-border supply agreements to secure long-term access to high-grade Fluor Apatite deposits amid rising geopolitical trade friction.