What is the scope and industry significance of the Point of Sale Display Market?
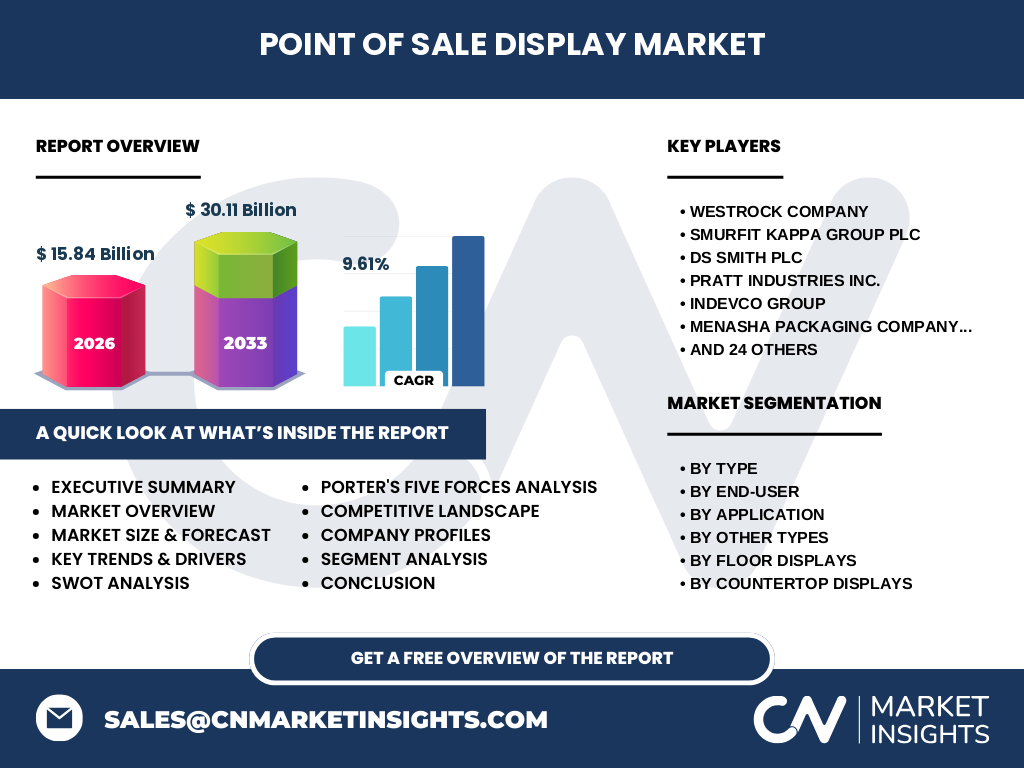
Our analysis indicates that the Point of Sale Display Market reached a valuation of 15.84 Billion in 2026. This ecosystem encompasses structural merchandising tools—ranging from corrugated cardboard shippers to interactive digital kiosks—designed to influence consumer purchasing decisions directly at retail checkout lanes and high-traffic aisle junctions across global retail environments.
Key market drivers, restraints, challenges, and opportunities shaping Point of Sale Display Market
The market is propelled by aggressive retail brand activations and the proliferation of impulse-buy zones. However, strict environmental compliance mandates regarding corrugated packaging disposal and volatile raw material costs for paperboard and resin act as notable restraints. Opportunities thrive in lightweight, sustainable substrates produced by innovators like WestRock Company and Smurfit Kappa Group plc.
Structural Growth Drivers and Emerging Trends
Industry trends highlight a definitive pivot toward sustainable merchandising units and smart retail integrations. Retailers increasingly demand modular structures that reduce freight carbon footprints. Key players such as DS Smith Plc and Pratt Industries Inc. are leveraging recycled fiber technologies to capture eco-conscious brand budgets.
COVID-19 Impact Analysis and Pandemic Recovery Trajectory
The pandemic severely disrupted physical retail environments, causing temporary freezes in brick-and-mortar display rollouts. Recovery materialized swiftly as non-essential retail reopened, supported by massive investments in hygienic sneeze-guard shields and touchless promotional displays manufactured by industry leaders like Menasha Packaging Company LLC.
Competitive Benchmarking and Strategic Dynamics
The Point of Sale Display Market industry trends reveal a moderately fragmented yet consolidated top tier where major packaging converters dominate large-scale retail programs. Enterprises such as InnoMark Communications and Great Northern Corporation maintain competitive moats through proprietary design engineering and robust national distribution networks.
Executive Summary of the Point of Sale Display Market Analysis
Our research underscores a pivotal inflection point for visual merchandising. Driven by omnichannel retail strategies, the sector is poised for exceptional expansion, demonstrating high-yield commercial viability for brand owners investing in versatile, high-impact physical displays.
Long-Term Market Forecast from 2027 to 2033
The data suggests the Point of Sale Display Market market size will surge from its baseline to reach 30.11 Billion by 2033, expanding at a robust CAGR of 9.61%. This accelerated growth trajectory reflects sustained investments in experiential brick-and-mortar retail environments.
Segmentation Analysis Across Formats and End-Users
Segmentation is categorized by type—encompassing Flour Displays, Freestanding Displays (rack, multi-tier, interactive), Countertop Displays (mini, tray, spinning, POP), and floor variants (standalone, dump bin, pallet, slatwall). End-user verticals span restaurants, retail, healthcare, warehouse, entertainment, and hospitality, servicing both mobile and fixed POS applications.
Geographic Distribution and Regional Market Performance
Regional performance varies based on localized retail density and supply chain maturity. North America and Europe currently dominate revenue share due to dense hypermarket networks, while Asia-Pacific represents the fastest-growing frontier driven by expanding modern trade infrastructure in urban centers.
In-Depth Regional Review of Manufacturing and Logistics Hubs
Regional ecosystems rely heavily on proximity to major corrugated box plants and multimodal shipping hubs. In North America, companies like Bay Cities Inc. and Rapid Displays Inc. capitalize on streamlined distribution channels to major port destinations and national retail distribution centers.
Company Profiles and Strategic Positioning
Market leaders differentiate through custom engineering, sustainable material sourcing, and end-to-end fulfillment services. Firms such as The Royal Group, INDEVCO Group, and MBC Signs deploy advanced digital printing and structural CAD design to secure multi-year contracts with tier-one consumer packaged goods brands.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to consolidated raw material markets for containerboard and plastics. Buyer power is high as large retailers dictate strict pricing and sustainability standards, while threat of substitution is mitigated by the unmatched tactile conversion power of physical retail displays.
SWOT Analysis of the Point of Sale Display Sector
Strengths include high impulse-purchase conversion rates and advanced structural design capabilities. Weaknesses involve high freight logistics costs for bulky assembled units. Opportunities lie in IoT-enabled smart digital displays, while primary threats stem from aggressive digital advertising migration.
Value Chain Analysis from Raw Materials to Retail End-Users
The value chain initiates with forestry and petrochemical raw material extraction, flowing through paper mills and resin extruders. Converters then transform these inputs via die-cutting and digital printing before logistics networks deliver finished units to retail store managers for end-consumer engagement.
Investment Insights and High-Potential Growth Pockets
High-potential areas center on lightweight, flat-pack corrugated floor displays and interactive digital POS integrations. Investors should target companies offering proprietary assembly-reduction designs that minimize in-store labor costs for major retail chains.
Conclusion and Strategic Takeaways for Industry Stakeholders
Sustained success in this sector requires continuous innovation in eco-friendly materials and smart retail technology integration. Brands and converters that align sustainability with high-impact visual appeal will capture disproportionate market share through 2033.
Proprietary Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary executive interviews with packaging converters, and secondary macroeconomic indicators from global retail associations, ensuring high-fidelity market sizing and forecasting accuracy.
Scope of the Report and Coverage Parameters
This report evaluates global market dynamics across specified product types, applications, and end-user verticals from 2026 to 2033. Limitations include localized tariff fluctuations and shifting retail real estate trends that may marginally impact regional growth velocities.
Recent Industry Developments, Partnerships, and Strategic Moves
Recent market activities feature strategic mergers, sustainable substrate innovations, and digital display integrations by key innovators such as Southern Imperial, RICH LTD., and Marvolus Manufacturing, reflecting an industry-wide push toward circular economy principles and enhanced consumer interactivity at checkout.