What is the scope and industry significance of the Freighter Aircraft Market?
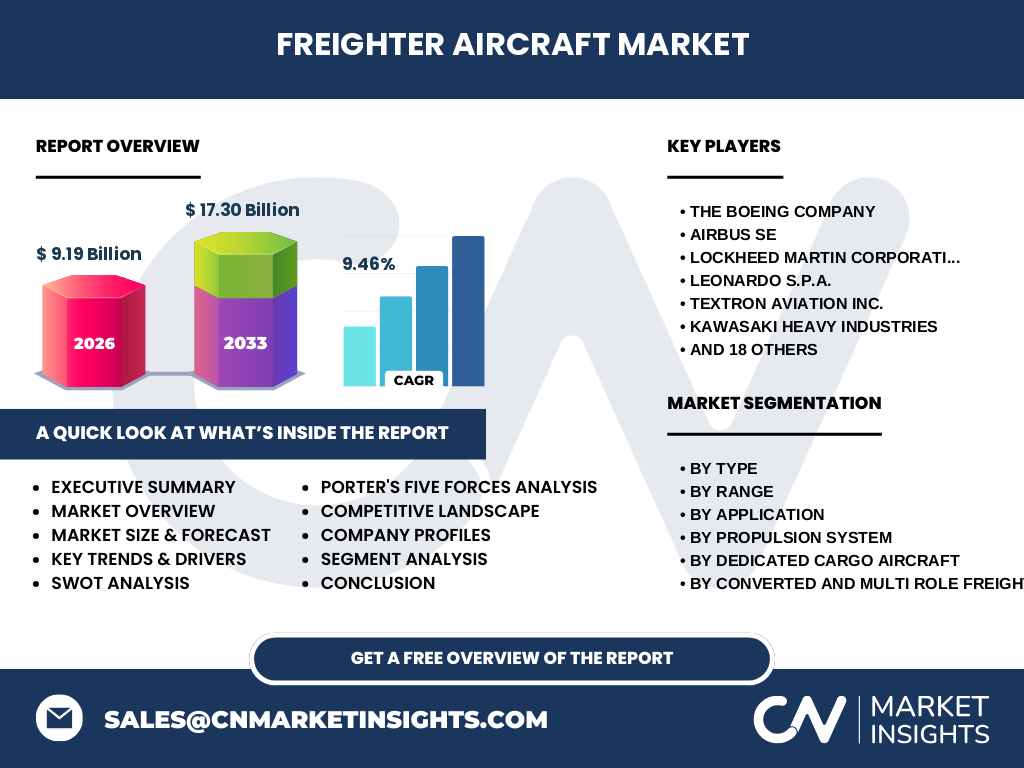
Our analysis indicates that the Freighter Aircraft Market represents a vital backbone of global supply chains, valued at 9.19 Billion in 2026. This sector encompasses dedicated cargo platforms and conversion units that facilitate high-value, time-sensitive logistics across international borders, operating under strict regulatory frameworks enforced by authorities such as the FAA and EASA.
Structural Growth Drivers and Restraints in the Freighter Aircraft Market
Growth in the Freighter Aircraft Market industry trends is heavily propelled by the exponential rise of cross-border e-commerce and pharmaceutical cold-chain demands. Conversely, severe supply chain bottlenecks for aerospace-grade titanium and skilled aircraft mechanics act as prominent operational restraints, challenging maintenance schedules across major hubs.
Emerging trends reshaping the cargo aviation sector
The sector is witnessing a rapid pivot toward sustainable aviation fuels (SAF) and advanced digital twin monitoring systems. Industry leaders like The Boeing Company and Airbus SE are increasingly optimizing wide-body freighter efficiency to comply with tightening ICAO carbon emissions mandates.
How did the COVID-19 pandemic transform operational trajectories?
The pandemic served as an unprecedented catalyst for the Freighter Aircraft Market, as grounded passenger fleets severely crippled belly-cargo capacity. This forced operators to accelerate Passenger-to-Freighter (P2F) conversions, establishing a resilient baseline recovery trajectory that continues to favor specialized operators like Kalitta Air LLC.
Competitive Benchmarking and Market Concentration
The competitive landscape remains an oligopoly dominated by aerospace behemoths alongside specialized conversion specialists such as Elbe Flugzeugwerke GmbH and IAI Bedek Aviation Group. Market concentration is high in the wide-body segment, forcing smaller tier-2 suppliers to carve out niches in quick-change and regional turboprop configurations.
Executive Summary: Key Findings on the Freighter Aircraft Market
Our comprehensive Freighter Aircraft Market analysis reveals a robust expansion path, projecting the market to surge from 9.19 Billion in 2026 to 17.30 Billion by 2033. This remarkable trajectory represents a compound annual growth rate (CAGR) of 9.46%, driven by sustained modernization needs among global logistics providers.
Market Forecast and Valuation Trajectory (2027 to 2033)
Based on our econometric modeling, the Freighter Aircraft Market market size will expand dramatically over the forecast period. Achieving 17.30 Billion by 2033 at a 9.46% CAGR reflects accelerating replacement cycles for aging narrow-body fleets and escalating demand for long-haul dedicated freighters.
Segmentation Analysis of Fleet Types and Applications
The market is fundamentally bifurcated into Dedicated Cargo Aircraft and Converted And Multi Role Freighter Aircraft. Furthermore, applications span commercial express logistics and military transport, while propulsion splits between jet and turboprop engines to address diverse mission profiles ranging from short-haul feeder routes to transoceanic heavy lift.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America leading in wide-body deployment due to major hub operations by The Boeing Company, while the Asia-Pacific region demonstrates the fastest growth rate. This regional acceleration is fueled by booming manufacturing output and expanding air freight infrastructure across key Chinese and Southeast Asian logistics centers.
In-Depth Regional Review and Operational Constraints
Our research highlights that European operators face stringent noise abatement regulations and slot constraints at major cargo gateways like Frankfurt and Leipzig. Meanwhile, Latin American and African markets heavily rely on rugged turboprop platforms from manufacturers like De Havilland Aircraft of Canada Limited to navigate underdeveloped ground infrastructure.
Strategic Positioning of Leading Industry Companies
Key market participants employ distinct differentiation strategies, with Airbus SE and The Boeing Company dominating original equipment manufacturing. Meanwhile, conversion leaders like PEMCO Conversions and KF Aerospace leverage proprietary supplemental type certificates (STCs) to extend the operational lifespan of passenger airframes into lucrative cargo assets.
Porter's Five Forces Assessment of Competitive Pressures
Supplier power remains moderately high due to the duopolistic nature of large commercial airframe manufacturing. Rivalry is intensely focused on fuel burn efficiency and payload-range optimization, whereas the threat of substitution is exceptionally low given the unmatched speed and global reach of freighter aircraft.
SWOT Analysis of the Global Cargo Aviation Ecosystem
Core strengths include established aerospace manufacturing ecosystems, while notable weaknesses involve high capital expenditure hurdles. Primary opportunities lie in surging e-commerce logistics, offset by external threats such as macroeconomic volatility and geopolitical trade restrictions impacting cross-border manufacturing.
Value Chain Analysis: From Raw Materials to End-Users
The value chain initiates with aerospace raw material providers supplying specialized aluminum and carbon composites, flowing through tier-1 aerostructure assemblers like Spirit AeroSystems and OEMs. The chain culminates with maintenance, repair, and overhaul (MRO) specialists such as AAR Corp. and Sabena Technics servicing airline end-users.
Investment Insights and High-Potential Growth Areas
Investors should direct capital toward passenger-to-freighter conversion facilities and sustainable propulsion technology startups. Companies possessing proprietary P2F engineering capabilities—such as Precision Aircraft Solutions—are particularly well-positioned to capture outsized margins during fleet transition cycles.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Freighter Aircraft Market offers compelling long-term fundamentals anchored by a 9.46% CAGR through 2033. Stakeholders must prioritize fleet flexibility, digital supply chain integration, and adherence to environmental mandates to successfully navigate this capital-intensive, high-growth sector.
Research Methodology and Baseline Triangulation
Our baseline estimates are derived through rigorous data triangulation, combining primary stakeholder interviews with C-level aviation executives, secondary macroeconomic indicators from IATA and ICAO, and proprietary trade registry databases tracking global aircraft registrations and MRO activity.
Scope and Parameters of the Market Research Report
This report covers global market dynamics, historical valuations, and future projections from 2027 to 2033 across all major aircraft types, propulsion systems, and geographic regions. Limitations include the exclusion of underground illicit cargo transport and private unlisted military-contracted logistical fleets.
Recent Developments and Strategic Industry Moves
Recent milestones include major P2F conversion line expansions by EFW Dresden and strategic partnership agreements between logistics giants and conversion specialists like Haeco Group. These moves underscore an industry-wide rush to secure conversion slots amid tightening global wide-body and narrow-body freighter availability.