What is the market overview and industry significance of the Coated Glass Market?
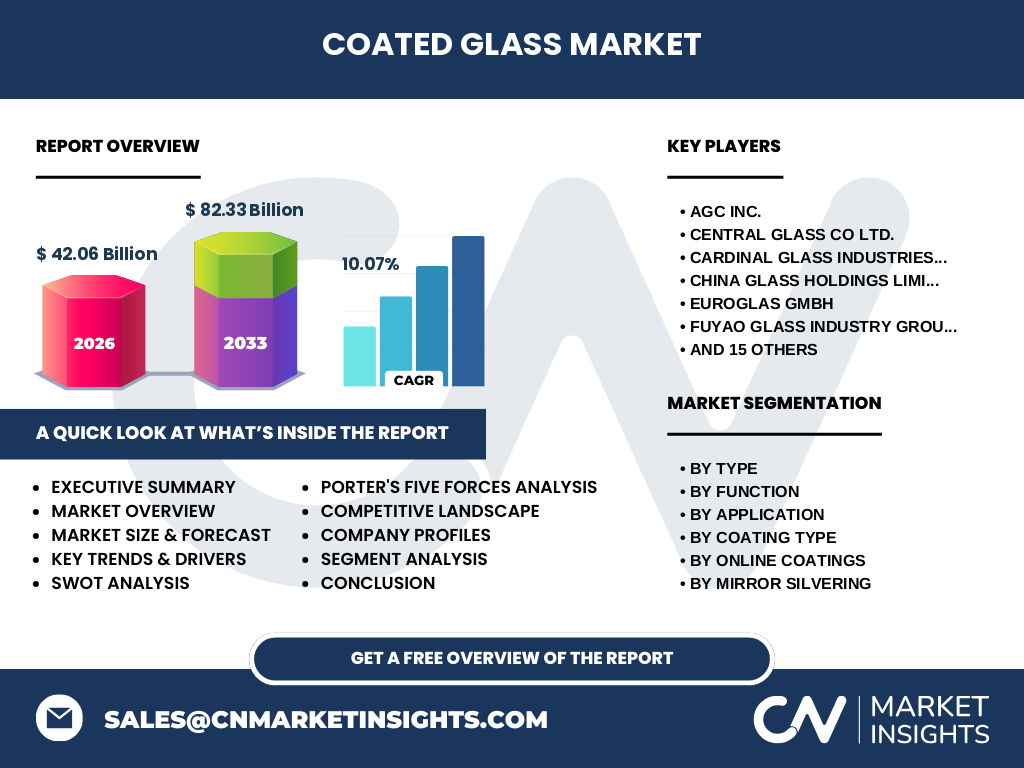
Our analysis indicates that the Coated Glass Market represents a cornerstone of advanced architectural and automotive engineering, valued at 42.06 Billion in 2026. This sector leverages chemical vapor deposition and magnetron sputtering to apply microscopic metallic oxides, enhancing thermal insulation, solar control, and emissivity profiles to meet stringent global energy codes.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Coated Glass Market?
Structural demand is propelled by stringent building energy efficiency mandates enforced by bodies like the US Department of Energy. However, high capital expenditures for pyrolytic and vacuum chambers act as restraints. Opportunities abound in smart-city initiatives requiring advanced solar control coatings to mitigate urban heat island effects.
Emerging trends and growth patterns in the Coated Glass Market
The market is witnessing a rapid pivot toward electrochromic and pyrolytic offline functional coatings that dynamically adjust solar heat gain coefficients. Our research highlights that urban developers increasingly favor multi-layer dielectric configurations to optimize daylighting while minimizing HVAC loads in commercial high-rises.
How did the COVID-19 pandemic impact the Coated Glass Market and dictate its recovery trajectory?
Pandemic-induced supply chain fractures and commercial construction halts temporarily suppressed demand in 2020. Recovery has been robust, accelerated by post-pandemic stimulus packages focusing on green infrastructure upgrades, pushing the market toward a projected valuation of 82.33 Billion by 2033.
Competitive benchmarking and strategic dynamics in the Coated Glass Market
Industry concentration is moderate to high, dominated by global innovators such as Saint-Gobain SA, Guardian Industries Corporation, and AGC Inc. These titans leverage extensive patent portfolios in offline functional coatings and strategic regional distribution networks to maintain pricing power against low-cost regional competitors.
Executive summary of key findings regarding the Coated Glass Market
Our comprehensive report reveals a robust market expanding at a 10.07% CAGR from 2027 to 2033. Growth is decisively anchored by commercial architectural retrofitting and lightweight automotive glazing requirements, necessitating continuous R&D investment in durable pyrolytic and magnetron-sputtered thin films.
Market forecast trajectory from 2027 to 2033
The data projects stellar expansion, scaling the market from its 2026 baseline of 42.06 Billion to reach 82.33 Billion by 2033. This trajectory is underpinned by accelerating urbanization across APAC economies and tightening carbon emission caps on residential and commercial real estate assets.
Segmentation analysis across product types, functions, applications, and coating methodologies
The ecosystem is segmented by type (Low E-Glass, Heat Reflective), function (Safety, Solar Control, Optics, Fire Rated), application (Automotive, Aerospace, Architecture, Electronics), and coating type (Online, Offline, Dielectric, Dichroic, Mirror Silvering). Architecture and Low-E coatings command the largest revenue shares due to universal green building mandates.
Regional market analysis and geographic performance distribution
Geographic performance is heavily skewed toward rapidly urbanizing zones in Asia-Pacific, followed by mature regulatory markets in North America and Europe. Localized building envelope regulations, such as the EU Energy Performance of Buildings Directive, dictate regional adoption rates for high-performance low-emissivity glass.
An in-depth regional review of high-growth territories
Asia-Pacific leads volume consumption, driven by massive infrastructural buildouts handled by players like Xinyi Glass Holdings Co Ltd. and China Glass Holdings Limited. Meanwhile, North America and Europe focus heavily on premium architectural retrofits utilizing advanced offline functional coatings to meet net-zero carbon targets.
Company profiles and strategic positioning of leading industry participants
Key industry architects include Vitro Architectural Glass, Corning Inc., and Schott AG. Vitro and Guardian focus heavily on high-performance architectural solar control solutions, whereas Corning specializes in ultra-thin optical and electronic-grade substrates, demonstrating how technical specialization drives competitive differentiation.
Porter's Five Forces analysis of the Coated Glass Market
Bargaining power of suppliers is moderate due to specialized raw float glass and rare metal requirements. Threat of substitutes remains low given the unique thermal and optical properties of coated glass, though intense rivalry among established titans compresses margins in commoditized segments.
SWOT analysis highlighting strategic strengths and vulnerabilities
Core strengths include superior thermal insulation properties and diverse architectural applications. Weaknesses stem from high capital intensity. Opportunities lie in IoT-integrated smart glass, while primary threats involve volatile raw material and energy costs required for high-temperature coating furnaces.
Value chain analysis from raw materials to end-user deployment
The value chain initiates with silica sand, soda ash, and metallic precursors, processed through float glass manufacturing, and advanced chemical or vacuum deposition. Value is aggressively captured further downstream by fabricators and installers supplying major architectural and automotive tier-one clients.
Investment insights, strategic recommendations, and high-potential areas
Investors should target niche sectors within offline functional coatings and multi-layer dielectric variants tailored for electronic and aerospace optics. Companies possessing proprietary durability enhancements for coastal or harsh climatic environments present the highest risk-adjusted return potential.
Conclusion and key takeaways for stakeholders
The Coated Glass Market offers exceptional compounding growth, supported by a 10.07% CAGR through 2033. Success requires aligning product portfolios with global decarbonization trends, prioritizing energy-efficient low-e solutions, and expanding manufacturing footprints in high-growth emerging economies.
Research methodology and baseline estimation triangulation
Our baseline estimates are rigorously triangulated by cross-referencing primary stakeholder interviews with C-level executives, secondary macroeconomic indicators from trade registries, and customs data concerning raw metal precursor shipments and float glass export volumes across major global ports.
Scope of the report, coverage parameters, and analytical limitations
This report encompasses global revenue evaluations from 2026 to 2033, analyzing qualitative and quantitative metrics across automotive, architectural, and optical sectors. Limitations include unforeseen geopolitical trade shifts and volatility in natural gas pricing utilized in pyrolytic coating operations.
Recent developments, corporate announcements, and strategic partnerships
Recent industry momentum features major capacity expansions by Sisecam Group and Nippon Sheet Glass Co Ltd., alongside joint ventures focused on scaling low-carbon manufacturing lines. These strategic moves emphasize sustainability, reduced furnace emissions, and enhanced coating durability.