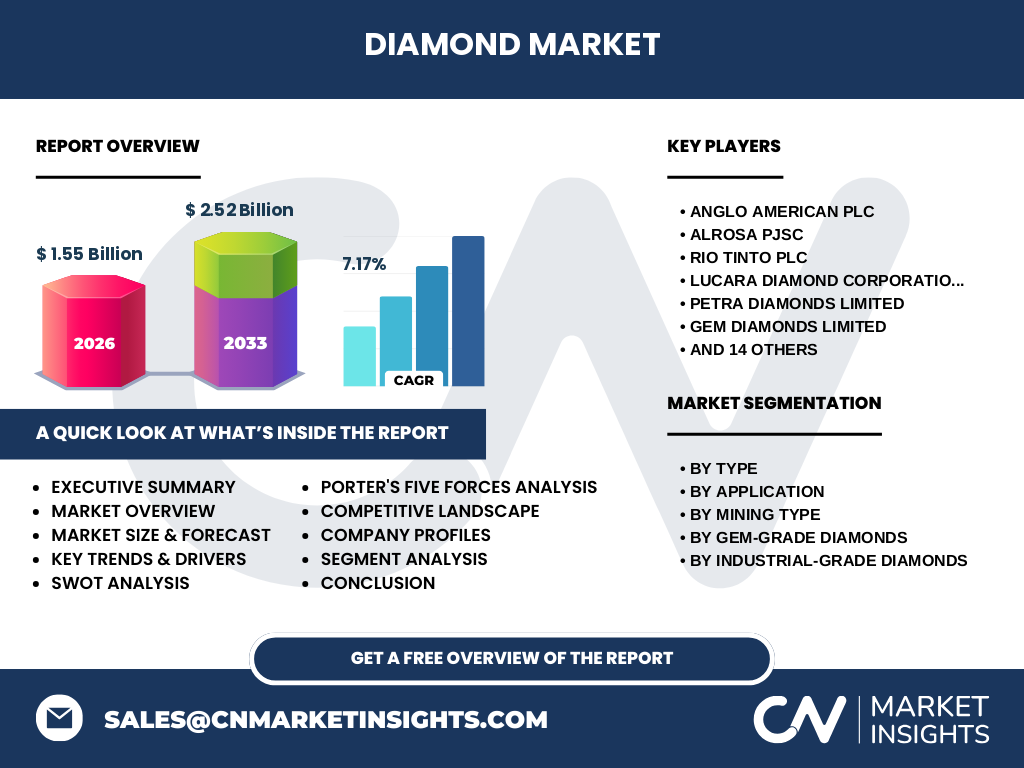
Market overview and structural scope of the Diamond Market
Our analysis indicates the Diamond Market size stands at 1.55 Billion, encompassing the complex global supply chain of natural gem-grade and industrial-grade carbon crystals. Regulated by bodies like the Kimberley Process, the industry spans high-clarity assets and abrasive-grade stones vital for manufacturing.
What are the primary drivers and restraints shaping the Diamond Market industry trends?
Growth is propelled by rising discretionary spending on jewelry manufacturing and robust demand for drilling-grade diamonds in infrastructure. Conversely, strict ESG compliance and ethical sourcing mandates imposed by regulatory frameworks act as notable operational restraints.
Emerging growth patterns within the Diamond Market
The data suggests a pronounced pivot toward traceable fancy-color diamonds and high-tech industrial applications. Producers are modernizing underground mining techniques to extract high-clarity assets efficiently while meeting strict environmental standards.
How did COVID-19 impact the Diamond Market and what does the recovery trajectory look like?
The pandemic caused severe supply chain disruptions across major cutting centers like Antwerp and Surat. Recovery has been driven by pent-up luxury demand and a digital-first transition among major miners like ALROSA PJSC and De Beers.
Competitive Benchmarking and Industry Concentration
The landscape is dominated by consolidated entities including Anglo American plc, ALROSA PJSC, and Rio Tinto plc. These giants control primary surface mining and underground mining operations, commanding significant pricing power across colorless and near-colorless categories.
Executive summary of the Diamond Market analysis
This comprehensive report projects the Diamond Market will expand from 1.55 Billion to 2.52 Billion by 2033, reflecting a steady 7.17% CAGR. Strategic opportunities abound in specialized abrasive-grade and high-clarity gem segments.
Diamond Market forecast through 2033
Based on our research, the industry is poised for sustained expansion, scaling from its 2026 baseline to reach 2.52 Billion by 2033. This trajectory is underpinned by steady 7.17% CAGR growth fueled by both industrial and luxury sectors.
Segmentation analysis across types and applications
Our research categorizes the sector into Gem-Grade Diamonds and Industrial-Grade Diamonds. Applications span luxury Jewelry Manufacturing and heavy-duty Industrial Applications, with mining split between Underground Mining and Surface Mining.
Regional market distribution and performance
Geographically, demand concentrates in North America and Asia-Pacific for luxury consumption, while industrial-grade sawing and cutting-grade stones see heavy uptake in industrialized zones driven by robust manufacturing sectors.
In-depth regional review of key diamond hubs
African producers such as Debswana Diamond Company and Catoca Mining Company dominate raw extraction via surface mining, while cutting and polishing hubs in India and Antwerp process high-clarity and colored stones for global export.
Strategic company positioning in the Diamond Market
Major industry participants like Lucara Diamond Corporation and Petra Diamonds Limited focus on recovering large, high-value stones using advanced X-ray transmission technology, differentiating themselves from bulk industrial producers.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to government regulations on rough diamond extraction, while buyer power is high in gem-grade categories owing to consumer substitution threats from lab-grown alternatives and alternative luxury goods.
SWOT evaluation of the global diamond industry
Strengths lie in natural asset scarcity and brand heritage. Weaknesses include high capital expenditure for underground mining. Opportunities emerge in tech-driven traceability, while threats stem from synthetic stone market penetration.
Value chain analysis from raw extraction to end-users
The value flow initiates at primary extraction sites managed by firms like Stornoway Diamond Corporation, moving through sorting centers like Okavango Diamond Company, cutting hubs, and finally to retail jewelry stores.
High-potential investment insights and strategic recommendations
Investors should target companies integrating advanced optical sorting technology and those securing ethical, traceable supply chains to capture premium pricing in the high-clarity gem and precision drilling segments.
Conclusion and core takeaways for stakeholders
The industry offers resilient growth prospects, driven by a solid 7.17% CAGR heading toward 2.52 Billion. Success requires balancing sustainable mining practices with digital provenance tracking.
Research methodology and data triangulation
Our findings combine primary stakeholder interviews with rough diamond trade registry data, customs import-export logs, and secondary macroeconomic indicators to establish reliable baseline estimates for the 1.55 Billion market.
Scope of the report and analytical limitations
This report covers global production, trade flows, and consumption trends across gem and industrial categories. Limitations include fluctuations in rough diamond rough pricing determined by producer sightholder allocations.
Recent developments, partnerships, and strategic moves
Recent industry shifts feature enhanced blockchain provenance initiatives by leading miners, expanded underground excavation projects by Letšeng Diamonds Limited, and strategic rough-allocation agreements by state-backed entities.