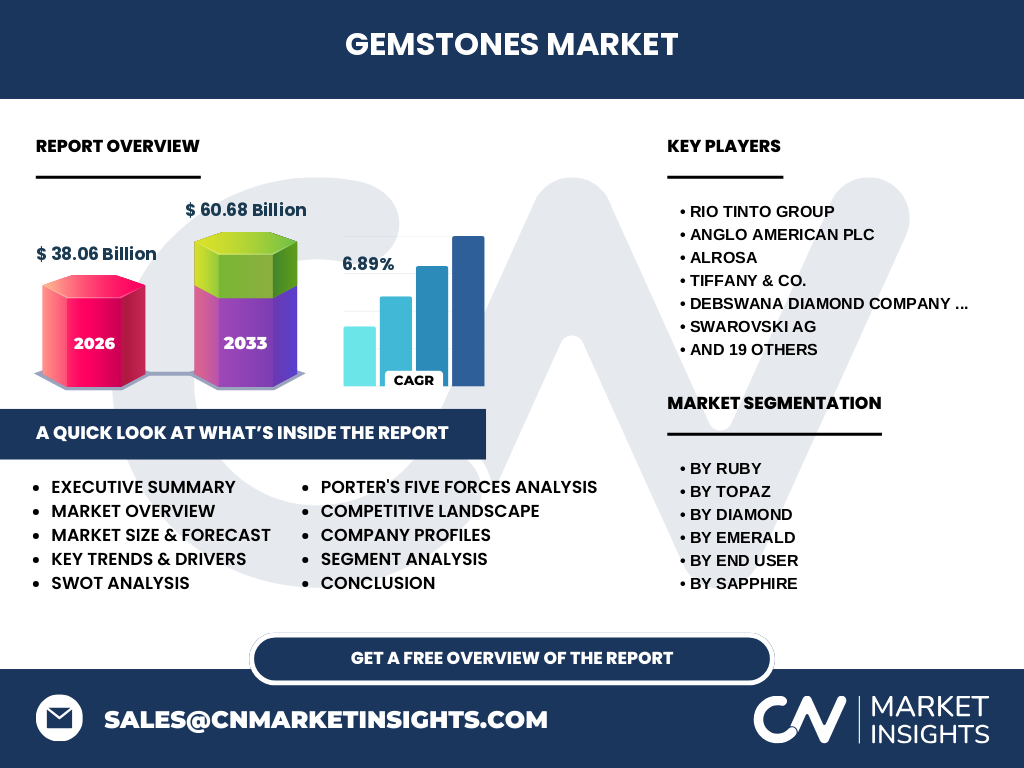
Market overview of the Gemstones Market
The Gemstones Market is valued at $38.06 Billion in 2026, encompassing the extraction, cutting, polishing, and global distribution of precious and semi-precious stones. Industry significance spans high-end jewelry manufacturing, bespoke luxury arts, and certified investment portfolios, driven by rigorous grading standards enforced by bodies like the Gemological Institute of America.
What are the primary growth drivers and market restraints?
Structural growth drivers include rising disposable incomes in emerging economies and surging demand for traceable lab-grown alternatives. Conversely, supply chain bottlenecks, strict ethical sourcing mandates from the Kimberley Process, and geopolitical restrictions on Russian rough diamond imports act as significant operational restraints for key market players.
Emerging trends and growth patterns in the Gemstones Market
Our analysis indicates a definitive pivot toward lab-grown transparency and blockchain-enabled provenance tracking. Consumers increasingly demand ethical verification for natural specimens, prompting innovators like Fura Gems Inc. and Burgundy Diamond Mines Limited to adopt hyper-transparent supply chain frameworks across retail channels.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and shuttered physical retail storefronts worldwide, severely impacting store-based luxury sales. However, the recovery trajectory has been robustly accelerated by the rapid digitalization of non-store-based distribution channels and an unprecedented surge in e-commerce luxury acquisitions.
Competitive benchmarking and strategic market landscape
Market concentration is characterized by a mix of vertically integrated mining conglomerates and iconic luxury houses. Giants like Rio Tinto Group, Alrosa, and Anglo American plc control primary rough extraction, while downstream titans like Tiffany & Co. and Swarovski AG dominate consumer-facing retail and brand equity.
Executive summary of the Gemstones Market
Driven by robust demand across luxury segments, the Gemstones Market is projected to surge from $38.06 Billion in 2026 to $60.68 Billion by 2033 at a CAGR of 6.89%. Strategic investments in synthetic production and digital omnichannel distribution represent the primary avenues for future enterprise profitability.
Market forecast from 2027 to 2033
Based on our research, the sector is slated for an expansion trajectory reaching $60.68 Billion by 2033, maintaining a steady compound annual growth rate of 6.89% starting from its $38.06 Billion baseline in 2026. This trajectory reflects sustained consumer appetite for both natural rarities and technological synthetic alternatives.
Segmentation analysis of product types and formats
The market is segmented by product types including Diamond, Emerald, Ruby, Sapphire, Alexandrite, Topaz, and other varieties like Amethyst and Tourmaline. Formats are divided into Natural and Synthetic, catering to divergent consumer preferences for traditional rarity versus sustainable lab-grown value.
Regional market analysis and geographic distribution
Geographic performance exhibits distinct regional concentrations, with Asia-Pacific leading in consumption due to cultural affinity for gold and colored gemstones. North America remains a dominant market for certified diamonds and branded luxury jewelry, while Africa serves as the primary epicenter for rough extraction via operations like Debswana Diamond Company Limited.
In-depth regional review of key markets
Key regional evaluations reveal that hubs like Antwerp, Dubai, and Jaipur remain vital B2B trading arteries. Jaipur acts as a primary global color-stone cutting center driven by specialists like Jindal Gems Jaipur, whereas North American markets prioritize digital-first retail experiences pioneered by platforms like Blue Nile Inc.
Company profiles and strategic positioning
Leading industry participants leverage distinct operational advantages. Lucara Diamond Corp. utilizes advanced X-ray transmission technology for large diamond recovery, Gemfields Group Limited focuses on ethically mined colored stones, and Petra Diamonds Limited targets mature asset optimization across major African kimberlite pipe operations.
Porter's Five Forces analysis
Supplier power remains moderate-to-high due to the concentrated ownership of prime kimberlite and pegmatite deposits by entities such as Mountain Province Diamonds Inc. and Gem Diamonds Ltd. Buyer power is balanced by brand loyalty in luxury segments, while substitution threat is intensified by high-purity synthetic diamond manufacturing.
SWOT analysis of the sector
Strengths include enduring cultural value and high asset liquidity. Weaknesses involve environmental extraction footprints. Opportunities lie in advanced synthetic stone customization and blockchain provenance, while threats include macroeconomic inflation curbing discretionary luxury spending and geopolitical trade sanctions.
Value chain analysis from raw materials to end-users
The industry value chain flows from primary extraction by firms like Arctic Star Exploration Corp. and Pangolin Diamonds Corporation through rough sorting and international grading. Stones then move to cutting centers in Surat or Antwerp before reaching end-users via store-based and non-store-based retail channels.
Investment insights and high-potential areas
High-potential investment avenues concentrate on technologically advanced synthetic cultivation facilities and traceable colored gemstone supply chains. Backing vertically integrated players such as Trans Hex Group (Pty) Ltd or Botswana Diamonds PLC mitigates upstream supply volatility for institutional investors.
Conclusion and key takeaways
The data demonstrates that the Gemstones Market is undergoing a structural evolution defined by technological disruption in synthetic creation and heightened demand for ethical transparency. Organizations that successfully adapt their omnichannel strategies will capture disproportionate share of the $60.68 Billion market by 2033.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining official trade registry data from mineral-rich jurisdictions, primary executive interviews with mining conglomerates like Stornoway Diamond Corporation and Rockwell Diamonds Inc., and secondary macroeconomic indicators regarding global luxury retail expenditure.
Scope of the report and coverage parameters
This report covers global market sizing, historical evaluations, and forecasts through 2033 across specified product types, formats, end-user applications including astrology and luxury arts, and distribution channels. Limitations include proprietary reserve data confidentiality among private mining syndicates and fluctuating rough stone auction prices.
Recent developments in the industry
Recent strategic moves feature increased joint ventures in synthetic diamond R&D, digital certification partnerships utilizing immutable ledger technology, and supply chain consolidation initiatives by firms such as Merlin Diamonds Limited and Bric Jewels Co. Ltd. to optimize rough-to-retail margins.