What is the scope and industry significance of the Methane Market?
Our analysis indicates that the Methane Market is valued at 149.26 Billion in 2026, serving as an indispensable backbone for global energy and chemical synthesis. This sector encompasses complex supply chains ranging from Conventional Natural Gas extraction hubs to emerging Power-To-Gas synthetic facilities, playing a critical role in powering industrial applications and fueling heavy transport.
Structural Growth Drivers and Restraints
The market faces a dynamic interplay of forces where surging industrial demand for Chemical Feedstock acts as a primary catalyst, while stringent environmental monitoring by bodies like the EPA imposes operational constraints. Capital expenditure is increasingly funneled into mitigating fugitive emissions, favoring firms capable of scaling Biogas and Landfill Gas purification technologies efficiently.
Emerging Trends and Growth Patterns in the Methane Market
The data suggests a pronounced pivot toward circular energy systems, with significant capital flowing into Fermentation and Gasification production methods. Major players are aggressively modernizing infrastructure to integrate synthetic pathways like Methanol-To-Gas (MTG), capturing market share through low-carbon fuel alternatives designed to meet tightening Scope 1 and Scope 2 emissions thresholds.
Pandemic Aftershocks and Recovery Trajectory
Following supply chain disruptions induced by COVID-19, the Methane Market rebounded sharply as industrial activity resumed across major manufacturing corridors. Strategic investments by operators such as BP plc and Shell plc accelerated digitalization of upstream assets, fortifying resilience against future logistical bottlenecks and stabilizing global distribution.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately high, characterized by dominant state-owned enterprises like China National Petroleum Corporation alongside agile multinational giants such as Exxon Mobil Corporation. Competitive advantage increasingly relies on proprietary carbon capture integration and strategic partnerships aimed at optimizing LNG supply chains across vital maritime choke points.
Executive Summary of Methane Market Research
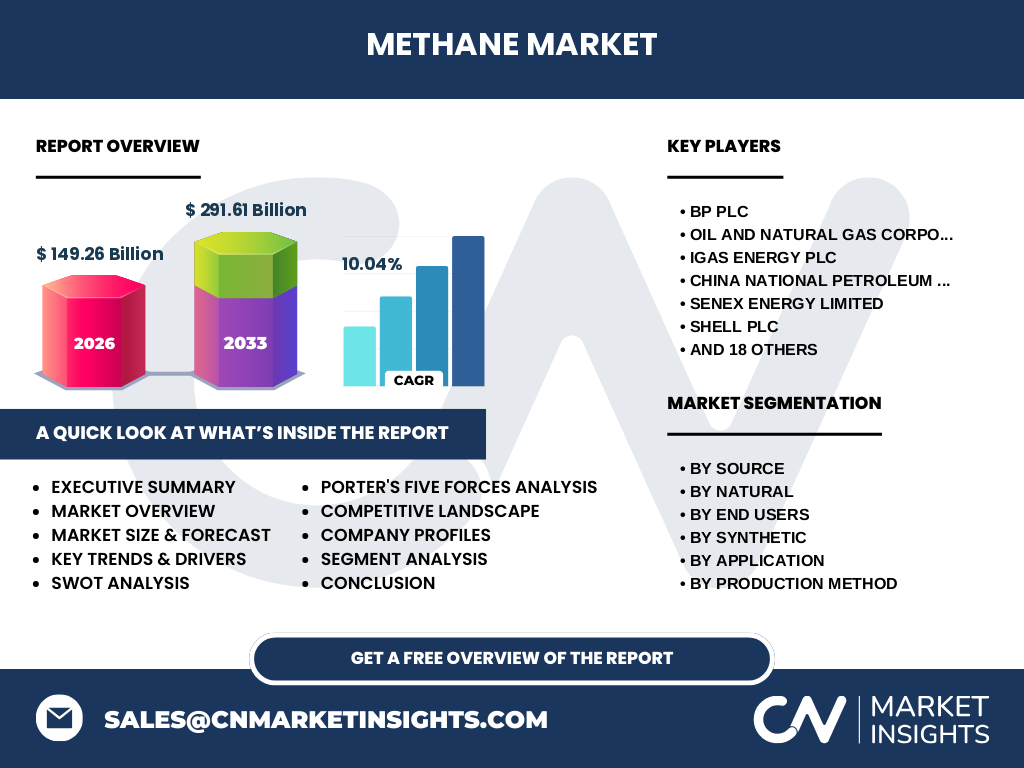
This comprehensive overview projects the Methane Market to expand from 149.26 Billion in 2026 to 291.61 Billion by 2033, registering a robust CAGR of 10.04%. Sustained demand across Automotive, Aerospace And Defense, and Power Generation segments underpins this exceptional growth trajectory, rewarding early adopters of advanced gasification techniques.
Long-Term Market Forecast from 2027 to 2033
Based on our research, the sector will maintain an accelerated CAGR of 10.04% through the forecast period, scaling from 149.26 Billion to reach 291.61 Billion by 2033. This expansion is heavily anchored in rising consumption of Liquefied Natural Gas and specialized chemical derivatives across developing industrial economies.
Segmentation Analysis of the Methane Market
The market bifurcates by Source into Natural (Conventional, Biogas, Landfill Gas) and Synthetic (MTG, Power-To-Gas, Gasification). End-user verticals span Automotive, Aerospace And Defense, Electrical, Chemical, and others, with Applications ranging from Fuel and Residential heating to specialized Liquid-Methane Rocket Fuel utilized in advanced aerospace propulsion.
Geographic Distribution and Regional Performance
Regional performance highlights distinct regulatory and infrastructural maturity, with Asia-Pacific leading in absolute consumption volume driven by chemical manufacturing clusters. Meanwhile, North America and Europe prioritize technological integration, injecting capital into advanced biogas recovery facilities and stringent pipeline leak-detection architectures.
In-Depth Regional Review and Localized Constraints
North American operations are heavily shaped by EPA mandates and regional pipeline capacity constraints, whereas Asian markets navigate surging domestic energy demand fueled by rapid urbanization. Companies like China National Offshore Oil Corporation and Chevron Corporation are actively adapting their regional asset portfolios to align with these localized logistical realities.
Company Profiles and Strategic Positioning
Industry leaders utilize distinct operational strategies, with firms like Linde plc and Air Liquide SA focusing on industrial gas purity and advanced separation technologies. Simultaneously, diversified energy titans such as TotalEnergies SE and Gazprom Neft PJSC leverage integrated upstream-to-downstream networks to capture maximum margin across the value chain.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of suppliers remains moderate due to specialized extraction technology requirements, while buyer power is tempered by essential utility and chemical feedstock demands. Threat of substitutes is mitigated by the unmatched energy density of conventional and synthetic methane in heavy industrial and aerospace propulsion applications.
SWOT Analysis: Strengths, Weaknesses, Opportunities, Threats
Strengths lie in deeply entrenched global distribution networks and versatile end-use applications. Weaknesses involve high capital expenditure for decarbonization. Opportunities abound in renewable synthetic pathways, while regulatory threats regarding methane leakage penalties require continuous technological vigilance and proactive compliance investments.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from upstream exploration of Conventional Natural Gas and organic waste collection for Biogas, through midstream liquefaction and pipeline transmission, terminating in downstream chemical synthesis and power generation. Value capture is increasingly concentrated at the midstream LNG processing and high-purity chemical feedstock stages.
Investment Insights and High-Potential Areas
Our analysis indicates prime investment opportunities in Power-To-Gas infrastructure and closed-loop Landfill Gas energy recovery systems. Investors should target technology providers specializing in emission abatement and synthetic fuel creation, as regulatory pressures will heavily favor low-carbon asset operators over traditional extractors.
Conclusion and Strategic Takeaways
The Methane Market represents a vital, evolving ecosystem poised to reach 291.61 Billion by 2033. Stakeholders must successfully balance aggressive growth targets with stringent environmental compliance, leaning on technological innovation in fermentation and gasification to secure long-term market leadership.
Research Methodology and Baseline Triangulation
Our analytical framework triangulates baseline estimates by synthesizing proprietary trade registry data, primary stakeholder interviews with executives at Shell plc and BP plc, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of both natural and synthetic production segments.
Scope of the Report and Coverage Parameters
This report evaluates the global Methane Market across specified sources, production methods, and end-user applications from 2026 through 2033. Limitations include inherent forecasting variances in emerging synthetic power-to-gas sectors influenced by rapid regulatory and geopolitical shifts.
Recent Developments and Strategic Industry Moves
Recent market dynamism is underscored by strategic joint ventures in renewable natural gas and heavy investments in LNG terminal expansions by firms such as Honeywell International Inc. and Osaka Gas Co. Ltd. These maneuvers highlight an industry-wide commitment to scaling efficiency and lowering carbon footprints.