Market overview and structural significance of the 3D E-Commerce Market
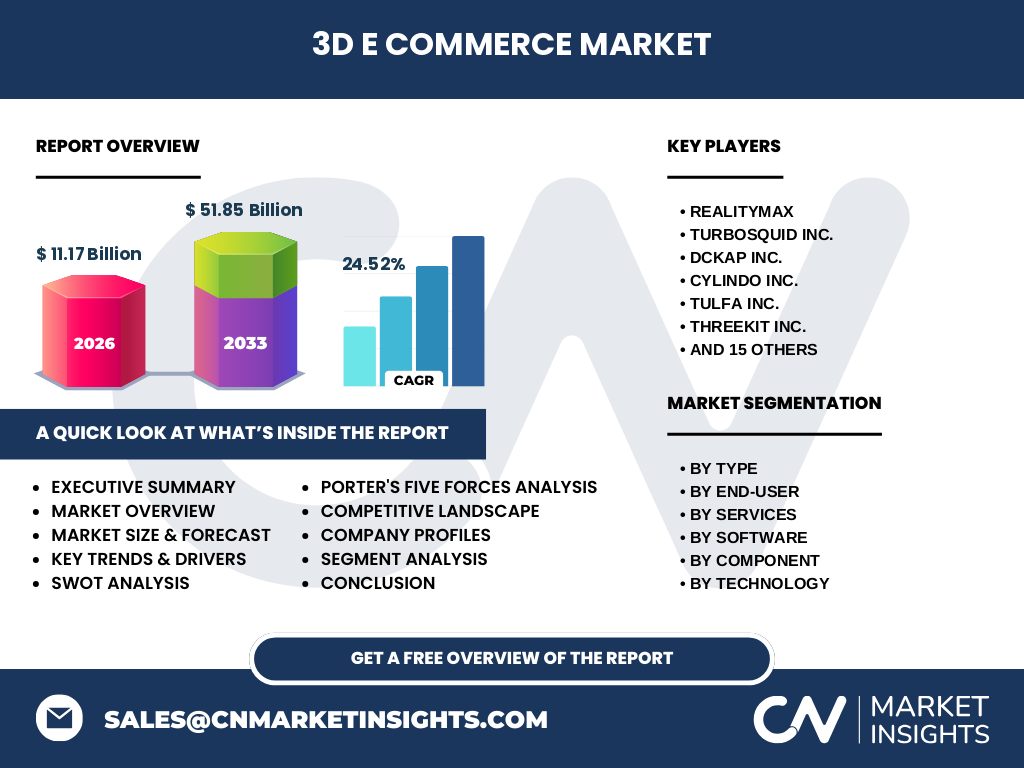
Our research establishes that the 3D E-Commerce Market reaches 11.17 Billion in 2026, revolutionizing online retail by replacing static imagery with immersive digital twins. This ecosystem spans advanced 3D Scanning, photogrammetry, and cloud visualization tools, empowering brands to bridge the physical-digital divide and significantly reduce consumer return rates across global digital storefronts.
What are the primary growth catalysts and operational restraints shaping the industry?
Structural growth stems from surging consumer demand for hyper-personalized shopping experiences and AR-driven visualization. However, high initial asset creation costs and technical pipeline bottlenecks act as persistent restraints. Innovators like Threekit Inc. and Cylindo Inc. are mitigating these hurdles by deploying scalable SaaS configuration engines.
Emerging tech trends transforming digital retail architecture
The shift toward real-time Artificial Intelligence (AI) and cloud-based rendering is redefining asset management. Companies are leveraging automated 3D model optimization services to compress complex geometry for mobile web deployment, enabling sub-second load times that directly elevate conversion metrics across high-traffic retail domains.
How did the COVID-19 pandemic reshape adoption trajectories?
Pandemic-era lockdowns forced an immediate pivot to contactless digital retail, accelerating enterprise investment in 3D product configurator tools by several years. Brands that previously relied on physical showrooms rapidly adopted solutions from pioneers like Marxent Labs LLC to maintain consumer engagement and sustain revenues.
Competitive Benchmarking and Market Concentration
The landscape features intense rivalry among specialized visual tech providers. Market leaders such as CGTrader Ltd., Expivi B.V., and VNTANA Inc. differentiate through proprietary asset pipelines and robust enterprise integration frameworks, creating formidable moats against generic software entrants.
Executive Summary of 3D E-Commerce Market dynamics
Driven by a robust CAGR of 24.52%, the market is poised for explosive expansion, scaling from 11.17 Billion in 2026 to 51.85 Billion by 2033. Enterprise investments are heavily concentrated in immersive AR/VR integration tools and automated rendering workflows to meet escalating consumer expectations for interactive product evaluation.
Long-term market valuation and growth trajectory through 2033
Our predictive models indicate sustained hyper-growth, expanding from the 2026 baseline of 11.17 Billion to reach 51.85 Billion by 2033. This trajectory is underpinned by widespread 5G rollout and pervasive consumer adoption of WebXR technologies across mobile and desktop browsing environments.
Detailed segmentation analysis across product categories
Segmentation spans multiple dimensions: By Type (3D Scanning, Photogrammetry, 3D Design, 3D Rendering), By End-User (Retail and Apparel, Home Décor and Furniture, Automotive, Electronics, Jewelry), By Services (Modeling, Optimization, Integration, Support), By Software (Visualization, Configurators, AR/VR, Asset Management), By Component (Software, Service), By Technology (Modeling, AR, VR, AI, Cloud), and By Application (Clothes, Automobile, Furniture).
Geographic distribution and macroeconomic performance
Regional performance varies based on local digital infrastructure maturity and retail sector digitization. North America commands the largest revenue share due to early tech adoption, while Asia-Pacific represents the fastest-growing frontier, fueled by expanding e-commerce penetration in apparel and consumer electronics.
In-depth regional review of high-growth territories
North America and Europe dominate commercial deployments, supported by heavy investments from localized innovators like Zakeke S.r.l. and Roomle AG. Meanwhile, Asia-Pacific markets show exceptional promise, driven by mobile-first consumer bases demanding interactive furniture and apparel visualization tools.
Strategic positioning of leading industry participants
Key market makers deploy distinct monetization strategies. RealityMAX and Danthree Studio focus on high-fidelity architectural and furniture visualization, whereas Brikl Limited and Mimeeq Inc. tailor their platforms for custom apparel and luxury goods configurations.
Porter's Five Forces assessment of industry competitiveness
Competitive rivalry is intense among established visualization platforms, while the threat of new entrants remains moderate due to high technical barriers in real-time rendering. Buyer bargaining power is offset by specialized integration demands, whereas supplier power is low given the abundance of underlying modeling talent.
SWOT Analysis of the sector
Strengths include dramatic conversion rate lifts and reduced returns. Weaknesses involve complex asset creation workflows. Opportunities lie in automated AI generation, while threats encompass fragmented technical standards and potential data privacy hurdles regarding spatial scanning inputs.
Value chain analysis from raw 3D assets to end-users
The value flow initiates with raw data capture via 3D scanning and CAD files. It transitions through specialized optimization and cloud-rendering layers managed by firms like TurboSquid Inc. and VividWorks Oyj, ultimately delivering immersive configurator experiences to end-users via standard web browsers.
Strategic investment insights and high-potential focus areas
Investors should prioritize enterprises developing zero-code 3D asset and content management tools and automated AI-driven photogrammetry pipelines. These technologies address the core industry bottleneck of scalable content creation, offering superior margin potential through software-as-a-service models.
Conclusion and core industry takeaways
The 3D E-Commerce Market has transitioned from a novelty to a foundational retail infrastructure. Achieving a projected 51.85 Billion valuation by 2033 underscores that immersive 3D and AR visualization are mandatory for modern brand survival and customer retention.
Robust research methodology and data triangulation
Our baseline estimates are derived from rigorous triangulation combining proprietary trade registry databases, primary executive interviews across leading tech vendors like NewArc.ai Ltd. and Expivi B.V., and macroeconomic indicators tracking global digital commerce expenditures.
Scope of the report and analytical coverage parameters
This comprehensive analysis evaluates global market dynamics, segment revenues, and competitive positioning from 2026 through 2033. Exclusions apply to offline-only industrial CAD applications, focusing strictly on consumer-facing e-commerce and retail visualization technologies.
Recent strategic developments, partnerships, and product launches
Recent ecosystem momentum highlights aggressive R&D spending on generative AI integration. Companies such as Nextech AR Solutions Corp. and DCKAP Inc. have forged strategic retail partnerships to embed real-time 3D configurators directly into major enterprise ERP and headless e-commerce architectures.