What is the scope and industry significance of the Welding Gas/Shielding Gas Market?
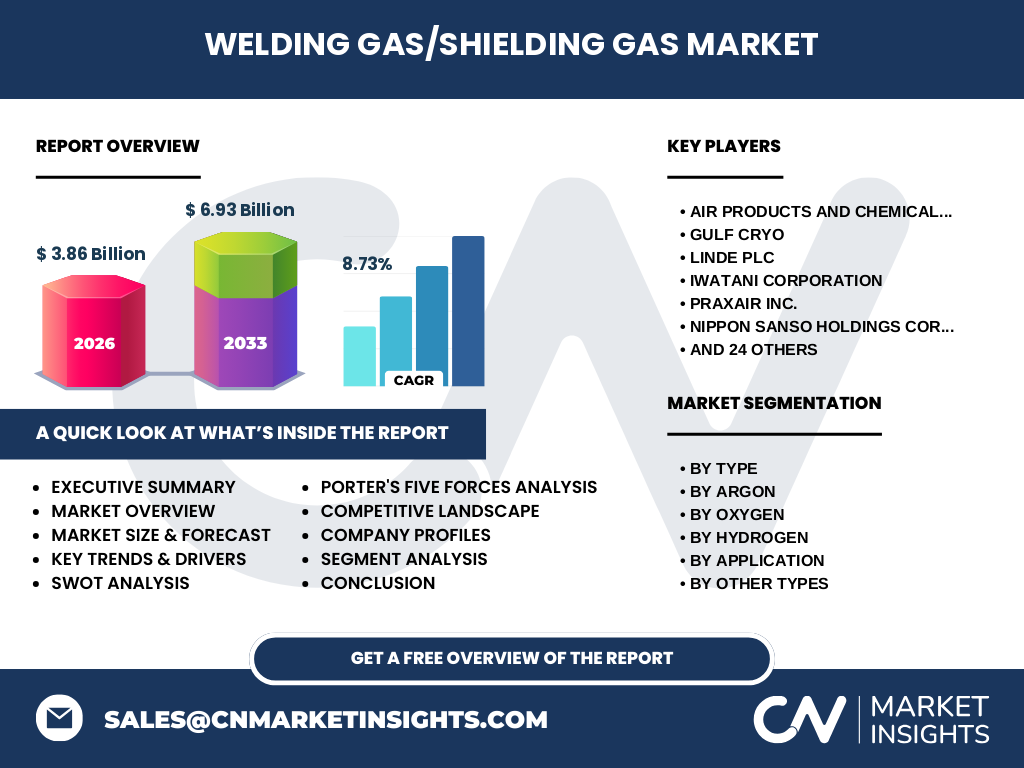
The Welding Gas/Shielding Gas Market encompasses specialized industrial gases utilized to protect metal arc welding zones from atmospheric contamination. Valued at 3.86 Billion in 2026, this sector is foundational for structural integrity across heavy manufacturing, energy infrastructure, and aerospace fabrication. Pure gases and complex mixtures dictate weld quality, penetration profiles, and mechanical properties.
Key market drivers, restraints, challenges, and opportunities shaping Welding Gas/Shielding Gas Market
Our analysis indicates that surging infrastructure investments and automated GMAW adoption act as primary structural drivers. Conversely, stringent environmental mandates by bodies like the EPA and compressed gas supply chain bottlenecks represent acute restraints. Opportunities proliferate within high-purity specialty gas mixtures for aerospace applications, directly benefiting innovators optimizing cylinder logistics.
Emerging trends and growth patterns in Welding Gas/Shielding Gas Market
The market is witnessing a decisive shift toward advanced Argon-CO2 mixtures and automated gas delivery systems. Industry trends highlight a growing preference for bulk merchant liquid distribution to lower unit costs in high-volume fabrication plants, favoring Tier-1 suppliers capable of on-site cryogenic storage solutions.
How did COVID-19 impact the Welding Gas/Shielding Gas Market and what is the recovery trajectory?
The pandemic induced severe supply chain disruptions and temporary shutdowns across automotive and metal manufacturing hubs. However, the post-pandemic recovery trajectory has been exceptionally robust, fueled by stimulus-backed infrastructure projects that rapidly accelerated baseline demand back toward an impressive long-term expansion path.
Competitive benchmarking and strategic dynamics in the Welding Gas/Shielding Gas Market
The competitive landscape is consolidated around global giants like Linde PLC, Air Products and Chemicals Inc., and Nippon Sanso Holdings Corporation. These leaders leverage proprietary air separation units and extensive merchant liquid distribution networks to maintain pricing power, while regional players like Gulf Cryo and Iwatani Corporation dominate localized industrial clusters.
Executive summary of high-level findings for the Welding Gas/Shielding Gas Market
Our proprietary research demonstrates that the Welding Gas/Shielding Gas Market is poised for accelerated expansion, projecting growth from 3.86 Billion in 2026 to 6.93 Billion by 2033 at a robust 8.73% CAGR. Metal manufacturing and automated applications anchor this trajectory.
Market forecast trajectory from 2027 to 2033
Based on our econometric modeling, the market will scale from its 2026 baseline to reach 6.93 Billion by 2033, maintaining an unbroken 8.73% CAGR. This accelerated valuation is underpinned by rising fabrication standards across emerging economies and continuous technological upgrades in gas metal arc welding.
Segmentation analysis across types, applications, and end-users
The market segments by type into Argon, Carbon Dioxide, Oxygen, Hydrogen, and Specialty Gas Mixtures. Applications span Gas Metal Arc Welding, Gas Tungsten Arc Welding, and others, servicing end-users across Metal Manufacturing, Construction, Energy, and Aerospace via Cylinder or Bulk distribution modes.
Geographic distribution and regional performance analysis
Regional performance is heavily skewed toward industrialized zones with dense manufacturing infrastructure. North America and Asia-Pacific lead consumption, driven by heavy construction and advanced aerospace fabrication, while stringent European regulatory frameworks push adoption toward high-efficiency shielding gas mixtures.
In-depth regional review of high-growth territories
Asia-Pacific represents the most dynamic regional market, propelled by rapid industrialization in emerging manufacturing hubs. North America follows closely, anchored by stringent American Welding Society standards and massive investments in domestic energy infrastructure, driving sustained demand for high-purity argon and helium blends.
Strategic positioning of leading companies in the industry
Industry titans such as The Messer Group GmbH, Praxair Inc., and Lincoln Electric Holdings Inc. anchor their market positions through vertically integrated gas production and proprietary welding equipment synergies. Regional specialists like American Welding Gas Inc. and Holston Gases Inc. secure market share through localized customer service and agile cylinder delivery.
Porter's Five Forces analysis of competitive pressures
The industry exhibits moderate-to-high supplier power due to the capital-intensive nature of air separation plants. Buyer power is mitigated by long-term supply contracts, while the threat of substitutes remains low given the irreplaceable chemical role of shielding gases in structural metal fusion.
SWOT analysis of the Welding Gas/Shielding Gas Market
Key strengths lie in essential industrial utility and entrenched supply chains. Weaknesses involve high distribution logistics costs for cryogenic liquids. Opportunities center on renewable energy infrastructure projects, whereas regulatory compliance costs and raw material price volatility represent persistent threats.
Value chain analysis from raw materials to end-users
The value chain originates with air separation and chemical processing of atmospheric raw materials. Gases are then purified, compressed, and transported via merchant liquid bulk or packaged cylinders through specialized distributors like WestAir Gases & Equipment to end-fabricators.
Investment insights and high-potential strategic areas
Investors should target high-purity specialty gas production facilities and digitalized cylinder tracking logistics. Companies investing in automated gas mixing technologies designed for robotic welding cells present exceptional capital appreciation potential over the forecast period.
Conclusion and core takeaways for market stakeholders
The Welding Gas/Shielding Gas Market offers compelling growth backed by an 8.73% CAGR through 2033. Stakeholders must prioritize supply chain resilience, sustainability compliance, and strategic alignment with automated fabrication technologies to capture emerging market share.
Research methodology for baseline estimations and data triangulation
Our baseline estimates are rigorously triangulated by cross-referencing primary stakeholder interviews with C-level executives, official trade registry data, and secondary macroeconomic indicators from global industrial associations to ensure absolute market sizing accuracy.
Scope of the report, coverage parameters, and operational limitations
This report covers global market dynamics for the Welding Gas/Shielding Gas Market from 2026 to 2033, broken down by type, application, end-user, and distribution mode. Limitations include unforeseen geopolitical trade shocks and localized raw material supply disruptions.
Recent developments, product launches, and strategic partnerships
Recent industry momentum features major cryogenic capacity expansions by Linde PLC and strategic distribution acquisitions by regional players like NexAir LLC and Arc3 Gases. These moves aim to optimize regional delivery routes and secure long-term industrial gas supply security.