Market overview and industry significance of the Synthetic Gemstone Market
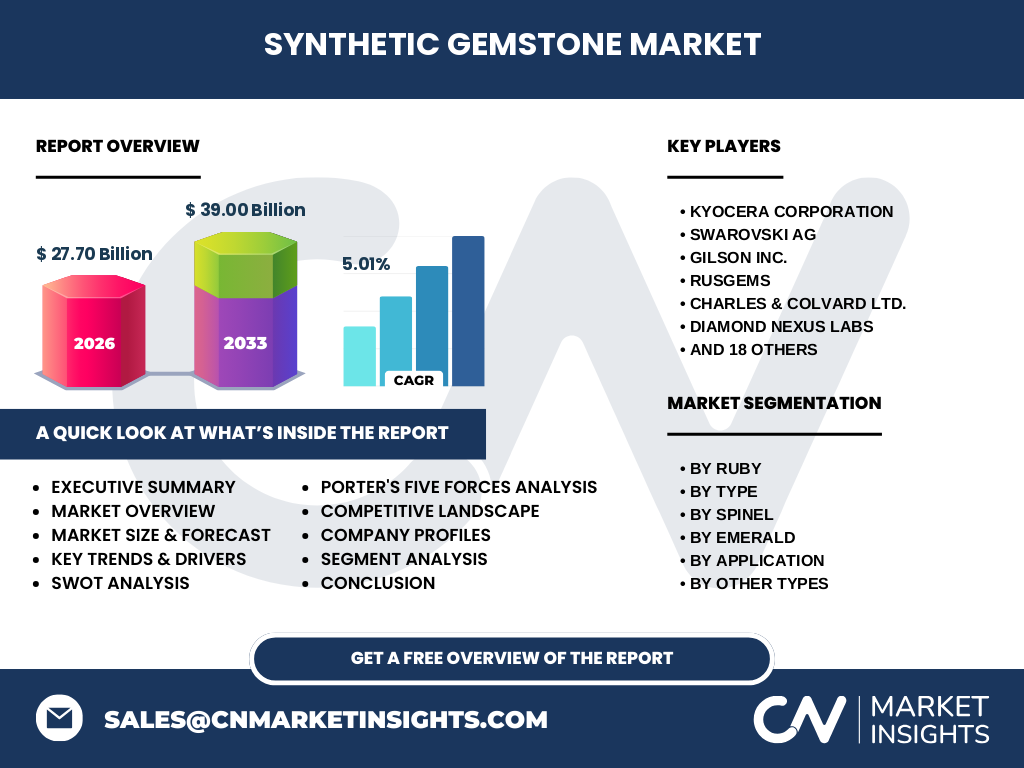
Our analysis indicates that the Synthetic Gemstone Market reaches a valuation of 27.70 Billion in 2026. This sector encompasses laboratory-grown ruby, emerald, and spinel produced via sophisticated techniques like the Czochralski and hydrothermal processes, serving both high-end jewelry and precision industrial instruments.
Structural Growth Drivers and Market Restraints
Growth is propelled by consumer demand for ethically sourced jewelry, championed by innovators like MiaDonna and ALTR Created Diamonds. However, the Synthetic Gemstone Market industry trends face restraints from high energy costs required for HPHT and CVD reactors, alongside complex customs hurdles at major ports.
Emerging trends in laboratory-grown gemstone production
The shift toward sustainable luxury is accelerating. Producers like Diamond Foundry and Greenlab Diamonds are leveraging renewable energy to manufacture eco-conscious stones, directly addressing stringent Federal Trade Commission disclosure guidelines for cultured specimens.
COVID-19 impact analysis and pandemic recovery trajectory
The pandemic caused severe supply chain disruptions across primary manufacturing hubs in Asia and Europe. Despite initial retail contraction, the Synthetic Gemstone Market rebounded swiftly as digital-first distribution channels by brands like Swarovski AG captured locked-down consumers seeking value.
Competitive landscape and strategic market concentration
Market concentration remains moderately fragmented, featuring industrial giants alongside agile specialists. Kyocera Corporation and Element Six dominate technological applications, while consumer-facing pioneers like Charles & Colvard Ltd. capture significant share in fine jewelry segments.
Executive summary of the Synthetic Gemstone Market analysis
The Synthetic Gemstone Market demonstrates robust resilience, underpinned by a projected market size of 39.00 Billion by 2033. Strategic investments in hydrothermal and flux-growth methods by players such as Chatham Inc. continue to drive margin expansion.
Market forecast from 2027 to 2033
Our research forecasts the market to expand at a steady 5.01% CAGR from 2027 to 2033, culminating at 39.00 Billion. This trajectory is supported by rising industrial consumption of synthetic sapphire and garnet in optical instruments.
Segmentation analysis across product types and applications
Segmentation is categorized by product, process, application, and distribution. Key segments include: By Type: Ruby, Emerald, Spinel, and Other Types. By Application: Jewelry, Instrument, and Other Applications. By Distribution: Online and Offline channels.
Regional market analysis and geographic distribution
Geographic performance highlights robust adoption across North America and Asia-Pacific. Regulatory backing from bodies like the Gemological Institute of America facilitates transparent consumer trust, aiding regional distributors and specialized jewelers like Vera Bijou.
In-depth regional review of manufacturing and consumption hubs
Asia-Pacific dominates production volume, anchored by major industrial manufacturers such as Henan Huanghe Whirlwind Co Ltd and Zhongnan Diamond Co Ltd. Meanwhile, North America leads in retail consumption, driven by direct-to-consumer innovators like Pure Grown Diamonds.
Company profiles and strategic positioning of leading firms
Industry leaders maintain distinct competitive advantages through proprietary synthesis tech. RusGems and Tairus specialize in advanced hydrothermal emeralds, whereas Scio Diamond Technology Corporation focuses on specialized electronic and optical grade materials.
Porter's Five Forces analysis of competitive intensity
The Synthetic Gemstone Market exhibits moderate-to-high competitive rivalry driven by rapid technological advancements. Threat of substitutes remains low due to precise physical matching with mined gems, while supplier power over high-purity graphite and seed crystals is elevated.
SWOT analysis of the laboratory-grown gemstone sector
Strengths include ethical provenance and flawless optical clarity. Weaknesses involve high capital expenditure for Czochralski furnaces. Opportunities lie in technological instrumentation, while threats stem from unregulated influx of low-cost imports affecting traditional brands like Gilson Inc.
Value chain analysis from raw materials to end-users
The value chain initiates with ultra-pure chemical inputs and carbon sources. Mid-stream operations involve energy-intensive synthesis by firms like Zhengzhou Sino‑Crystal Diamond Co Ltd and Sumitomo Electric Industries Ltd, flowing downstream to jewelry artisans and instrument makers.
Investment insights and high-potential areas
Investors should target emerging hydrothermal production facilities and direct-to-consumer digital platforms. Companies integrating sustainable energy matrices—exemplified by New Diamond Technology LLC—demonstrate superior long-term valuation potential within the Synthetic Gemstone Market industry trends.
Conclusion and key takeaways for stakeholders
The Synthetic Gemstone Market offers compelling growth, moving from 27.70 Billion in 2026 toward 39.00 Billion by 2033. Strategic alignment with sustainability metrics and technological precision remains paramount for long-term stakeholder profitability.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registries, primary stakeholder interviews with executives from Diamond Nexus Labs and Biron Gems, and secondary macroeconomic indicators sourced from international gemological associations.
Scope of the report and coverage parameters
This comprehensive report evaluates the global Synthetic Gemstone Market market size across specified product categories, distribution networks, and regional jurisdictions. Exclusions apply to unregistered artisanal grey-market operators lacking verifiable compliance metrics.
Recent developments, strategic partnerships, and product launches
Recent milestones include strategic capacity expansions by Veynou and collaborative retail partnerships aimed at scaling eco-friendly jewelry lines. These moves reflect aggressive positioning to capture rising consumer preference for certified laboratory-created alternatives.